

[I originally wrote this in 2022 and revised it in July 2026]
I recently watched a discussion between an academic and a central banker that exposed an intergenerational amnesia that is undermining financial stability and economic wellbeing for all.
The presentation was by Moritz Schularick, an economist I deeply respect for having stewarded the compilation of some of the first multi-country and multi-century economic datasets that include data points on banking crises and bank money creation (bank credit). In his talk, Schularick was explaining some of his team’s learnings from analyzing dozens of banking crises in 17 countries over a 140 year period.
Dear reader: If hearing “banking crises” doesn’t put your nervous system on high alert, you may not be aware of Moritz’s earlier work showing that bank-led credit crises trigger extra destructive economic crises. Economic recessions caused by bank lending booms and busts have longer and deeper periods of unemployment, more business bankruptcies, and worse debt crises for households, businesses, and governments (when compared to recessions caused by natural disasters, wars, etc). So, if you dislike living through economic crises, you should be very concerned about banking crises!
The proof that banking crises are completely preventable
During his talk, Schularick showed the following chart of banking crises that have taken place since 1870 in seventeen countries. I’ve re-created it to remove text that distracts from seeing the pattern:

After speaking about all the things his team had learned by studying central banks’ responses to each of the banking crises, Schularick received a question from a leading economist for the Bank of France:
“On the table there was almost nothing between 1930 and 1990. There is a big chunk in the table which is blank. So I was wondering: Is it true that there were no banking or financial crises at that time?”
- Bussiére Matthieu, Phd, Director of the Directorate, Economics and International and European Relations, Banque de France
Schularick explained during the Q&A that his catalog of banking crises has been corroborated by three different methods, two quantitative and one qualitative.
So, it’s a fact. Seventeen countries figured out how to completely eliminate banking crises for three decades, after averaging eight crises per decade before and 6 per decade since. In a 2013 paper, Schularick and his co-authors dubbed this remarkable interlude an “oasis of calm.”
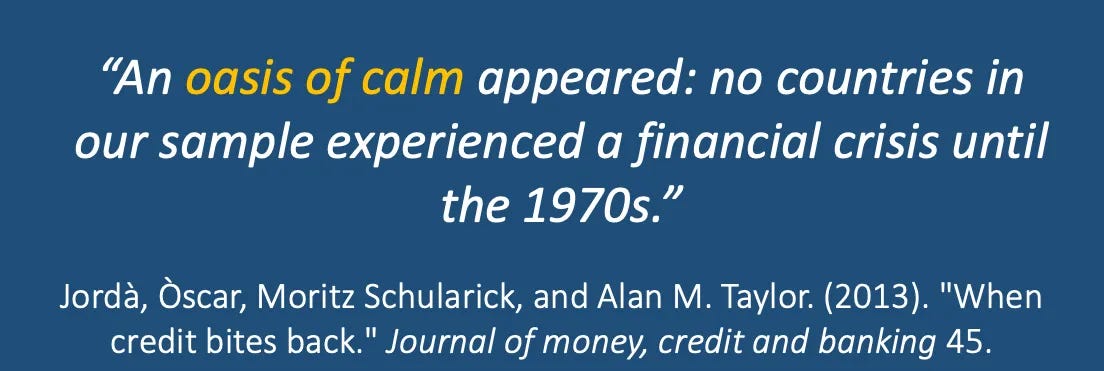
The important thing about the interlude is what it signals about what is possible today. We don’t have to endure banking crises. A recipe for banishing banking crises from modern civilization has been discovered, proven, and could be applied again, now. Below, I give a high level summary of the recipe, but first I want to talk about why this is a worrying blindspot and what is at stake.
Amnesia in a bad place
Now, just to put Matthieu’s comment in perspective, you need to understand that the Bank of France is the central bank of France. As the bank’s director of economics and international relations, Matthieu is an active participant in international negotiations about how the Euro currency is managed by the European Central Bank. He also is involved in decisions about how European central banks regulate the banks in their countries to ensure stability.
It would be reasonable to think that someone in Matthieu’s role would be aware of previous eras of highly stable banking. In fact, you would think that he would be studying such eras carefully for lessons to apply today.
However, Matthieu’s question for Schularick revealed that he was completely unaware of the period in the middle of the last century when there wasn’t a single banking crisis in 17 countries for a period ranging between 30 and 50 years, depending on the country. This is not a knock on Matthieu. The fact that no one had told him that a previous generation of governments and their central bankers had figured out how to completely eliminate banking crises reflects a blindspot in the instruction of economics. I have looked in many textbooks and never seen it mentioned.

If Matthieu was not aware of this “oasis of calm,” as Schularick’s team dubs it, it seems safe to assume that many of the other central bankers participating alongside Matthieu in high-level monetary policy and bank regulation conversations in the EU are similarly unaware. If they were aware, one could reasonably expect them to be having urgent conversations about why their leadership over the past two decades has failed to match the perfect multi-country banking system stability achieved by a previous generation of leaders between 1940 and 1970. Instead, what I see in conversations is constant reference to avoiding the worst (another 2008 crisis) and “promoting stability” rather than matching the perfect systemic stability of the “oasis of calm” era.
To test if this gap is also present in multilateral organizations, I once showed the above charts to a senior World Bank economist at the joint IMF/World Bank meetings in DC. I asked if he’d heard deliberations centering the success of the last mid-century. He confirmed that (1) he’d never heard such a conversation and (2) he’d not previously been made aware of the oasis of calm. He cautioned, naturally, that he’s not privvy to every conversation.
These are anecdotes, of course, but I have seen no evidence of such a conversation within banking policy and regulation deliberations, whether written in reports or discussed in oral presentations. I’d be interested in whether others with visibility into conversations at high levels of banking governance have seen such discussions or observed their absence. If that’s you, please message me what you’ve seen.
A previous generation of central banking leaders figured out how to not have any banking crises, at all, for thirty straight years. What those leaders knew seems to have been forgotten or abandoned.
This amnesia is hard to explain
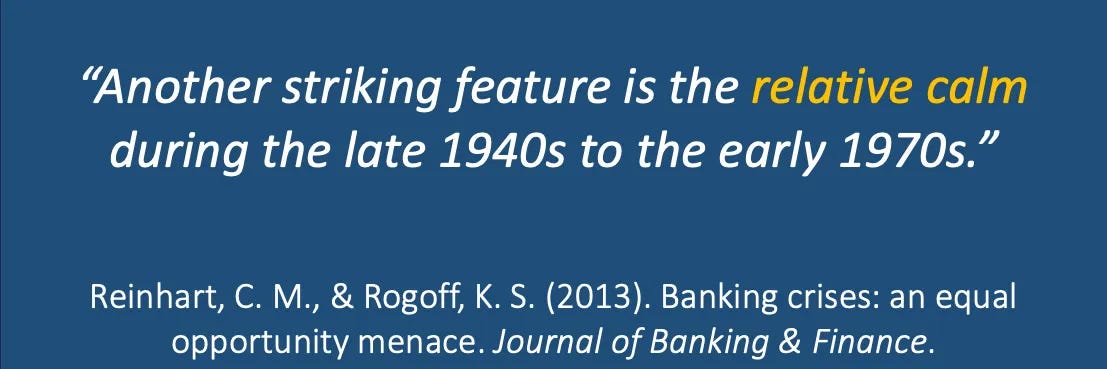
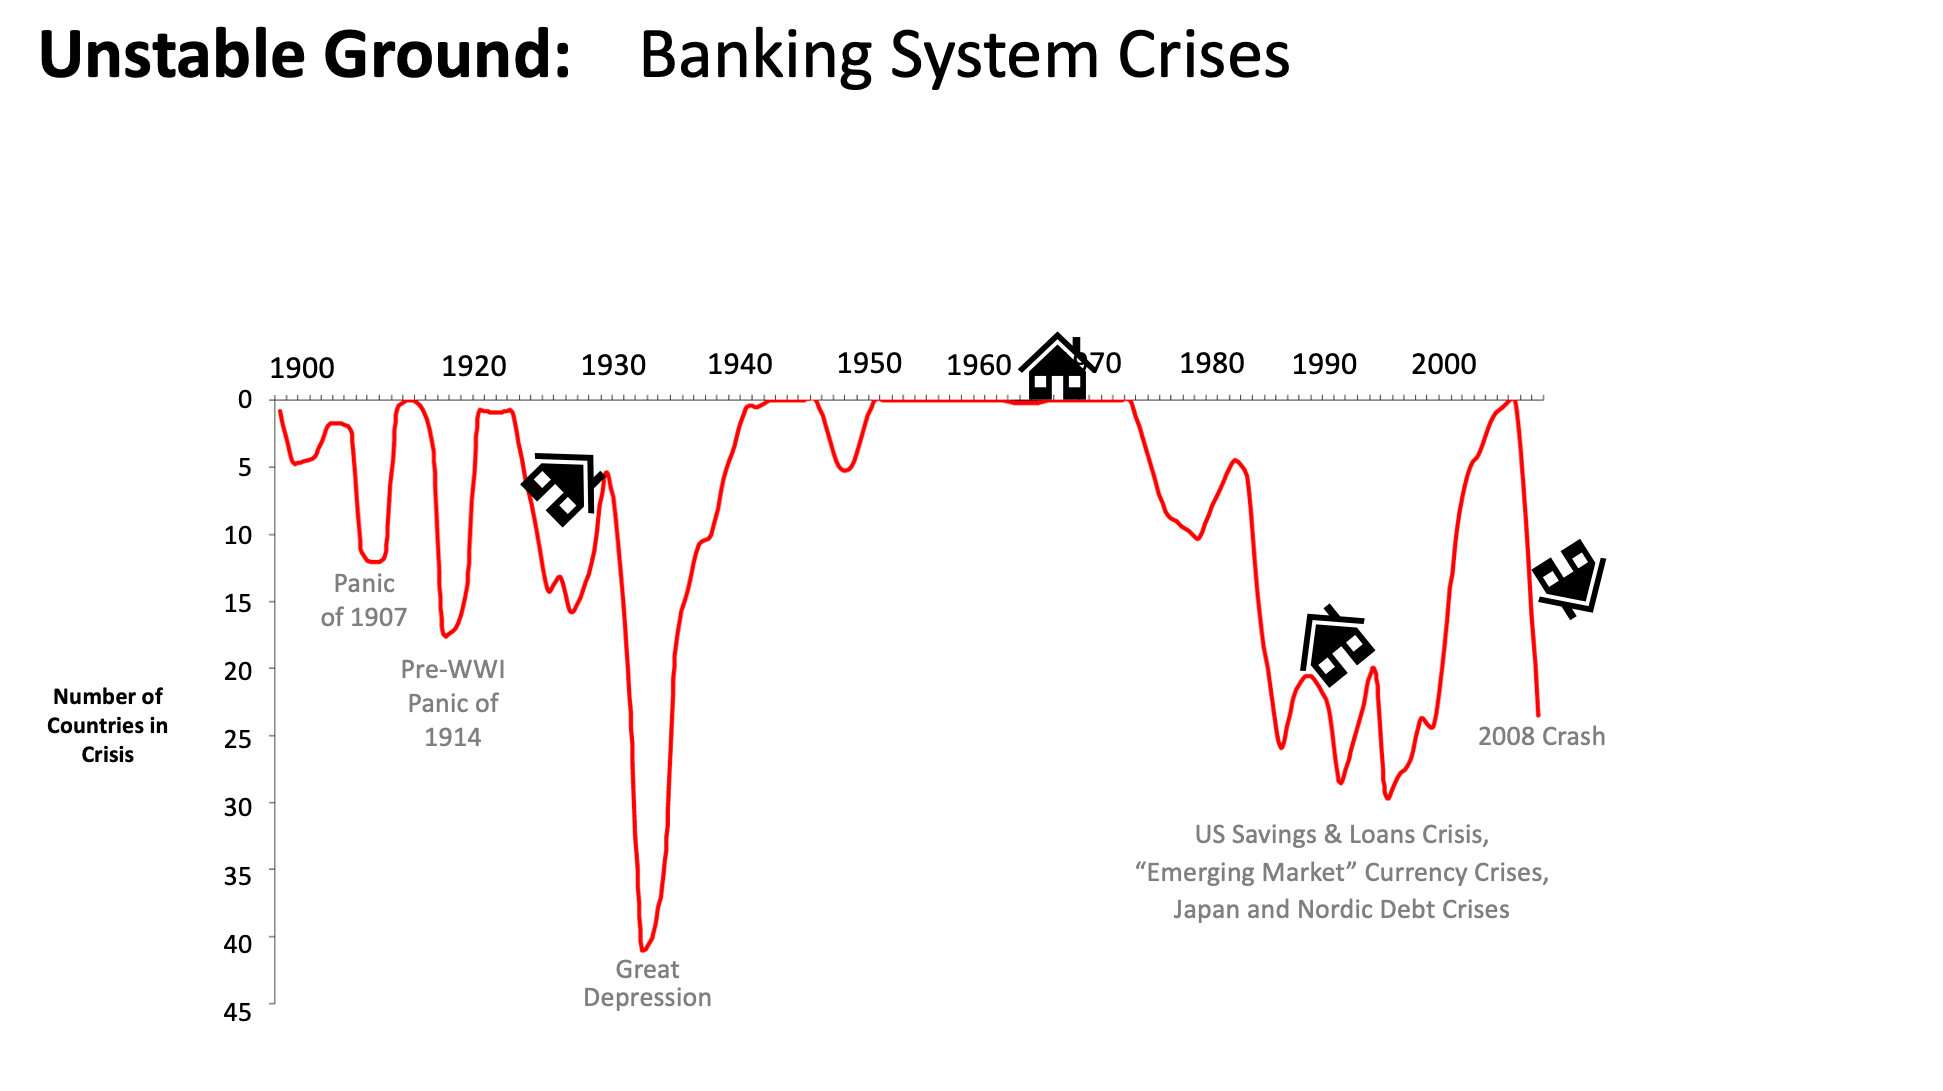
By 2009 and 2012, there were multiple highly-cited datasets shining a bright light on the 1940-1970 era as being a high-water mark in the history of banking stability, and therefore economic stability. As Schularick pointed out to Matthieu, his dataset isn’t the first one to highlight this wondrously tranquil period in banking history. Even before the 2008 financial crisis, a team of researchers at Harvard Business School had compiled a similar dataset that covers 66 countries, which revealed the same pattern, shown here in one of their 2013 papers:

The leaders of that Harvard study, Carmen Reinhart and Kenneth Rogoff, even wrote an influential book in 2009 which identified intergenerational amnesia as a culprit in banking crises: “short term memories make it all too easy for crises to recur.” (Inexplicably, Reinhard and Rogoff wrote in the paper in which they published the above chart that “graduation from banking crises has proven, so far, virtually impossible.” Their own data shows that achieving zero banking crises is completely possible and can even be sustained for decades at a time, globally.)
Unfortunately, Reinhart and Rogoff made some calculation mistakes in the analysis of their dataset and came to the incorrect conclusion that government austerity is a good solution to banking and financial crises. The fact that many politicians around the globe cited their analysis when passing austerity cuts post-2008 is a devastating lesson in the dangers of drawing causal conclusions from statistical correlations.
Nevertheless, their analytical errors don’t change the fact that the middle of the last century saw a dramatically more stable banking era than what came before and what we’ve experienced since.
An open question for me is “Why did only one generation get to enjoy the hard-earned discovery that banking crises are completely avoidable before the wisdom was lost?”
Why does a leading central bank economist not know all this?
Why are Matthieu and his colleagues in the leadership ranks of European central banks not anxiously comparing their own performance to that high water mark era?
I’d love for someone to study that question. Tracing the loss of the wisdom that guided economic leaders during the 1940s, 50s, and 60s would be a good way to learn how to stop such intergenerational amnesia in the future. But for now…
The important thing to observe is that, today, some of the economists leading our monetary systems are not aware that banking crises are completely avoidable.
In some sense, this shouldn’t come as a surprise considering how much we hear our central bankers talk about “promoting stability” instead of “permanently eliminating instability”. They simply don’t have an abolition mindset – even though history shows that abolishing banking crises is completely within our ability. Not just in theory, but in practice.
Banking Crises vs Wellbeing
When I give presentations, I like to flip Reinhart and Rogoff’s chart of banking crises upside down. It converts the peaks of the chart into deep crevasses. To me, this better reflects the subjective experience of banking crises. They are economic earthquakes that crack open the ground and swallow-up the hopes, dreams, and investments of generations. I’ll never forget being on a large group call at the beginning of the pandemic, when the fear of another financial crash was strong. A woman broke into the expert discussion to say that she simply could not handle living through something like the 2008 crisis again. The trauma of having lost her home and the business she’d built over many years overflowed in her tears. Her eyes reflected an intertwining of terror and grief that I’d never seen before.
Solid ground for wellbeing
Flipping Reinhart and Rogoff’s chart also gives greater meaning to the flat line of the 1940-1970 era. Again, it reflects the subjective experience of that time: stable financial ground on which to build a healthy society. (Rather, stable ground on which to try to build a healthy society. While many social indicators, such as wages, savings, and reduced inequality, improved mid-century, the era was marred by continued oppression and economic discrimination with respect to race, gender, colonialism, etc.)
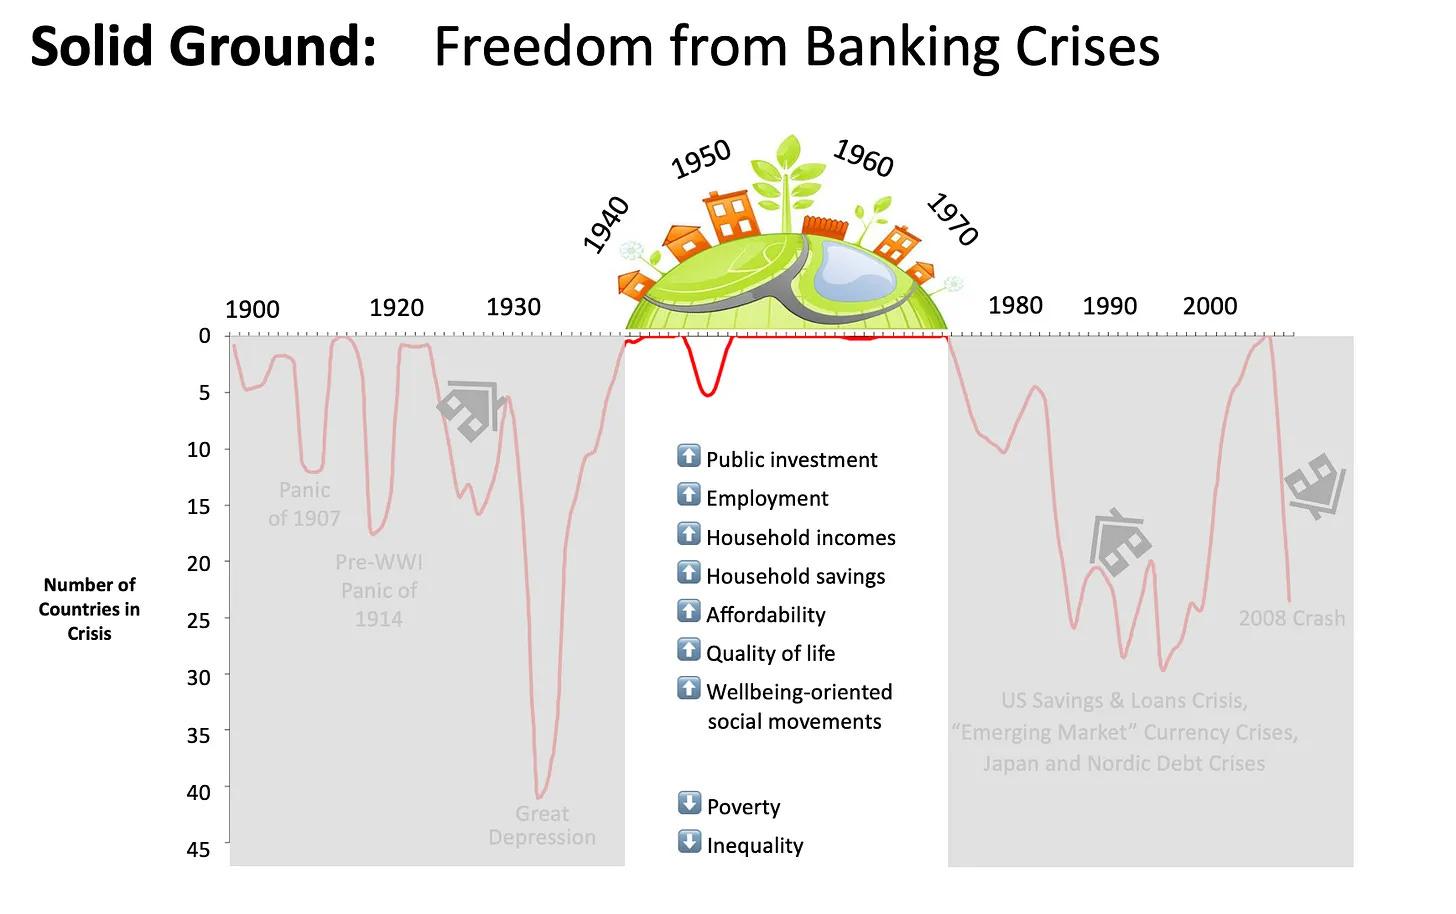
And countries did build healthier societies during that era of stability. In many countries around the world, public investment, employment, household incomes, household savings, affordability, and quality of life were improving. Poverty and inequality were falling. And as governments’ fiscal capacity grew, social movements won better social safety nets and more equitable distribution of public investment.
Not all of these things were due to banking stability, of course, but they are all gains that accumulated because they weren’t undone by banking crises. To say it another way, banking crises have devastating effects on all of those same aspects of economic wellbeing. Look at the 2008 crisis when many families lost their entire home equity and savings, unemployment soared and wages stagnated, poverty and inequality increased, and public debt burdens climbed dramatically.
There are direct, and even causal, connections between banking stability (and the absence of banking crises) and those metrics of prosperity and wellbeing. I don’t have time to explore them here, but I just wanted to preview how much better the world can be when banking crises are abolished, as the empirical data shows is possible. A further exposition of those things will have to come in another article.
Extra destructive
The 2008 crisis wasn’t an anomaly. Research looking across many decades and dozens of countries show that banking crises frequently lead to “financial recessions” which are, on average, 3 times deeper and longer than non-financial recessions in terms of productivity losses, unemployment, and business closures. They are also associated with large upswings in inequality. In fact, financial recessions have a permanently scarring effect on economies that is only rivaled by energy price shocks.

Banking crises have such a devastating effect, in part, because they result in an 86% increase in government indebtedness within 3 years, on average. This is largely due to the fact that citizens demand their governments provide some level of a social safety net, especially in times when huge numbers of people are thrown out of work due to the faults of financiers. In many countries, this comes in the form of “automatic stabilizers” that kick in whenever a crisis hits, such as unemployment insurance and anti-poverty assistance. Governments have to run deficits in order to provide these safety nets. The resulting spike in public indebtedness eventually results in creditors pressuring the governments to reduce cut public services and public investment in order to pay back its debts. (As noted, Reinhart and Rogoff recommend such cuts as the remedy to the public debt burden caused by banking crises, instead of recommending that banking crises be completely prevented in the first place by employing the practices of the mid-1900s.)
Having lived through the 2008 crisis and the stagnant aftermath and seen this destruction first hand, I feel envious of the financial stability of that era. Even a little angry that it didn’t last into my lifetime. Why did only one generation get to enjoy the hard-earned discovery that banking crises are completely avoidable before the wisdom was lost???
Fertile Ground for Right-wing Extremism
Banking crises have surprising effects on democracy, unique among other causes of economic crises. Political scientists took Schularick’s dataset of 140 years worth of banking crises in 17 countries measured the effect of banking crises on democracy (800 election cycles). They found that financial recessions triggered by banking crises spark right-wing swings in politics within 5 years.
On average, far-right parties increase their vote share by 30% after a financial crisis. Importantly, we do not observe similar political dynamics in normal recessions or after severe macroeconomic shocks that are not financial in nature… A key difference between financial recessions and [other] severe macro disasters is that support for the government increases during non-financial macro-disasters, but falls significantly in financial crisis recessions. Put differently, in non-financial disasters people rally behind the government. In financial crises, support for the government drops sharply… A first potential explanation could be that non-financial crises are perceived as “excusable” events, triggered by large exogenous shocks such as oil prices, natural catastrophes, or wars… A second explanation is that financial crises typically involve bailouts for the financial sector and these are highly unpopular… A third explanation is that financial crises have social repercussions that are not observable after non-financial recessions.
Many people in the US would recognize all three of those factors as playing a role in the rapid rise of the Tea Party in 2010 and the MAGA movement that emerged from it. There are similar swings happening in Europe, such as Brexit. Given the amount of destruction banking crises cause, the anger of the populous is understandable.
The leaders of the postwar era didn’t need sophisticated studies to tell them about the relationship between banking crises and rightwing extremism. They were clear that the Great Depression, rise of Fascism, and calamity of WWII all had roots in bank-fueled credit bubbles, systemic banking crashes, and bank-levered “hot money” driving speculative foreign exchange volatility. They understood that the “beggar thy neighbor” trade wars were futile attempts to combat the economic destruction and capital outflows. That understanding is where the political will to regulate speculative risk-taking and systemic risk out of banking came from.
So what exactly did so many countries do to simultaneously eliminate banking crises?
Countries took diverse pathways to achieve the same goal of ending banking crises and bank money creation for unproductive and speculative purposes. (The fact that today’s leaders can’t find even one pathway to completely eliminate banking crises is damning in consideration of the historical evidence that there are multiple ways that work.) At a high level, the pathways that countries took included two prongs: domestic measures and international cooperation.
The subordination of the banking sector to government-led economic development policies.
Examples of ways this was done include:
regulating private banks like public utilities with strong controls, supervision, and market segmentation
establishing mission-oriented public banks, development banks, cooperative banks, and credit unions
implementing credit policies that obliged banks to lend for productive economic activities and blocked or penalized them for lending to unproductive activities
setting interest rate floors and ceilings that kept credit markets stable and banks from competing for deposits with ruinous interest rate wars
holding interest rates at low levels to enable governments and corporations to fund themselves easily and on long terms
taking ownership of or guaranteeing (after vetting) large portions of the assets bank lending produced
creating money for fiscal spending via various forms of “monetary financing”
What these practices had in common was that they channeled bank money creation into national development priorities, such as industrialization or agricultural modernization, and away from unproductive, counterproductive, and speculative purposes. Such economic planning by governments sounds extraordinary, today, but it was the norm mid last century. As some have pointed out, the fact that governments have largely given up that role today doesn’t mean we don’t have centralized economic planning. The planning just takes place within large and highly coordinated financial institutions, especially big banks.
A few particularly good resources on the practices governments employed during the “oasis of calm” are Eric Monnet’s Controlling Credit (Chapter 7), Credit Policy and the ‘Debt Shift’ by Bezemer et al., and Rebuilding Banking Law by Menand and Ricks.
Forging international monetary system agreements.
Countries cooperated on stabilizing exchange rates and stopping money from flowing across borders in rapid and destabilizing ways (e.g., speculative “hot money”). Banks had been key participants in the exchange rate and capital account volatility of the interwar period. The primary mechanism for reigning the volatility in was the 1944 “Bretton Woods agreement” which put governments in charge of setting exchange rates and controlling capital flows, no longer banks. See Chapter 1 of Deweaponizing Interdependence: Bringing the Idea of International Clearing Union into the Twenty First Century for an excellent summary of that agreement, its development, and its relevance for today.
In general, all of these measures had a common goal, which was to ensure that the legal privilege to create money was being directed into the service of public priorities and in ways that were stabilizing rather than destabilizing.
[If I had to recommend one resource on the regulation of the banking sector in this era, it would be Eric Monnet’s Controlling Credit. Chapter 7 provides a multi-country survey in Chapter 7 that shows there were multiple pathways to stabilization.]
How to avoid dangers in deregulation
It’s widely accepted that today’s banking regulations are overly complicated, especially for small banks without the capacity to handle the compliance burden. For example, the post-2008 crash US Dodd-Frank banking reform law totaled 2,300 pages and called for agencies to develop 400 new regulations.
Without question, a number of banking regulations can be safely removed or simplified, but the deregulation trend in recent decades shows that many of the rules cut were not safe to remove. Reinhart and Rogoff find a strong and predictive correlation between banking deregulation and banking crises in the post-oasis era. In 70% of the banking crises studied, “the financial sector had been liberalized within the preceding 5 years, usually less.”
To get back to safety, it helps to know that we previously had a sustained era of zero banking crises because it simplifies our task. We can:
Step 1: Retain what worked
Before we consider further deregulation, we should first look to see which stabilizing pieces of the oasis of calm recipe were lost in the oasis-ending deregulation era, and bring them back.
Step 2: Reconsider what is new
There are an enormous number of regulations that have been created that may not need to exist once the oasis of calm measures are put back in place. Consider, for example, that the oasis of calm preceded the development and (problematic) promulgation of the complex Basel I, II, and III global banking standards, which were designed to restore banking stability. (Basel I and II failed to stop the 2008 crisis.) Given that the oasis of calm era achieved near-perfect banking stability, some newer regulations probably aren’t necessary once the oasis of calm measures are put back in place. For example, the stability benefits of today’s complex risk-weighted capital adequacy regulations could be satisfied with a simple leverage ratio requirement, a rule commonly found in the oasis era. (The sufficiency of a simpler leverage ratio is tacitly acknowledged in Basel III, which added a simple leverage ratio as a “backstop” for the more complex risk-weighted capital adequacy regulations.)
The point here isn’t to say that everything during the oasis period was perfect or that nothing important has been developed since then. Many good regulations have been innovated since then, such as anti-money laundering, privacy standards, know your customer laws, etc. My argument is simply that we should be making the oasis of calm regulatory regime – the indisputable high water mark of global banking stability – the jumping off point for banking stability regulation today, instead of examining each new crisis for tweaks to make to the regime that just failed.
Let’s change the world
If this post does anything, I hope it will give you the confidence to be a banking crisis abolitionist for as long as you breath. No one can tell you the the complete elimination of banking crises isn’t possible. It has already been accomplished, in the real world, in dozens of countries, for decades at a time!
The first step is to choose, ourselves, to be the rememberers, the ones that remind our leaders of what has been forgotten. Together, we can end the amnesia and break the spell cast by the message that the risk of banking crises is something we can only manage, not eliminate. All we have to do is, every opportunity we get, speak up to reject the spell and share the memory of what works. Every time we do that, we change what is possible. We cannot know which leaders will grab on to the idea, but some will and the world will be changed by it.
Please share this article. Write your own. Speak up. Ask hard questions. Demand that leaders match the high water mark. The generations that lived through the 2008 crisis, and all those that follow, deserve the opportunity to build our lives in an oasis of calm.