

This is part of a series of presentations that share insights from my four years of research into the design of national currencies. The series curates and encapsulates learnings that I think are particularly interesting, important, and useful for understanding how our world works, today.
This second video gives a brief overview of the way banks newly create 100% of the money they lend, every time they lend. This runs contrary to the typical belief that banks lend out depositors’ savings. As discussed in a prior video on the history of money creation, this way of creating money through banking is the primary source of money in the world today.
This video covers the accounting and limits placed on bank money creation. The next video will cover the law and politics governing this system of money creation. As always, the presentation builds on a large body of scholarship, which can be found in the references listed below.
Jump to the…
Video Recording
Annotated Bibliography
These are organized in the order of their approachability and the sequence of information in the video’s narrative.
McLeay, Michael, Amar Radia, and Ryland Thomas. 2014. “Money Creation in the Modern Economy.” Bank of England Quarterly Bulletin 54 (1): 14–27. https://www.bankofengland.co.uk/quarterly-bulletin/2014/q1/money-creation-in-the-modern-economy.
The Bank of England’s seminal 2014 bulletin describes in clear language that banks do not lend out depositors’s savings because they newly create 100% of the money they lend via accounting.
European Central Bank. 2015. “What Is Money?” Updated June 19, 2024. Accessed 2024. https://www.ecb.europa.eu/ecb/educational/explainers/tell-me-more/html/what_is_money.en.html.
This concise introduction provided by the European Central Bank states that “If a commercial bank grants you a loan to buy a car, they create money in this way… and when you repay the loan, the money created disappears.”
Ryan-Collins, Josh, Tony Greenham, Richard Werner, and Andrew Jackson. 2012. Where Does Money Come From? London: New Economics Foundation. https://neweconomics.org/2012/12/where-does-money-come-from/.
This book provides an excellent and accessible, yet scholarly, introduction to money creation in today’s banking-based national money systems. It is an especially useful resource because it presents the exact accounting entries used in banking to create money. It also provides the accounting entries for many other transactions, such as when banks buy cash (bills and coins) from central banks in order to provide customers with a physical representation of their electronic deposits. While the book focuses on the United Kingdom, it is relevant for readers in all countries because the UK system is the original bank money creation system upon which all others are built today.
Federal Reserve Money Types: Government (M1) vs Bank Money (M2)
Board of Governors of the Federal Reserve System (US). 2025. “M1 (M1SL).” Federal Reserve Bank of St. Louis (FRED). Accessed October 2025. https://fred.stlouisfed.org/series/M1SL.
Board of Governors of the Federal Reserve System (US). 2025. “M2 (M2SL).” Federal Reserve Bank of St. Louis (FRED). Accessed October 2025. https://fred.stlouisfed.org/series/M2SL.
United States Mint. 2024. “How Coins Are Made: Bringing Coins Into Circulation.” Inside the Mint. July 2, 2024. https://www.usmint.gov/news/inside-the-mint/how-coins-are-made-bringing-coins-into-circulation
This article on the website of the United States Mint explains that coins are minted by the Mint in response to orders for coins placed by depository institutions (banks). Coins do not enter circulation as spending by the government.
Federal Reserve Bank of San Francisco. 2025. “Infographic on the Cash Lifecycle.” Last modified 2025. https://www.frbsf.org/cash-lifecycle-infographic/
This article and infographic shows how coins from the Mint and bills from the US Bureau of Engraving and Printing are put into circulation by the Federal Reserve in response to orders from banks, not as spending by the government.
Glocalities. 2014. “What Global Population Thinks About Commercial Banks.” Press release. Accessed October 2025. https://glocalities.com/news/press-release-global-population-does-not-want-commercial-banks-to-stay-responsible-for-creating-most-of-the-money.
This survey of 24,000 people conducted in 12 languages across 24 countries revealed that a majority of people believe the majority of money is created by governments or central banks. Only 14% preferred that private commercial banks be the primarily creators of the money supply.
Positive Money. 2014. “POLL RESULTS: Only 1 out of 10 MPs Understand That Banks Create Money.” Positive Money (blog). August 19, 2014. https://positivemoney.org/2014/08/7-10-mps-dont-know-creates-money-uk/.
This poll found that seven out of ten members of the UK parliament beleived that *only* the government had the legal power to create money, including digital bank money. Only 10% knew banks creates over 95% of the money in ciruclation.
Werner, Richard A. 2016. “A Lost Century in Economics: Three Theories of Banking and the Conclusive Evidence.” International Review of Financial Analysis 46: 361–79. https://doi.org/10.1016/j.irfa.2015.08.014.
This paper describes an empirical test of bank accounting software conducted in 2014. The investigator found that the software confirms that 100% of the deposits provided to borrowers are newly created.
Positive Money. 2013. “Positive Money Banking 101.” YouTube playlist. Accessed October 2025. https://www.youtube.com/playlist?list=PLxl7ssO5_r5fG9OEFsMYXUDr6hYXwRMx8.
This brief and animated video series provides an excellent introduction to bank money creation.
Perry Mehrling. 2020–. “Economics of Money and Banking (Mehrling) — Full Course.” Institute for New Economic Thinking. YouTube playlist. Accessed October 2025. https://www.youtube.com/playlist?list=PLbjqQEPFY1J8ShzMPiaULMDCIuFmaBs0Y.
This course taught through Columbia University by highly regarded banking historian and economist Perry Mehrling, provides instruction on bank and central bank accounting.
Money Justice Collaborative. New Banking Consensus Database. Accessed October 2025. https://moneyjustice.org/consensus.
This database contains quotes and citations for statements published by experts confirming that banks create 100% of the money they lend. The more than 150 quotes come from central banks, banks, banking scholars, economists, and multilateral organizations.
Hockett, Robert C., and Saule T. Omarova. 2017. “The Finance Franchise.” Cornell Law Review 102 (5): 1143–1218. https://dx.doi.org/10.2139/ssrn.2820176
This paper illuminates bank money creation through the lens of law, including some of the limits on bank money creation.
Ricks, Morgan. 2016. The Money Problem: Rethinking Financial Regulation. Chicago: University of Chicago Press. https://press.uchicago.edu/ucp/books/book/chicago/M/bo22438821.html.
This book illuminates bank money creation through the lens of law, including some of the limits on bank money creation.
Transcript & Slides
Today, we’re going to be talking about how banks create money.
In our last video, we talked about the way that today’s money system emerged from accounting. About 5,000 years ago, the first evidence of money is actually this accounting-based money that Egypt and Sumeria used for 3,000 years.
In the case of Egypt, before the invention of physical money like coins, that were really invented by states to support their marauding and pillaging armies, and continue to be used problematically by states for the next 2,000 years or so, as discussed in the last video.
And about 300 years ago, a major innovation happened where the accounting system and this physical form of money creation merged into the national money systems that pretty much every country on the planet uses today. So this isn’t exactly a linear story. There are lots of different ways that money had been created by many different human societies over the last 5,000 years. But this is a simple way of thinking about the threads that came together into forming what we use today.
And what’s important about the accounting-based money system we use today is that instead of it being states that are operating the books – the accounting books – it’s commercial banks, also credit unions and the savings banks. And that's a radical shift. And we're going to talk particularly in the next session about why that is such an important radical shift.
But just to give you a sense of what’s ahead in this section, first of all, we’re going to help you understand how banks create money. And by the end of this presentation, I promise you, you’re going to understand it better than most economists. And you don’t need to know anything from finance or anything like that to get it.
Then we’re going to talk about what limits bank money creation, because obviously banks fail. If they could just create an unlimited amount of money, that would never happen. So, there are limits.
I’m going to let you hear directly from central bankers, bankers, and banking scholars – talking about this themselves.
And then we’re going to talk about why governments let banks create money.
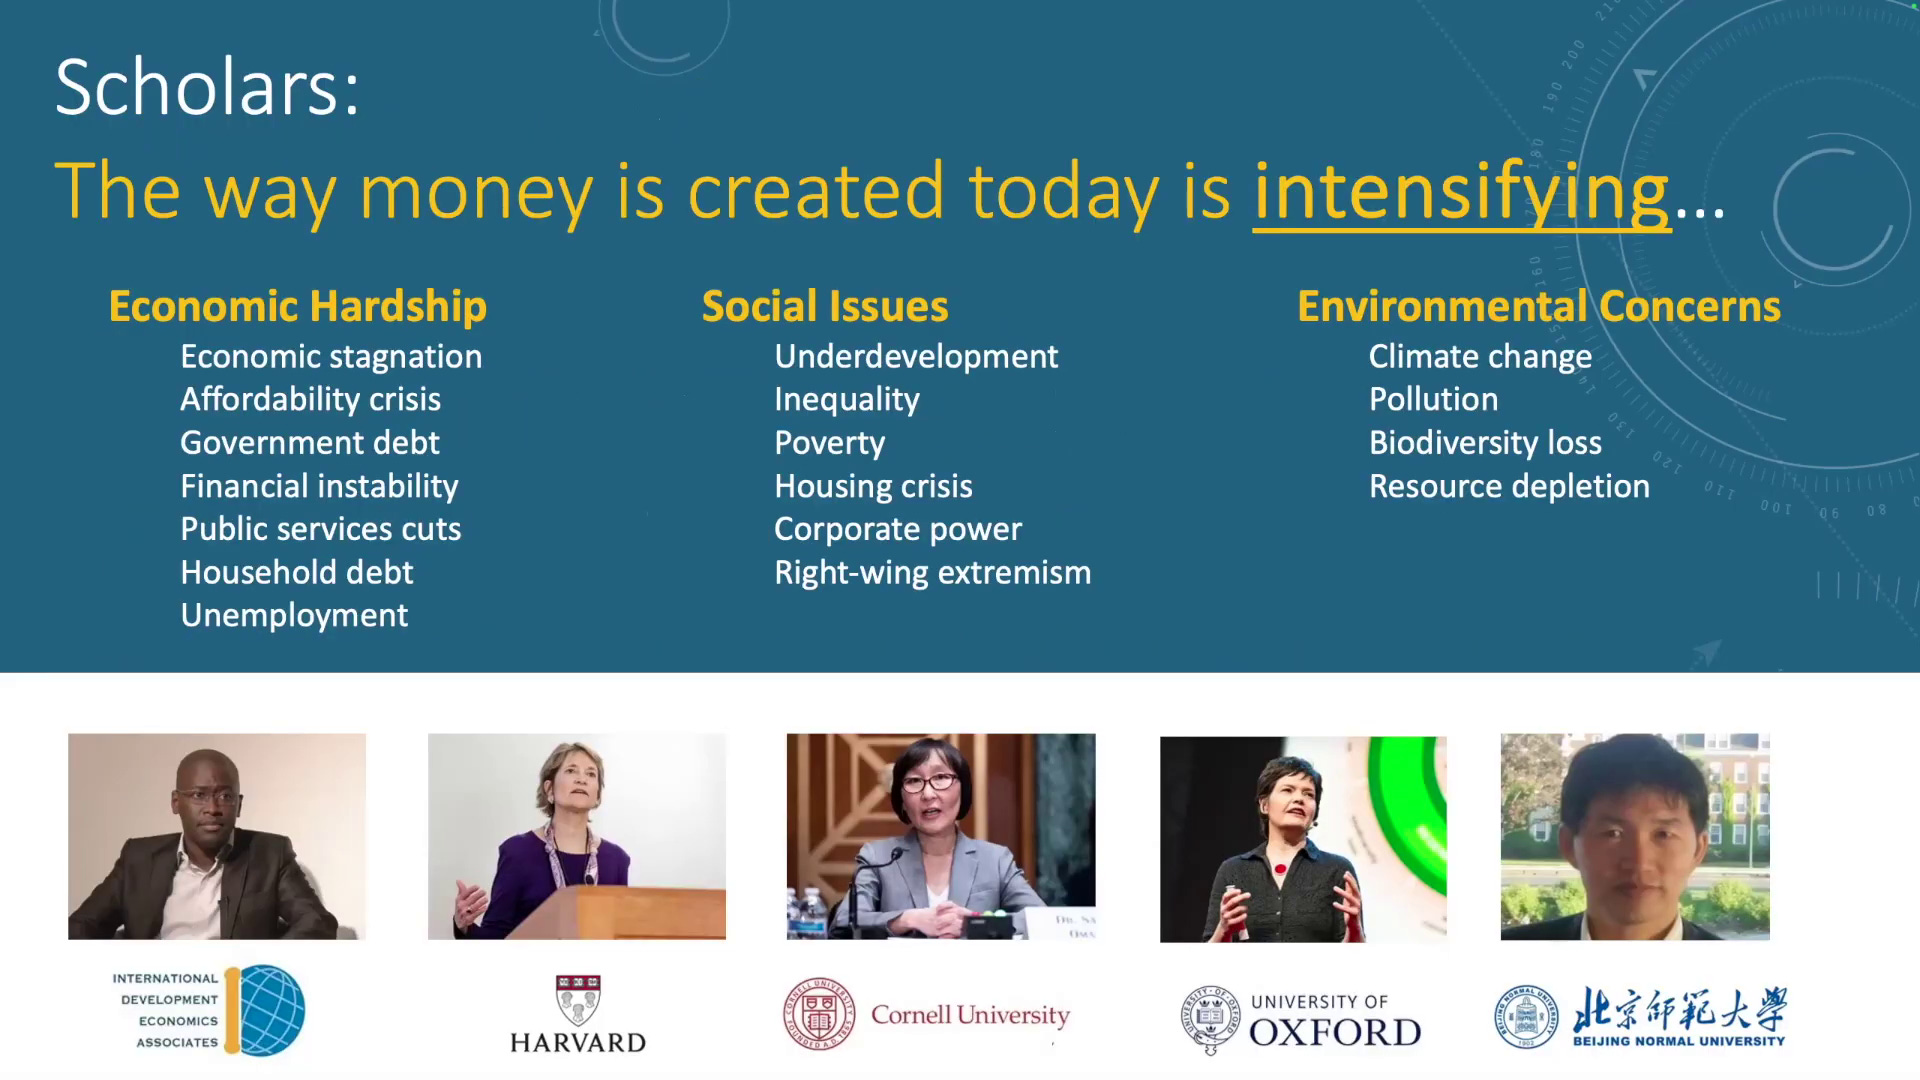
And just why are we talking about all this? Just to reconnect with why this is all important, the reason is that scholars and researchers are telling us today that the way money is created is intensifying many of the economic, social, and environmental issues of our time. And that may sound surprising that the way money is created could be influencing so many different issues.
But if you think about it, money is involved in so many of these issues, whether it’s inequality or affordable housing, or even what type of fuels we’re using in our energy infrastructure. And so, it makes sense actually, and we’ll talk more about this next time, why money creation could be touching on so many different things.
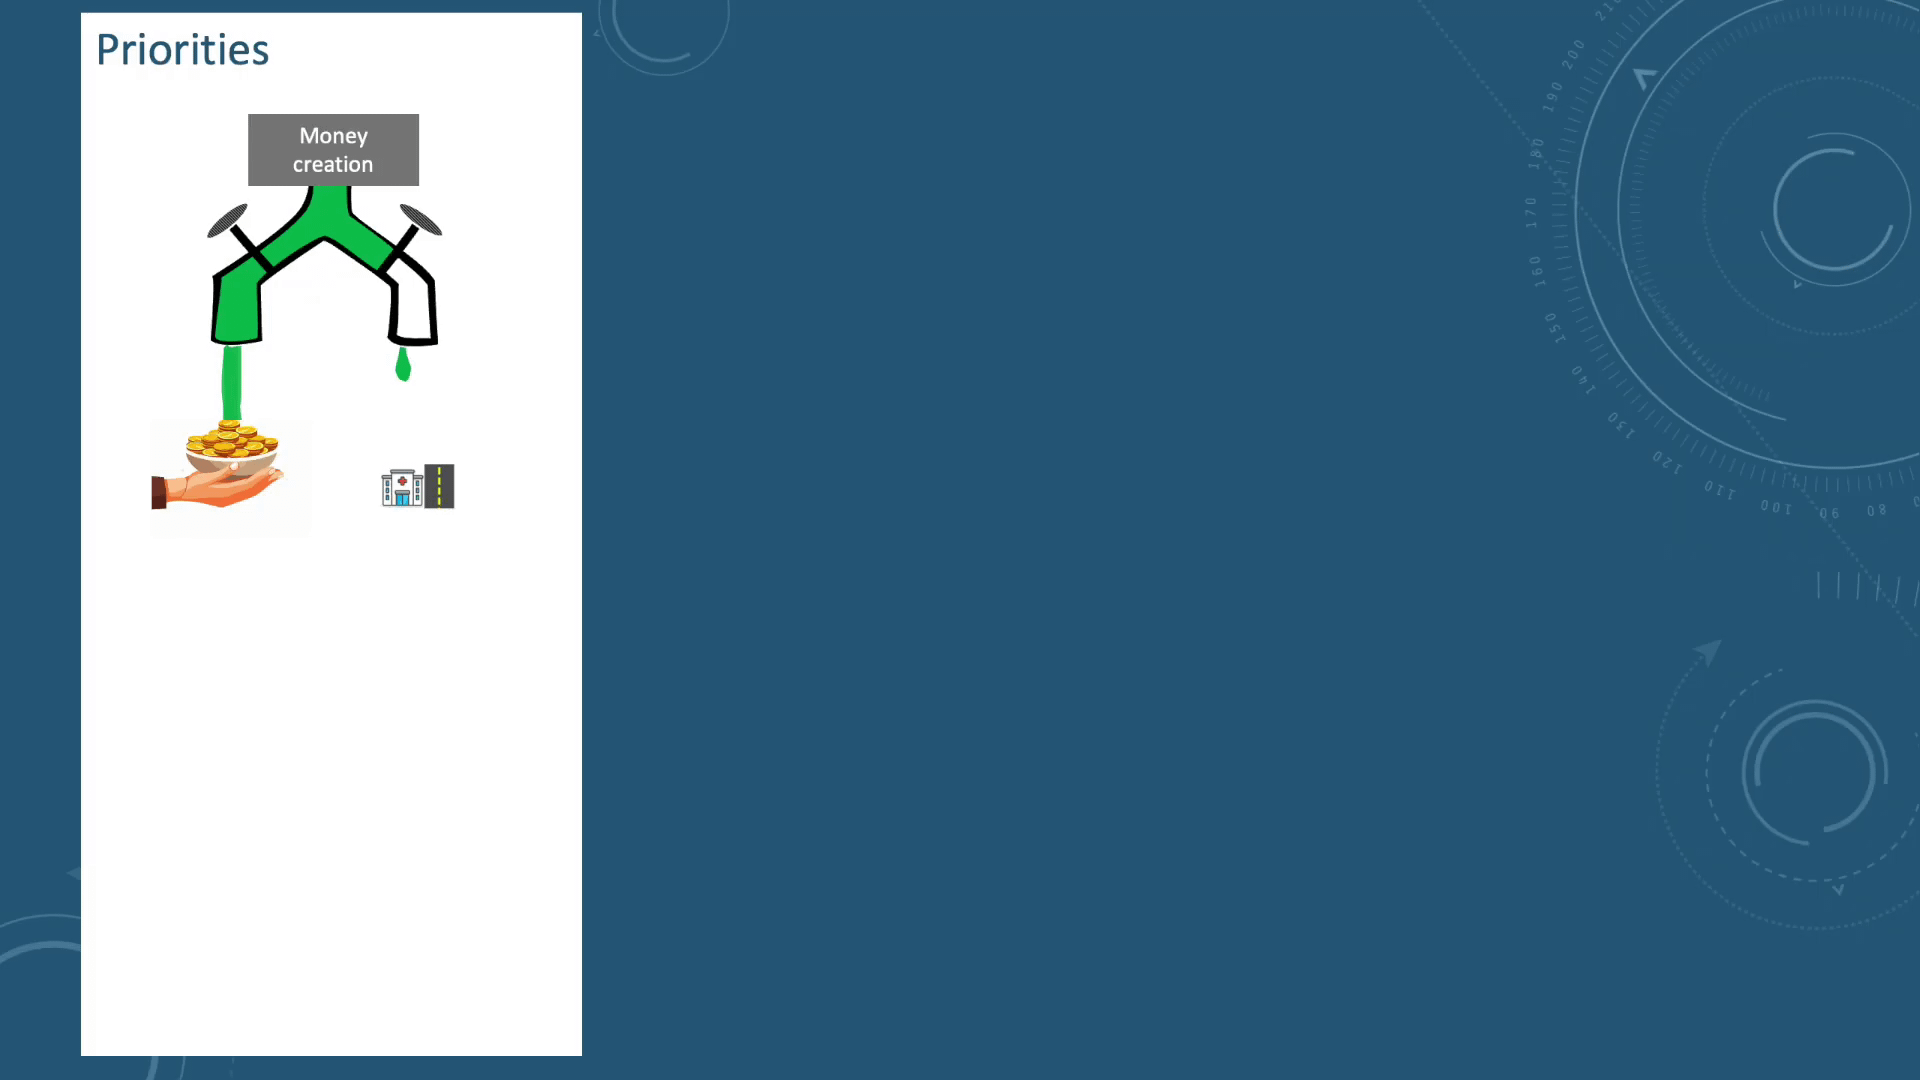
Now, obviously there’d be no reason in talking about this if there weren’t some alternatives. And what these researchers are telling us is that there are. So if you take, for example, what is being prioritized in terms of what’s being funded with new money creation, what they tell us is that our current system is prioritizing private wealth accumulation.
So for example, people who are already wealthy are most able to borrow money to buy up assets like real estate and businesses and so on, and become further wealthy. Meanwhile, investment into things that aren’t profitable like running a hospital or building roads for the public, public wealth is not prioritized.
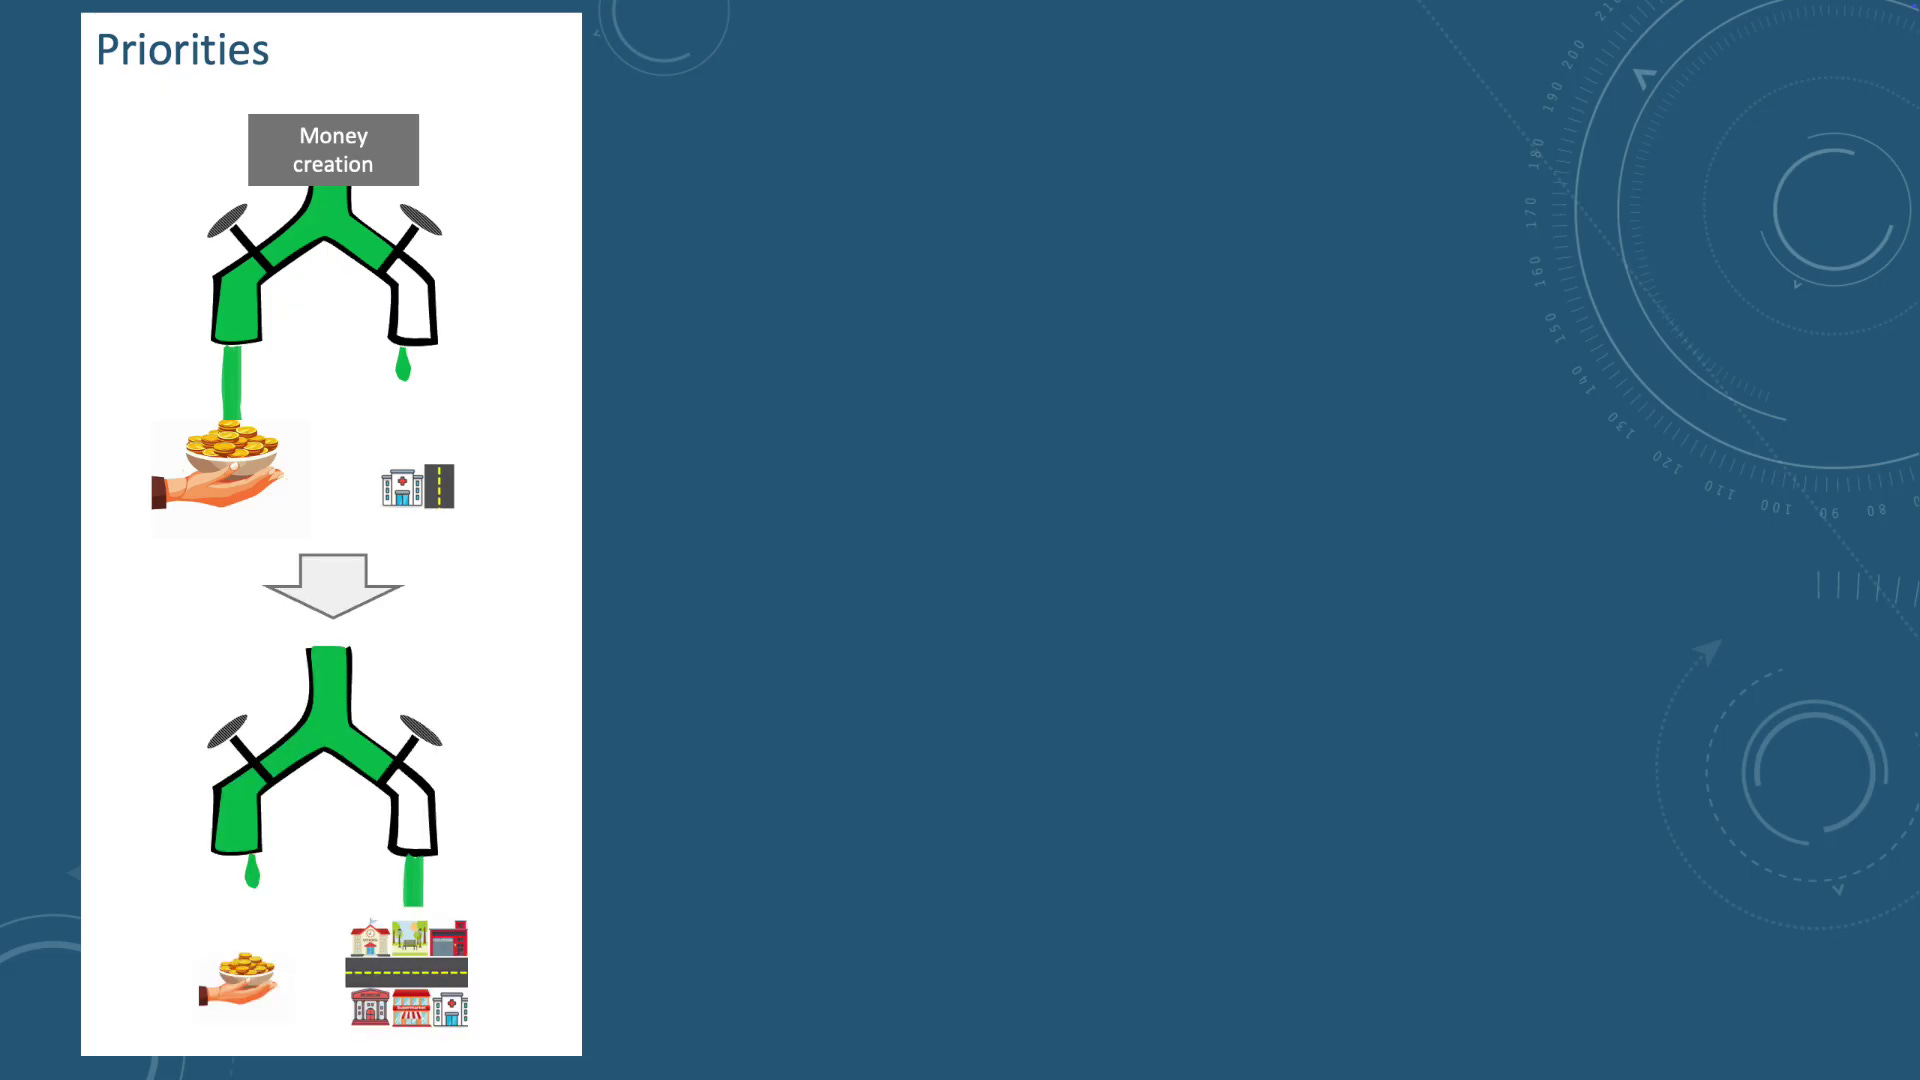
And what they point to is that there are systems that we’ve had in the past and that are, in fact, in use in the world today that do the exact opposite. They prioritize public wealth building with schools and hospitals, and so on.
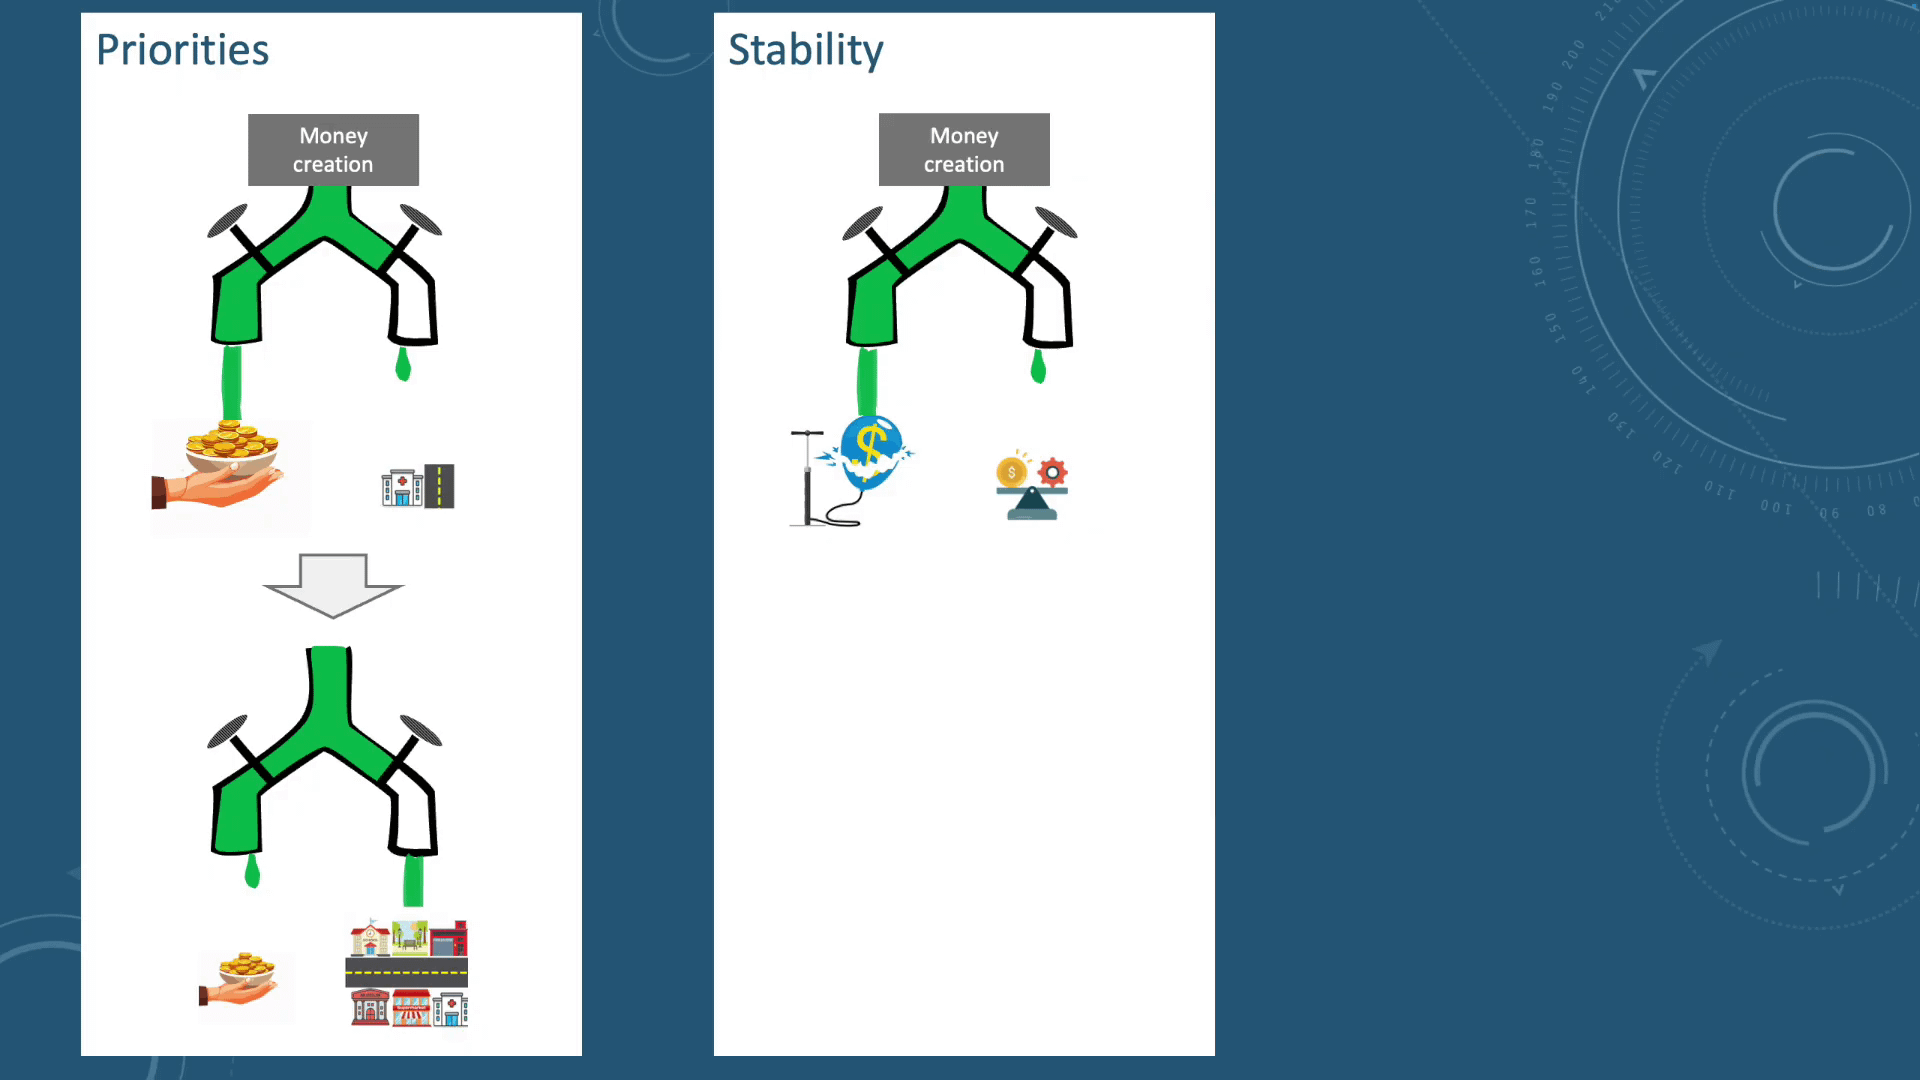
And what they're also pointing to is things like financial stability. Our current system, as they're telling us, rewards speculation in the stock market and in real estate and so on, and kind of penalizes investment in long-term productivity like farms and factories.
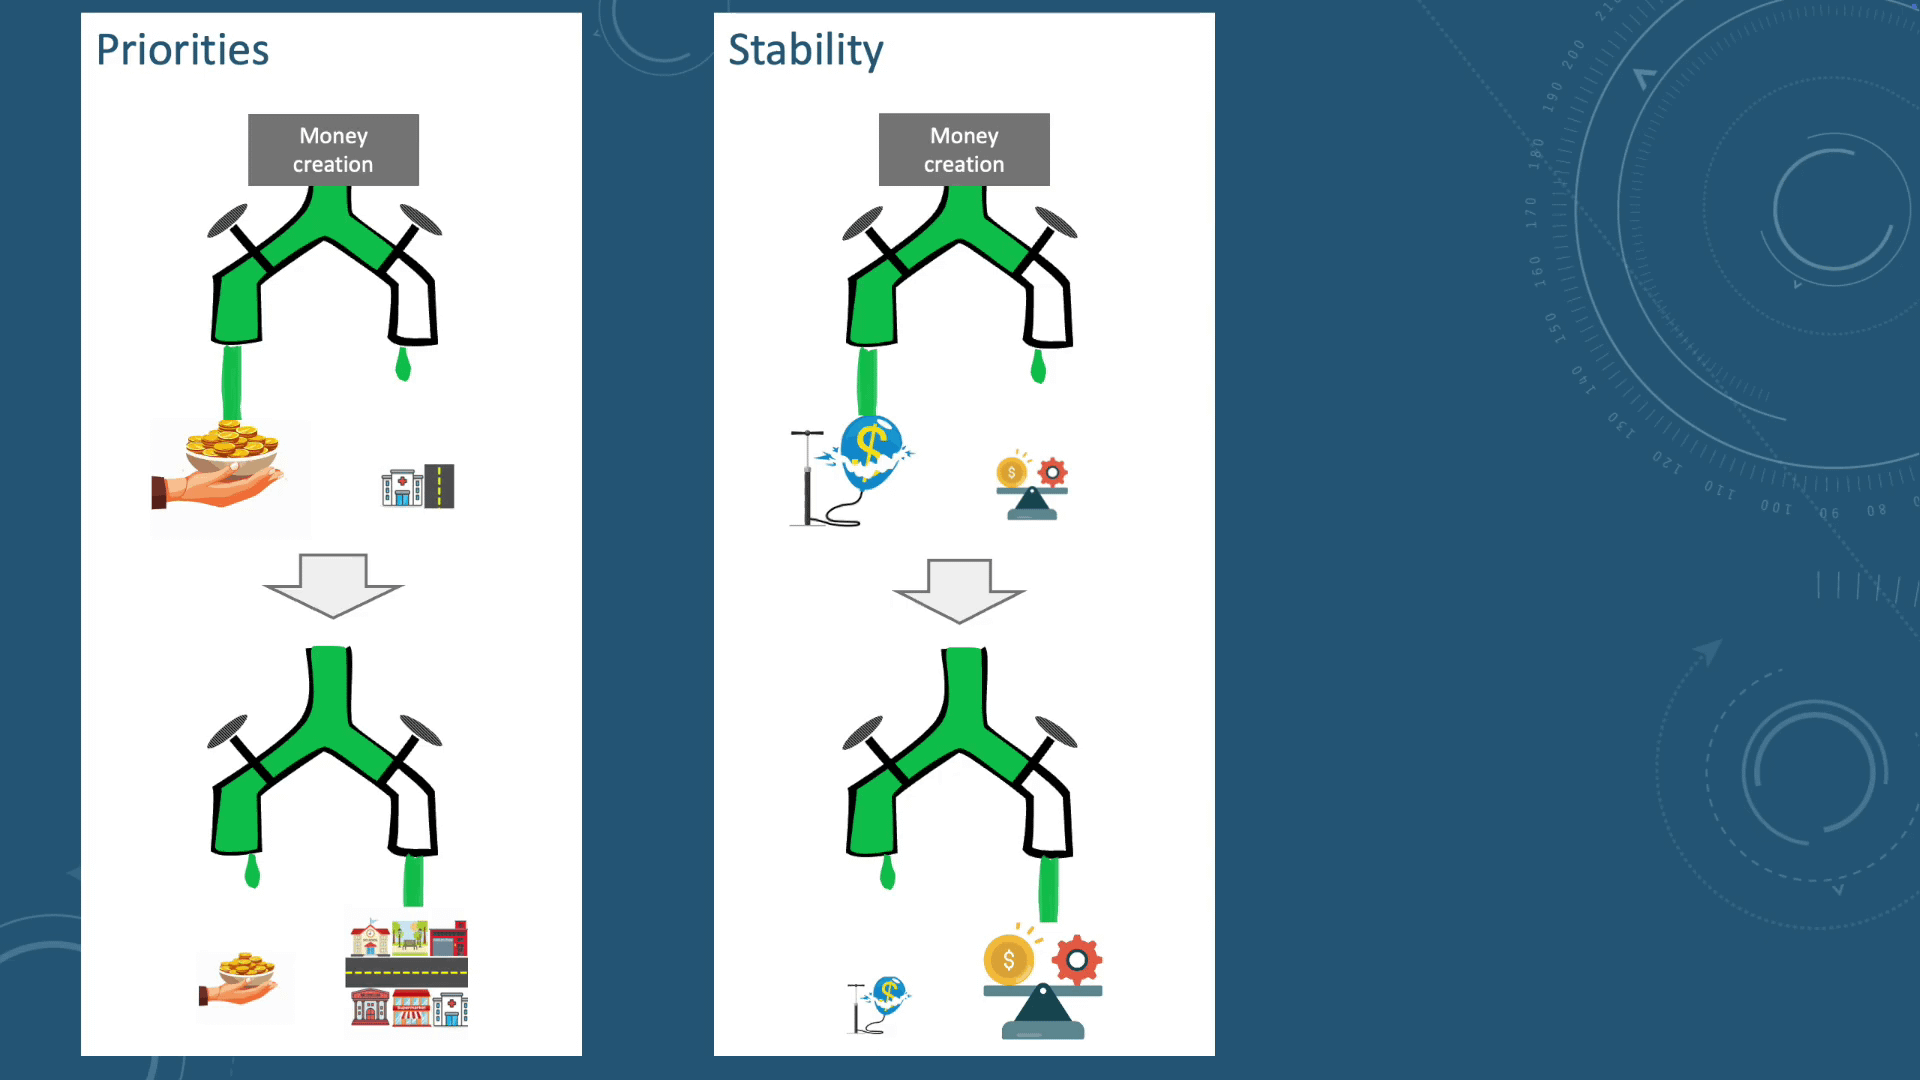
And so what they’re telling us is that, “Hey, we’ve had different systems before, and again, around the world today, that do the exact opposite – they reward investment in farms and factories and discourage speculative bubbles.”
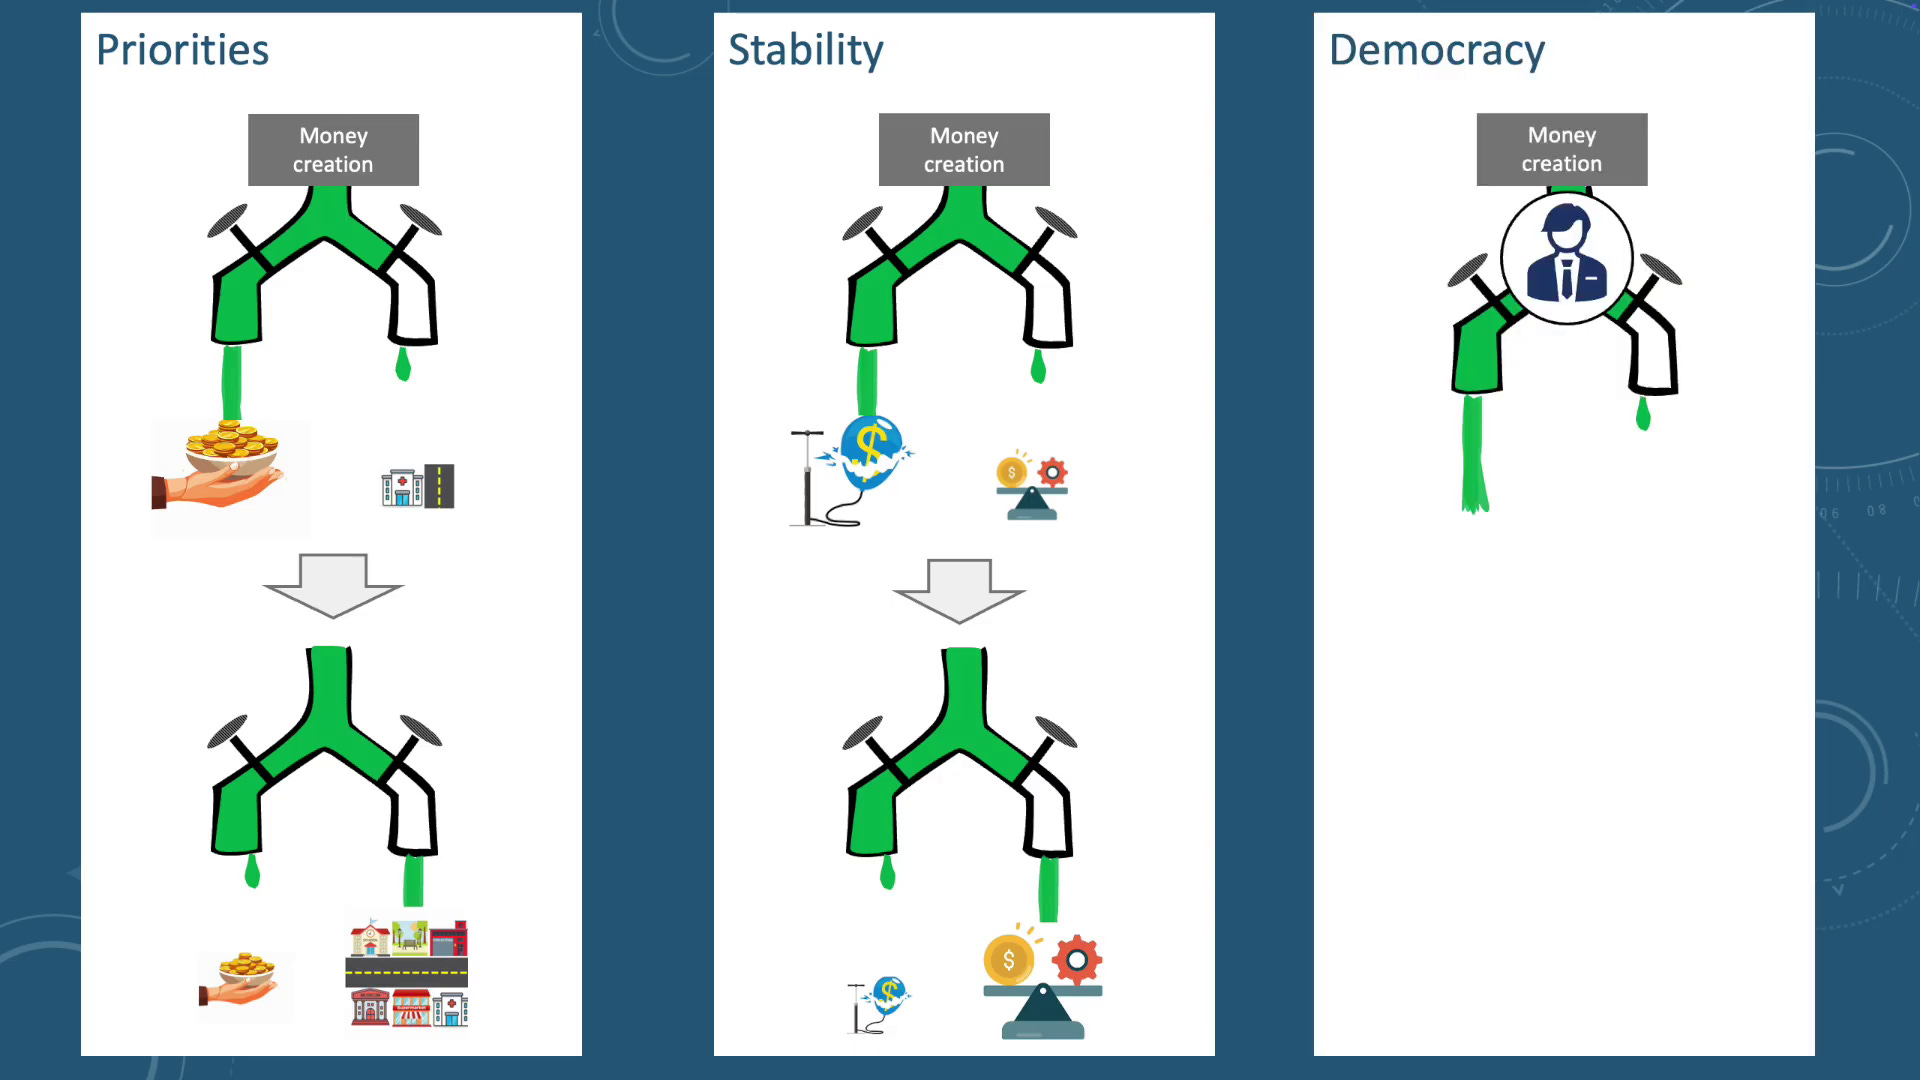
And when it comes to who’s making the decisions about what receives investment in our economy when new money is being created, our current system is not particularly democratic. The decisions have been outsourced to the loan officers and management of private banks.
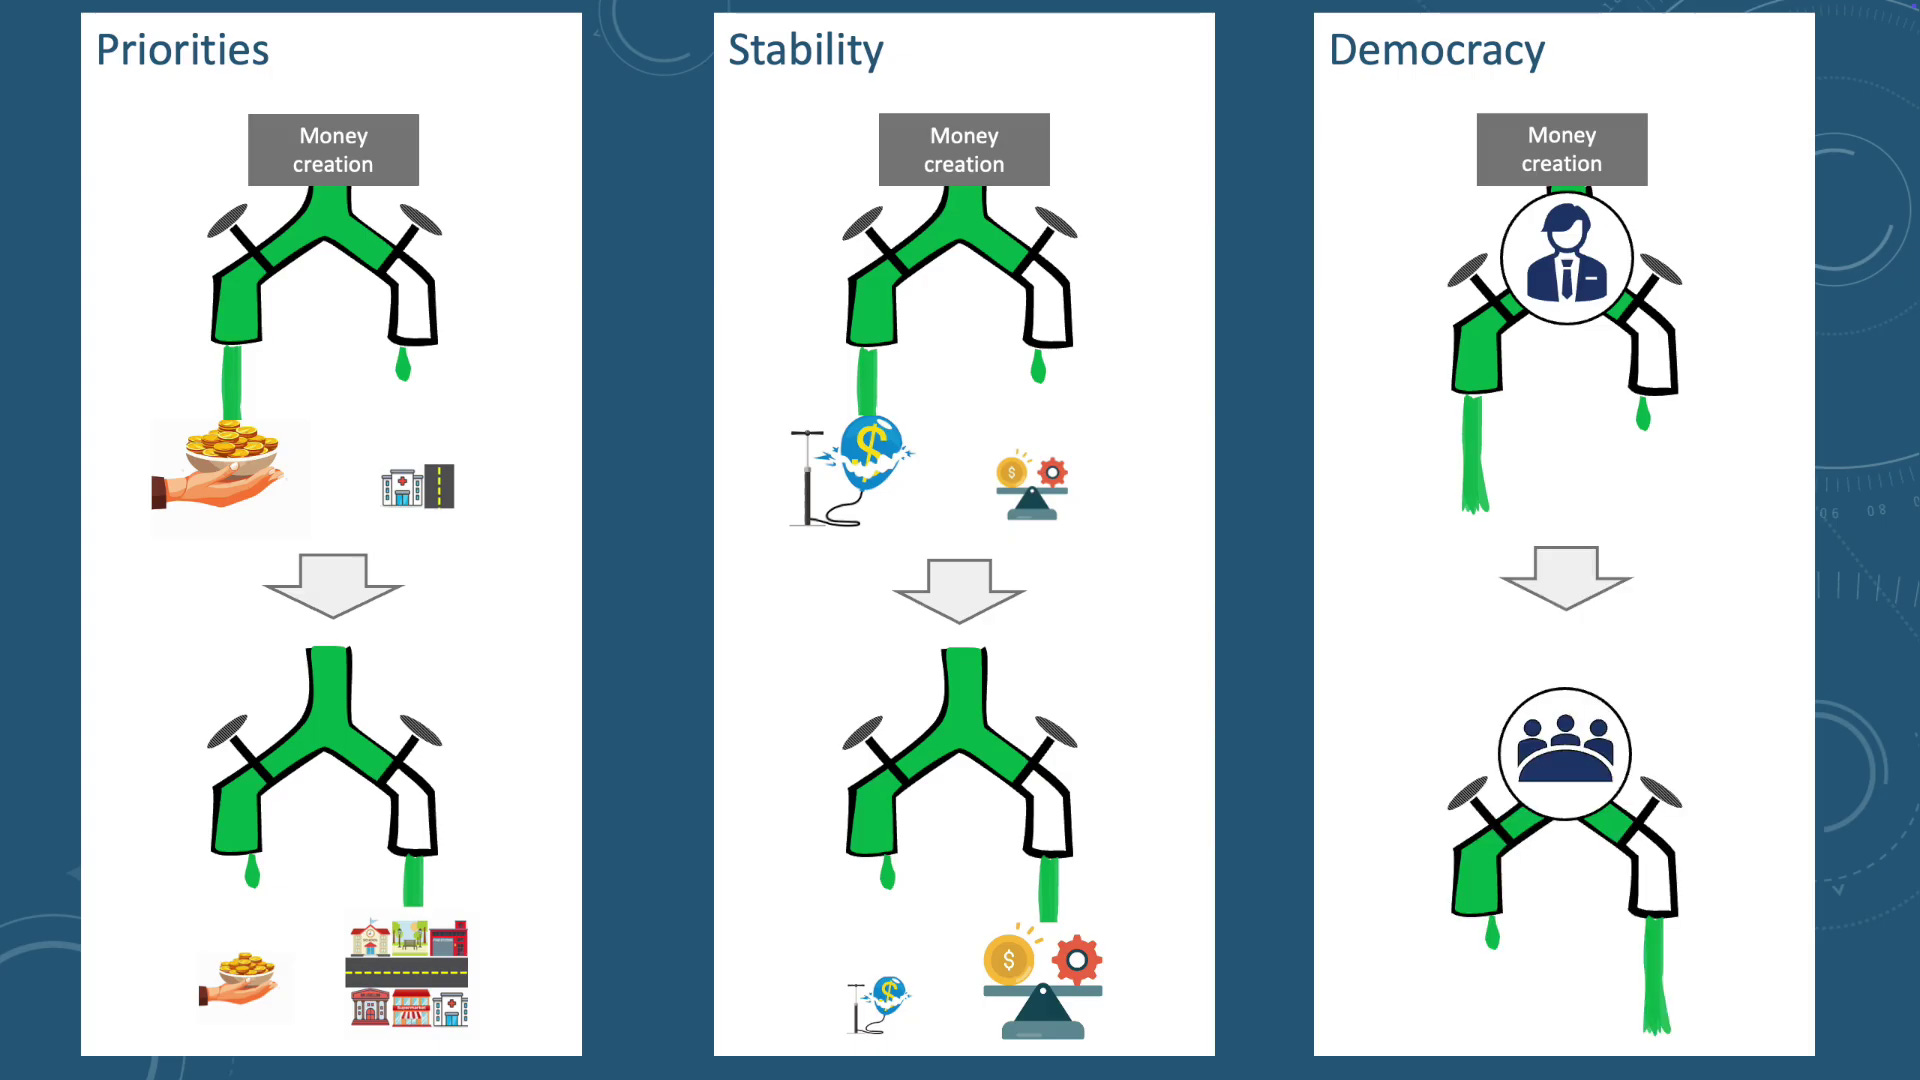
Whereas, there have been systems in the past and that exist in the world today that are far more democratic in terms of who’s making the decisions. And typically, those decision-makers tend to prioritize things that are stabilizing and building public wealth.
Now, whether or not you agree with the diagnosis of these problems – of these things as problems – or you agree with what the alternative solutions are that these folks might be proposing, reasonable people can disagree. And so, we’re not in this video arguing for one or the other. What we’re trying to do is, in broad strokes, provide you with a foundational understanding of how the system works today so that you can decide for yourself what you believe.
And as always, these presentations are based on a lot of scholarship. So please check out the video description notes for the references for this video.
So, we’re going to do this in two parts actually: one part today, and then the second part in another session. And today, we’re going to talk about the accounting, and we’re going to talk about the limits on bank money creation.
So how is it that banks actually run this accounting system and create money using it? And just to say that it’s not scary, don’t be worried. You don’t need to know a lot about money or finance, or any of those things, or accounting. And my hope in sharing this with you is that you will understand it at a high enough level that you will find it empowering to know, even if you don’t know the details or couldn’t teach them to somebody else, you’ll know where to find them.
Okay, so how much money does the government create? Let’s start there, little accounting. Let’s account for where money comes from.
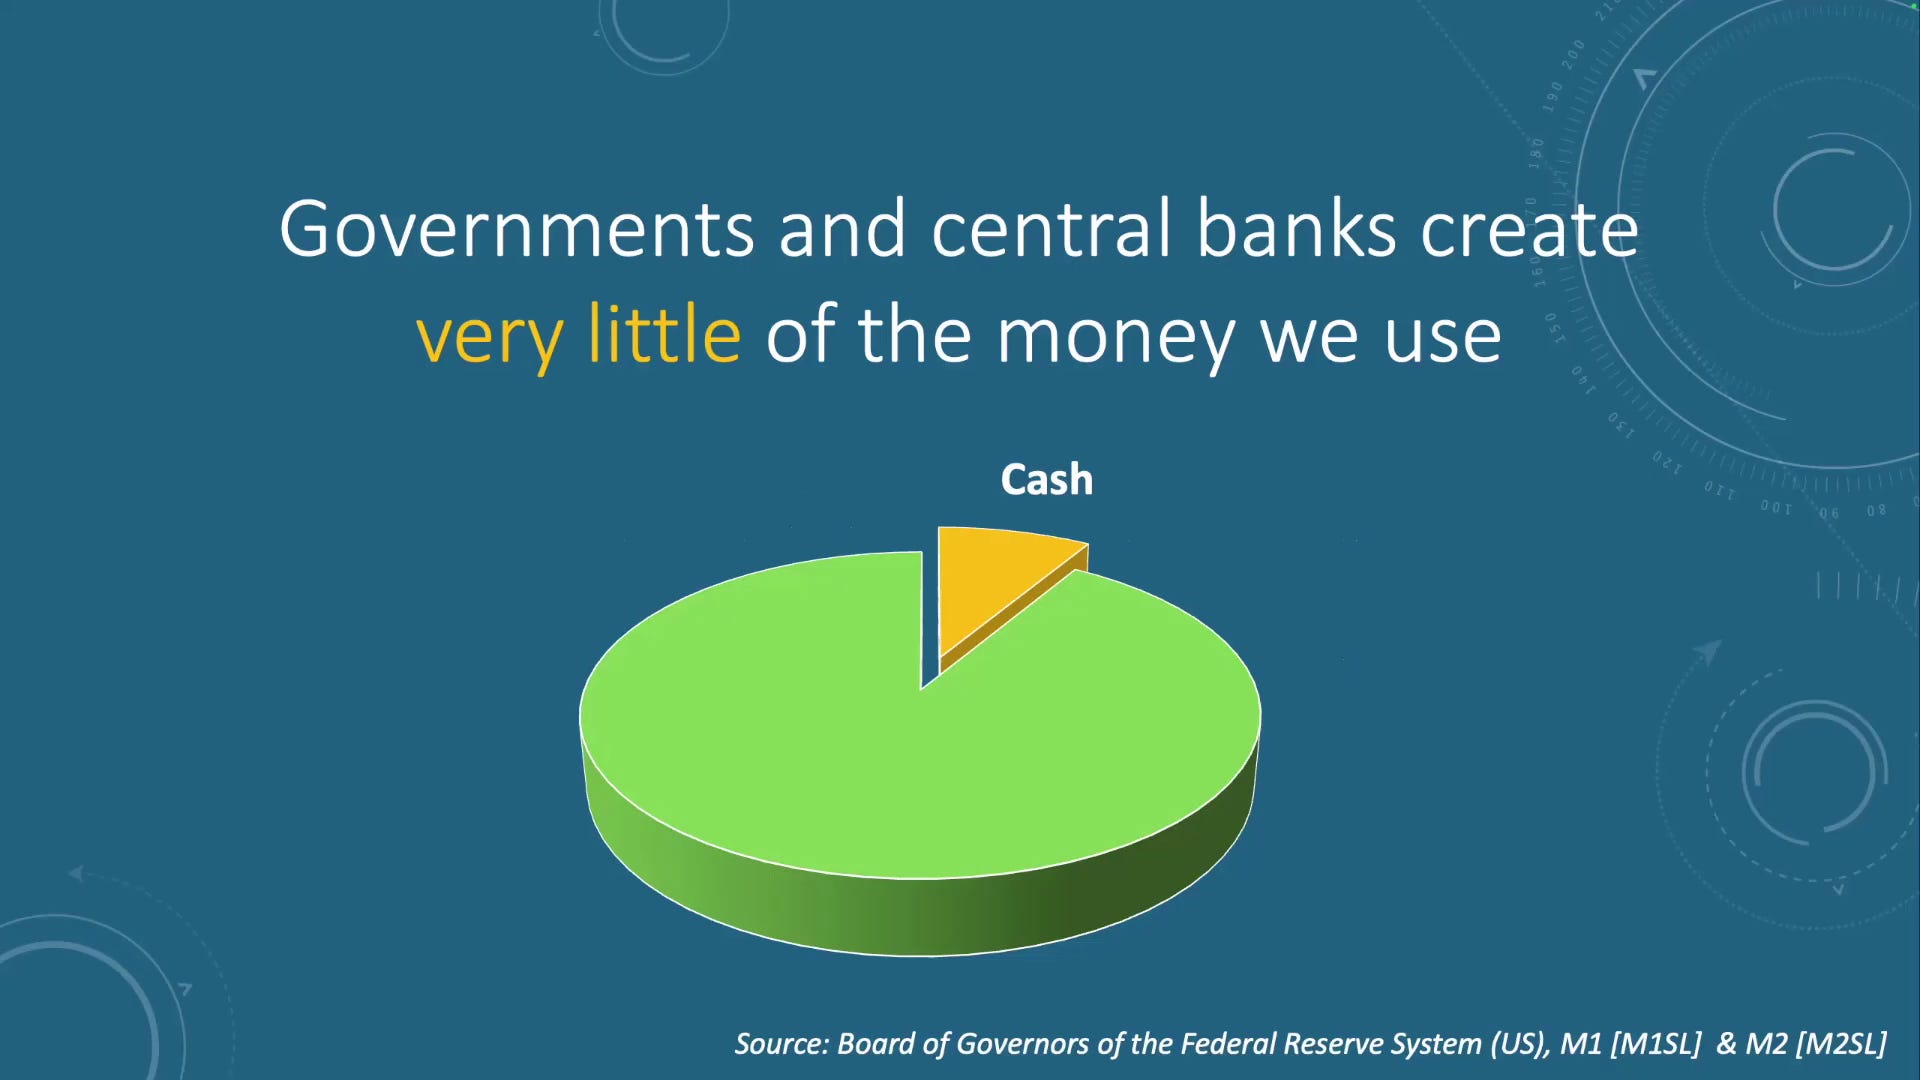
And the thing that’s quite surprising to many people and was to myself when I first learned it is that governments and central banks create very little of the money we use. We actually have survey data that shows 22,000 people across 22 countries, that only about 20% of people are aware of this.
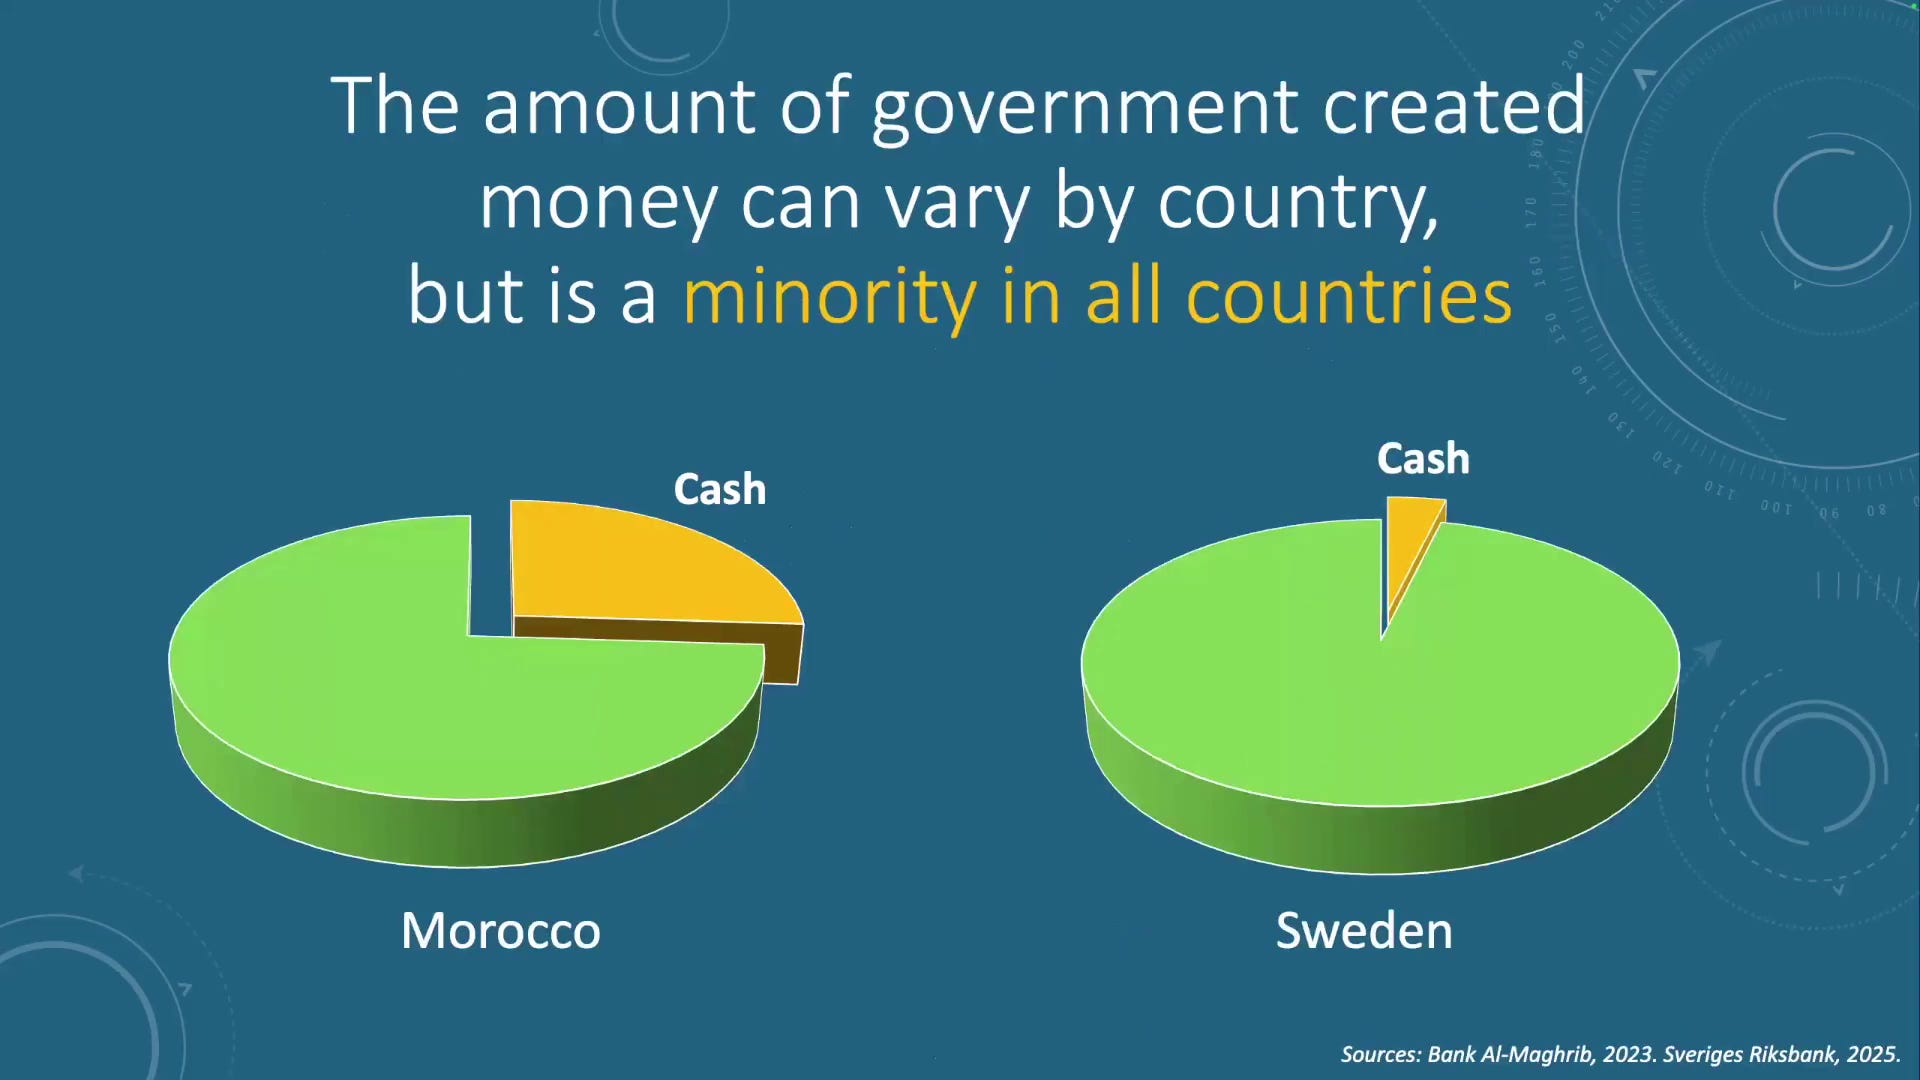
So that amount that the government creates is the cash and coins. And this is true – this ratio is true in countries all around the world. The minority of the money in circulation is created by the government. This is true in Morocco, where it’s one of the highest cash using societies on the planet. There, only about 30% of the money supply, is created by the government. And in Sweden, where they use almost no cash anymore, it’s only about 3%. But still in all cases, it’s a minority.
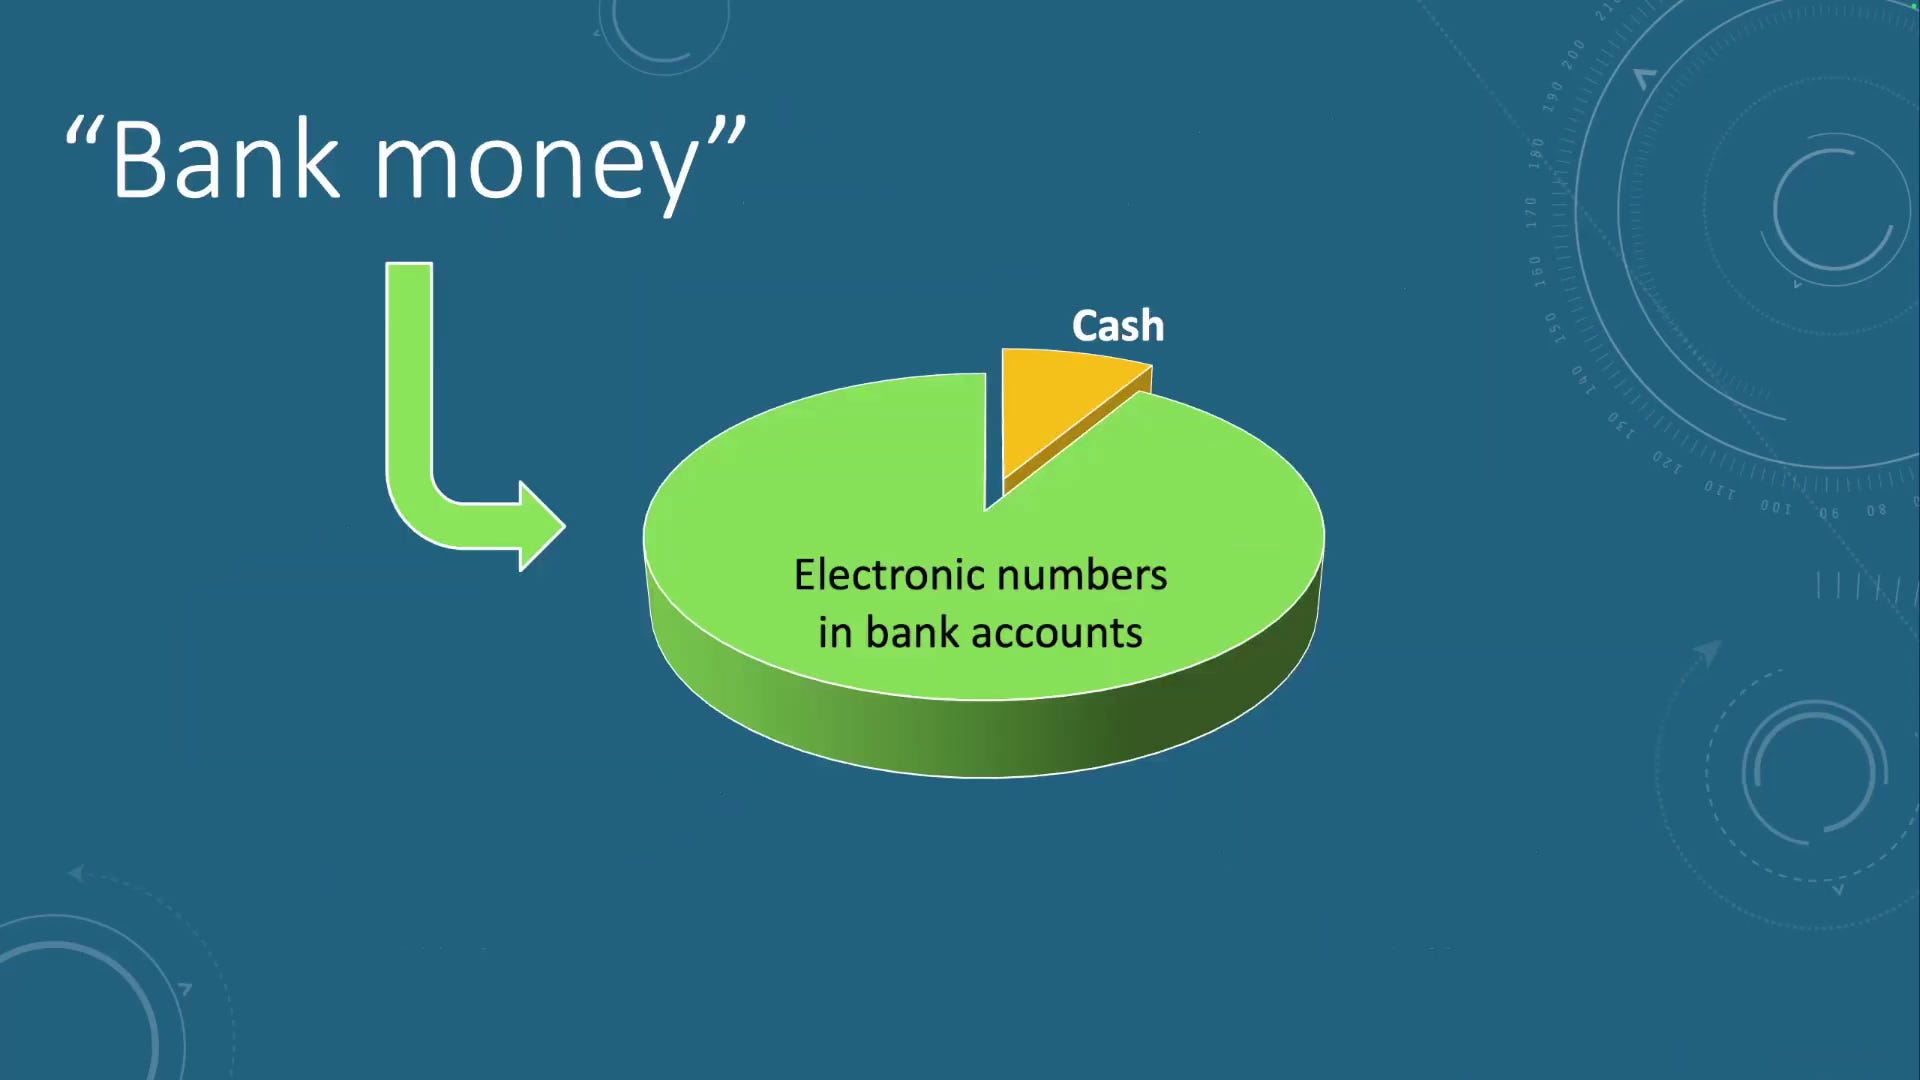
So, what is the rest of that money? It's bank money. It's just the electronic numbers in bank accounts. It's the only place that exists is in the accounting records of banks.
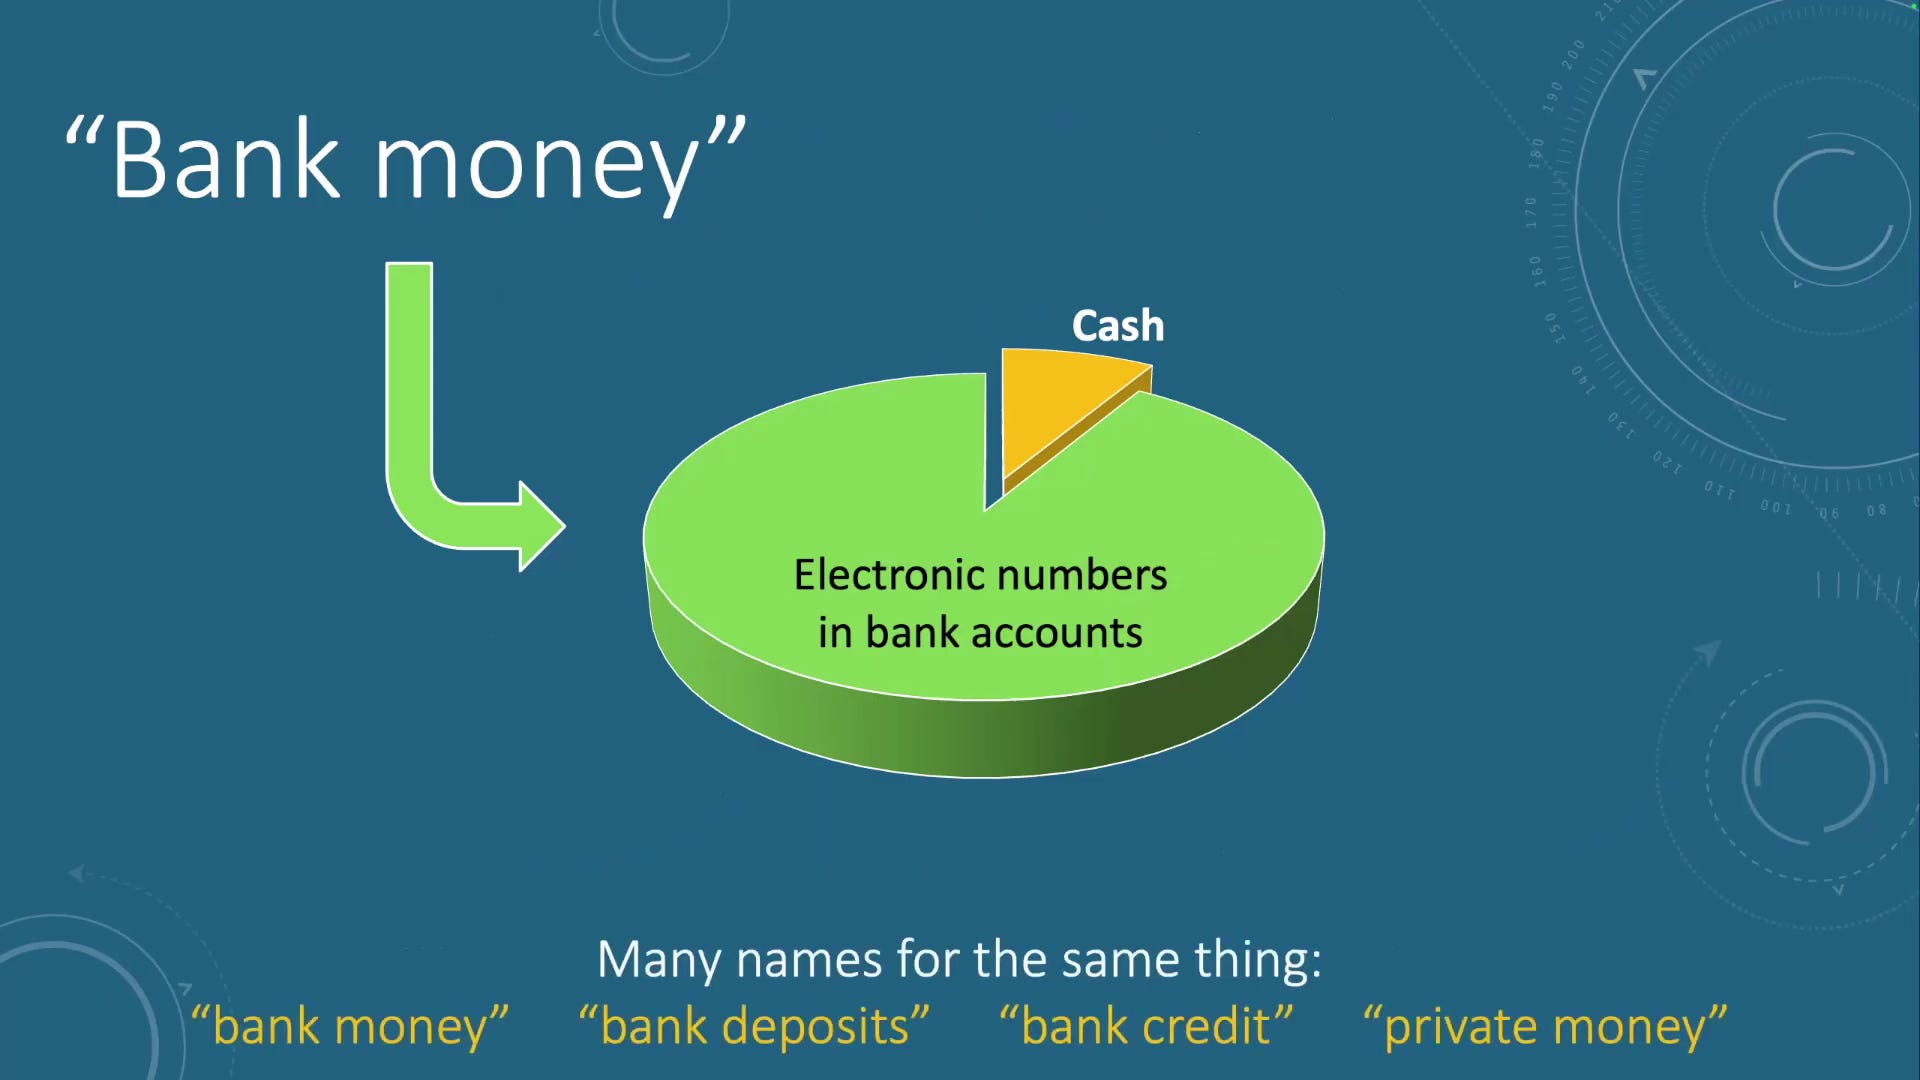
And this bank money goes by a number of different names. If you’re looking in the literature, there’s bank money, there’s bank deposits, which is probably the term you’re most familiar with, there’s bank credit, there’s private money – all of these terms are referring to the electronic numbers in bank accounts.
And I try to use bank money because bank deposits is misleading. It suggests that bank deposits originate with some physical thing being delivered to a bank and as government-created cash or coins, and that’s not the case as you’ll learn.
So where does bank money come from?
As I mentioned, most of us are not aware really of how it comes into existence, and there’s been numerous studies. This is actually an interview that’s being done on the streets in Germany by their public television station.
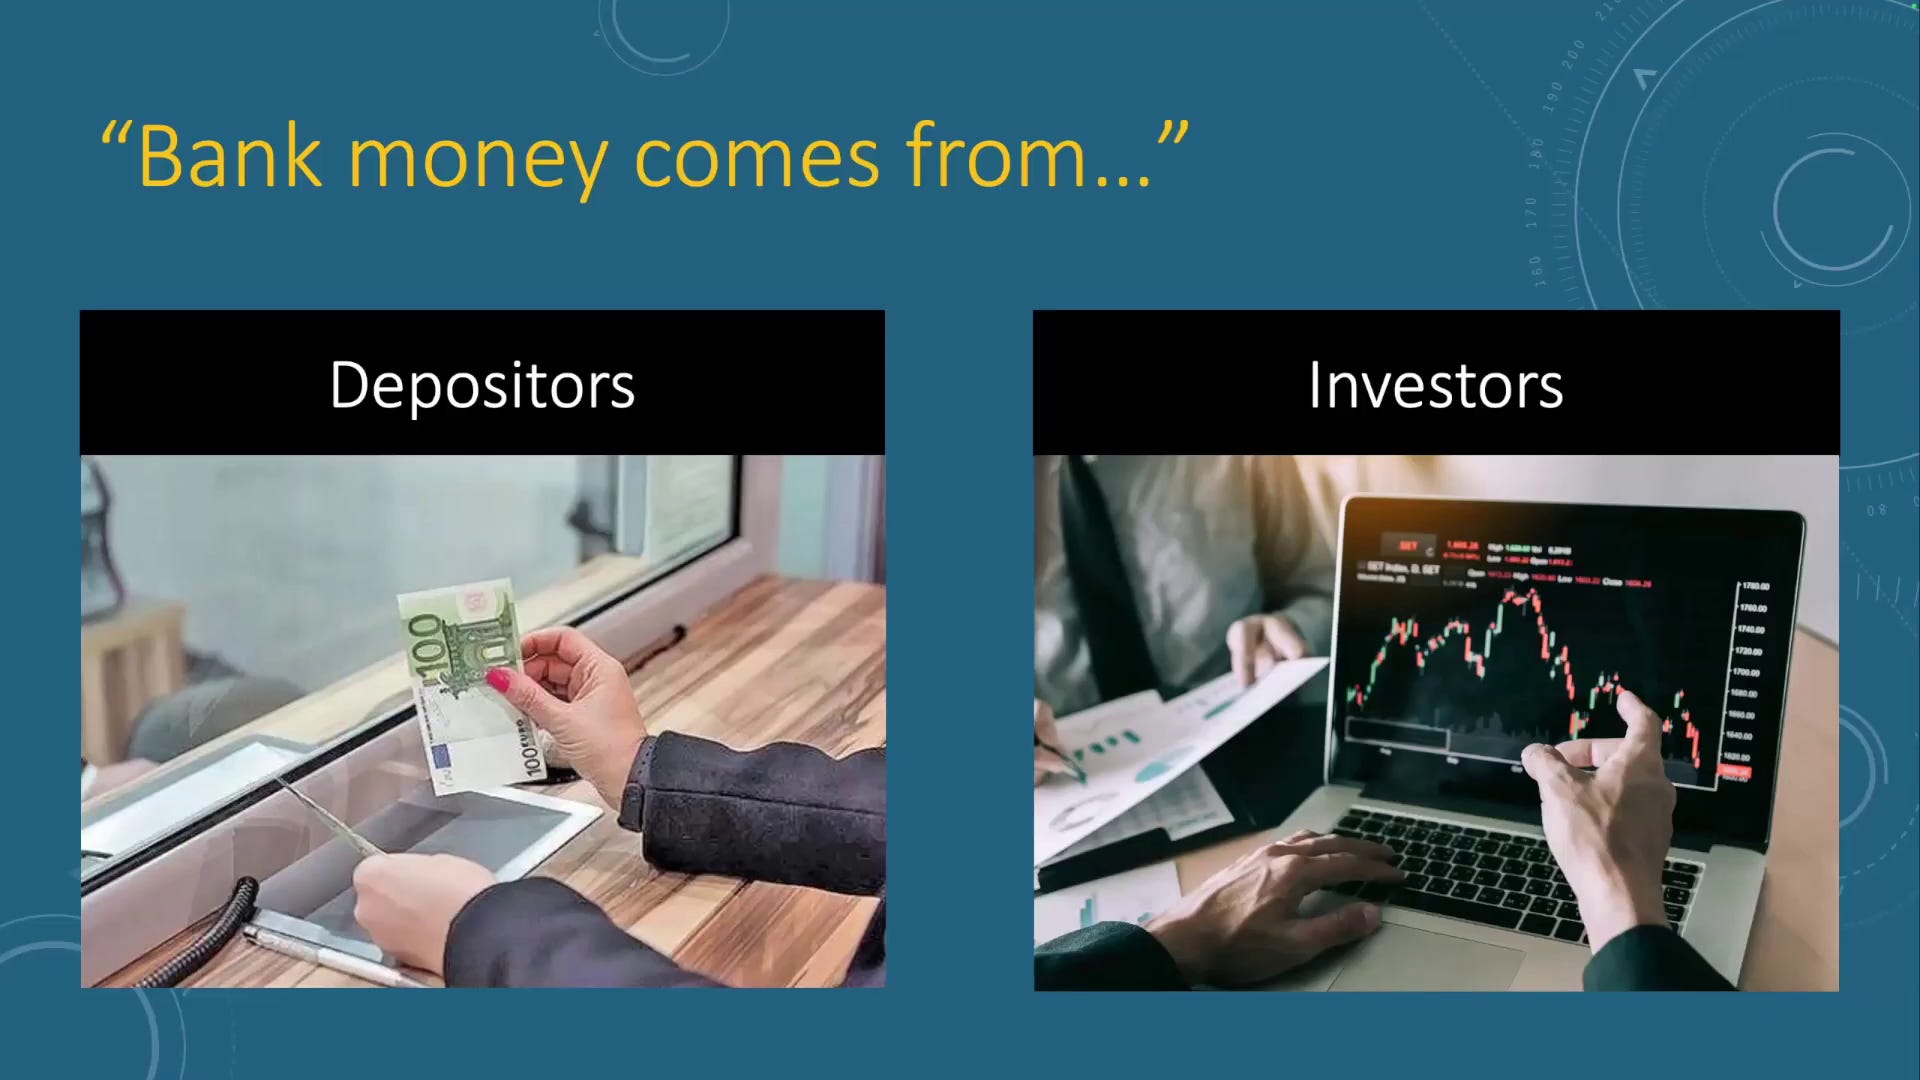
And when we ask people, where does bank money come from? Most people say it’s depositors putting money in the bank, or investors putting money in the bank.
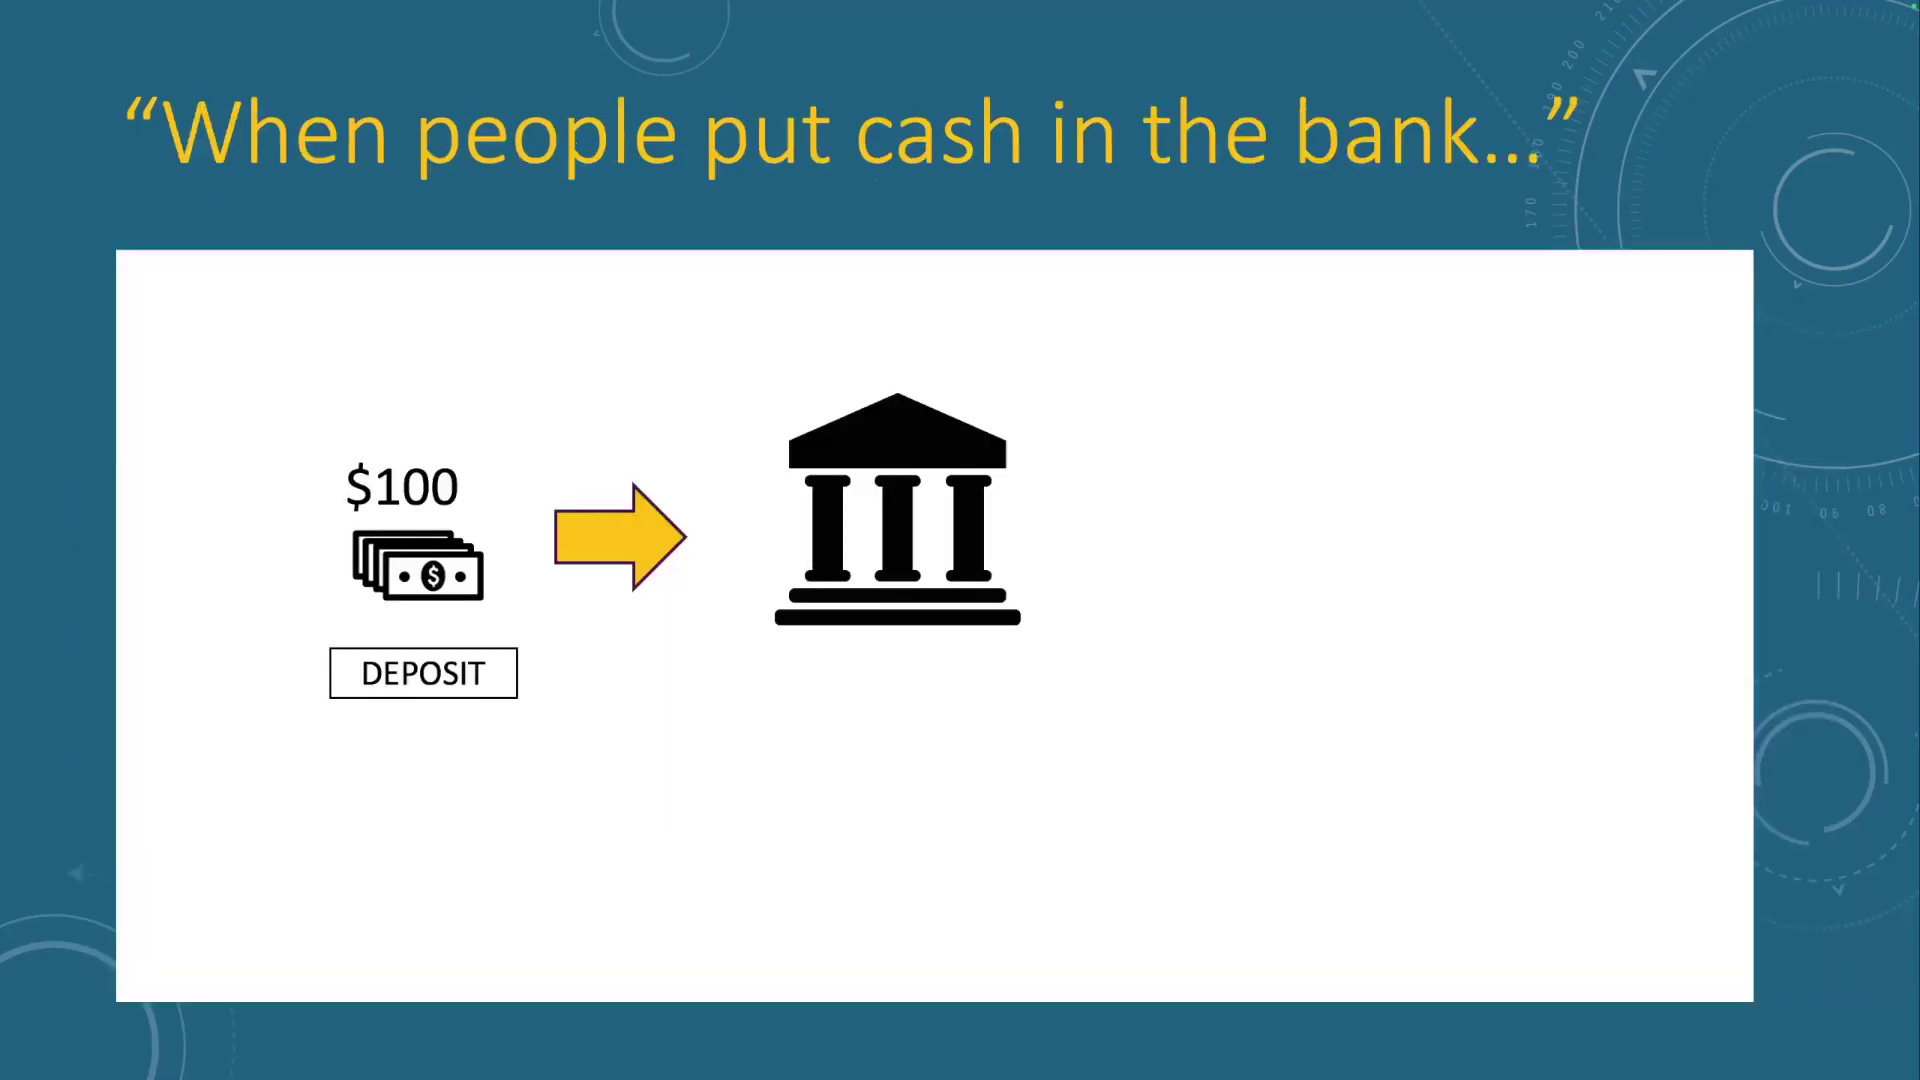
And it looks like this: when people put cash in the bank…
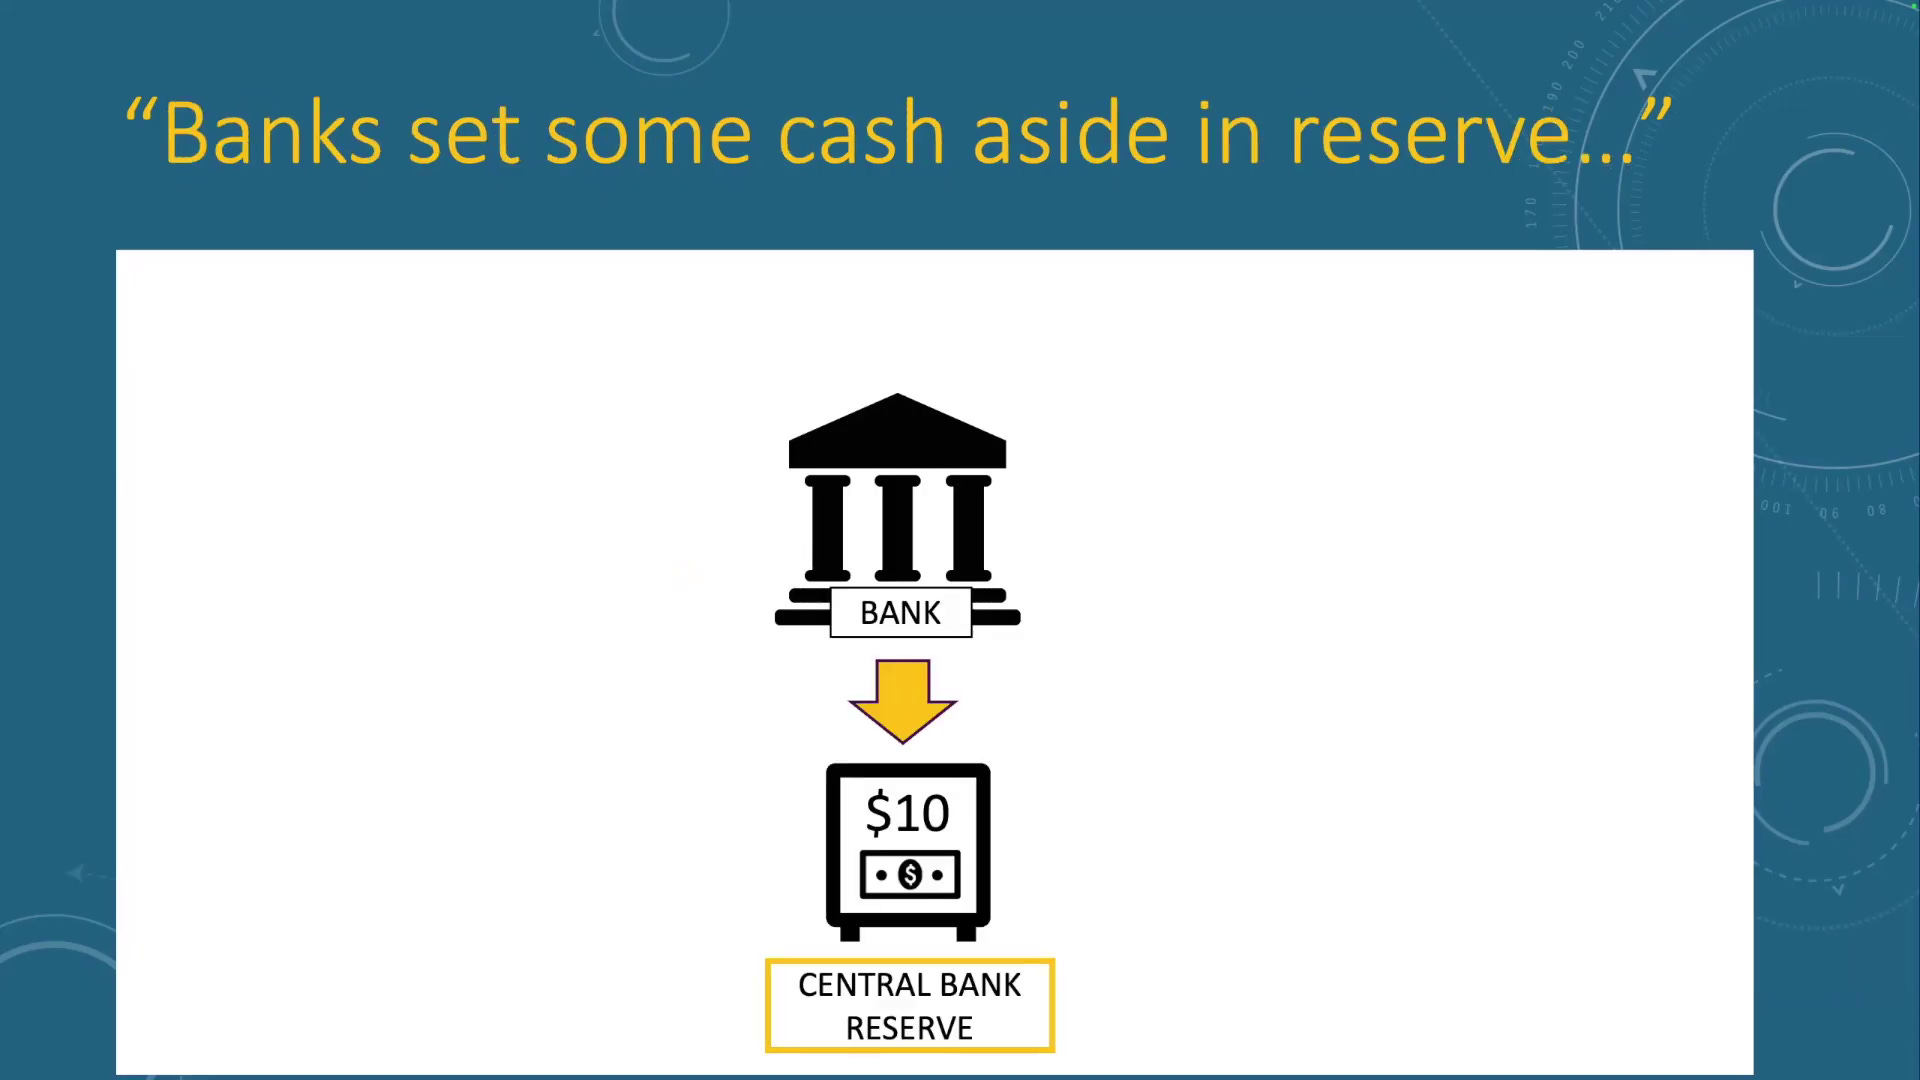
The bank sets aside some of it in reserve at the central bank, let’s say 10% of it…
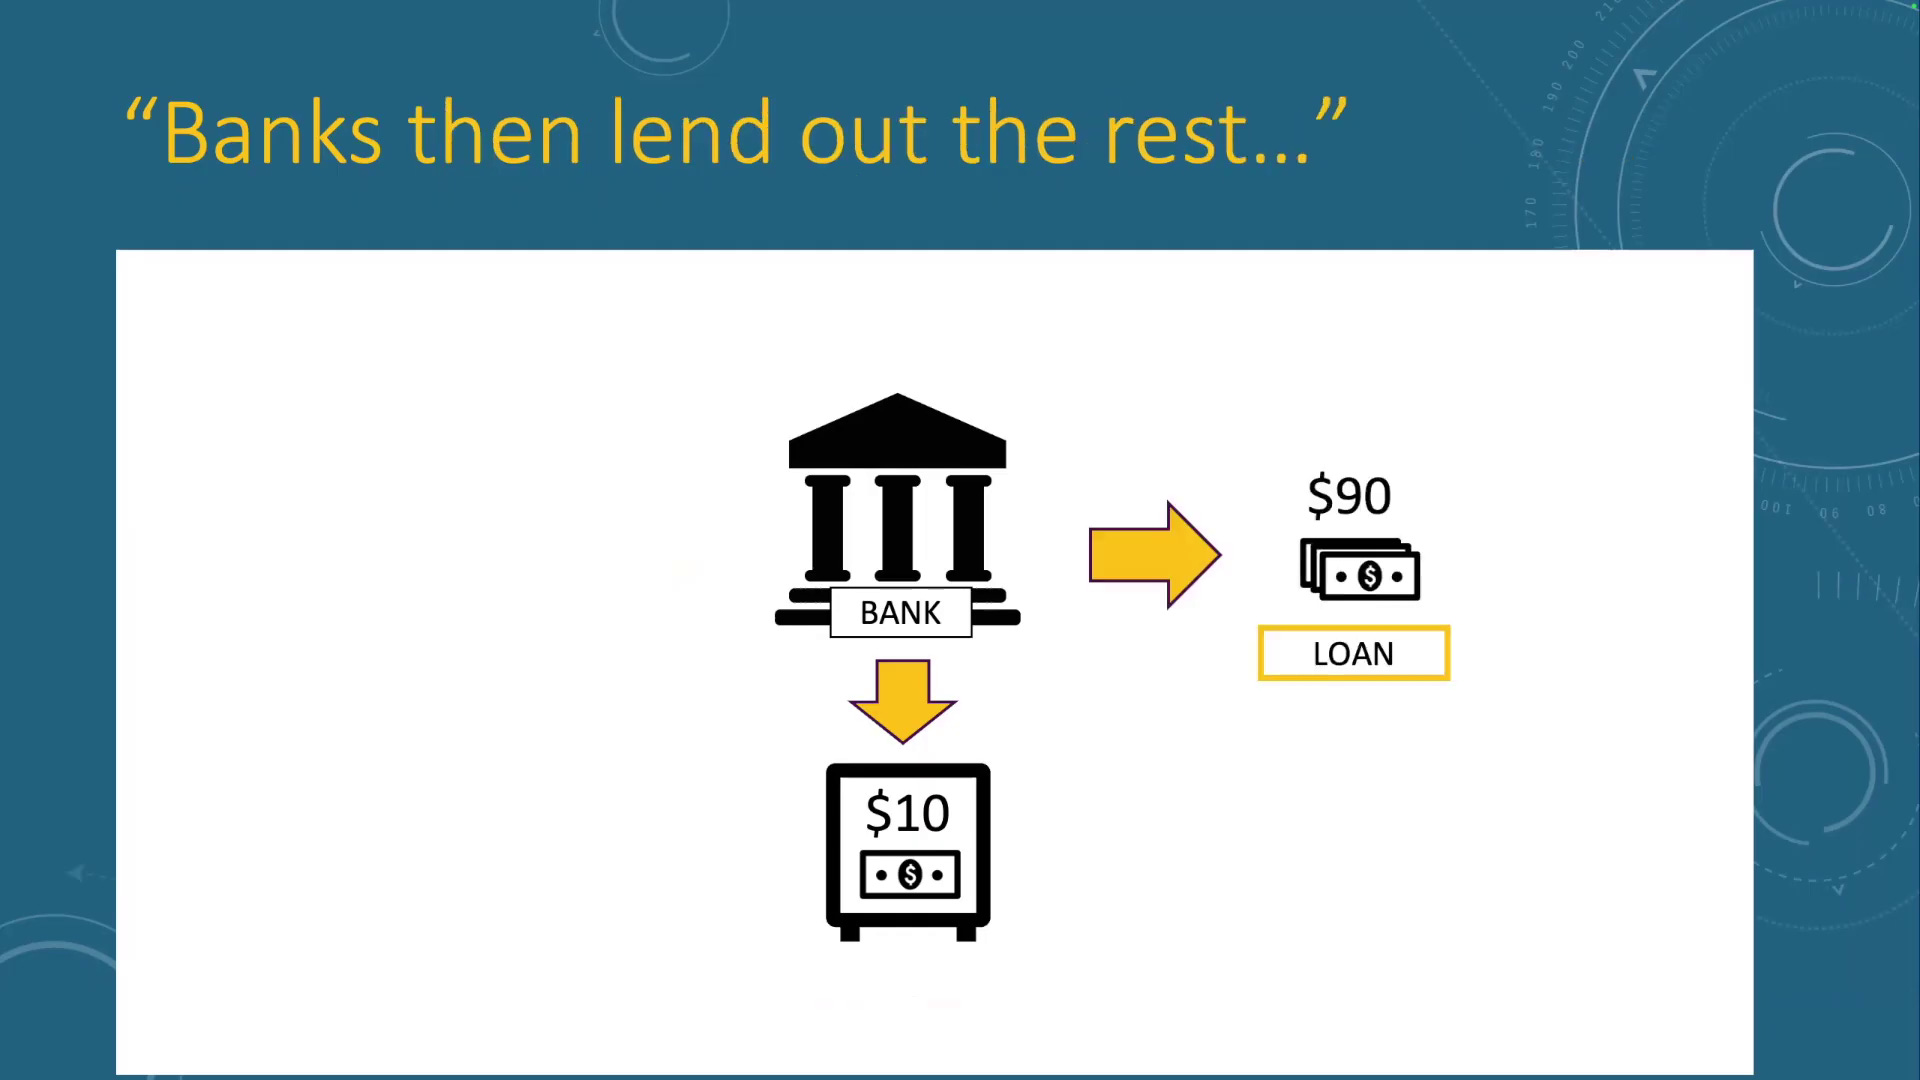
And then they lend out the rest. And that’s how most people understand the way that banks lend money.
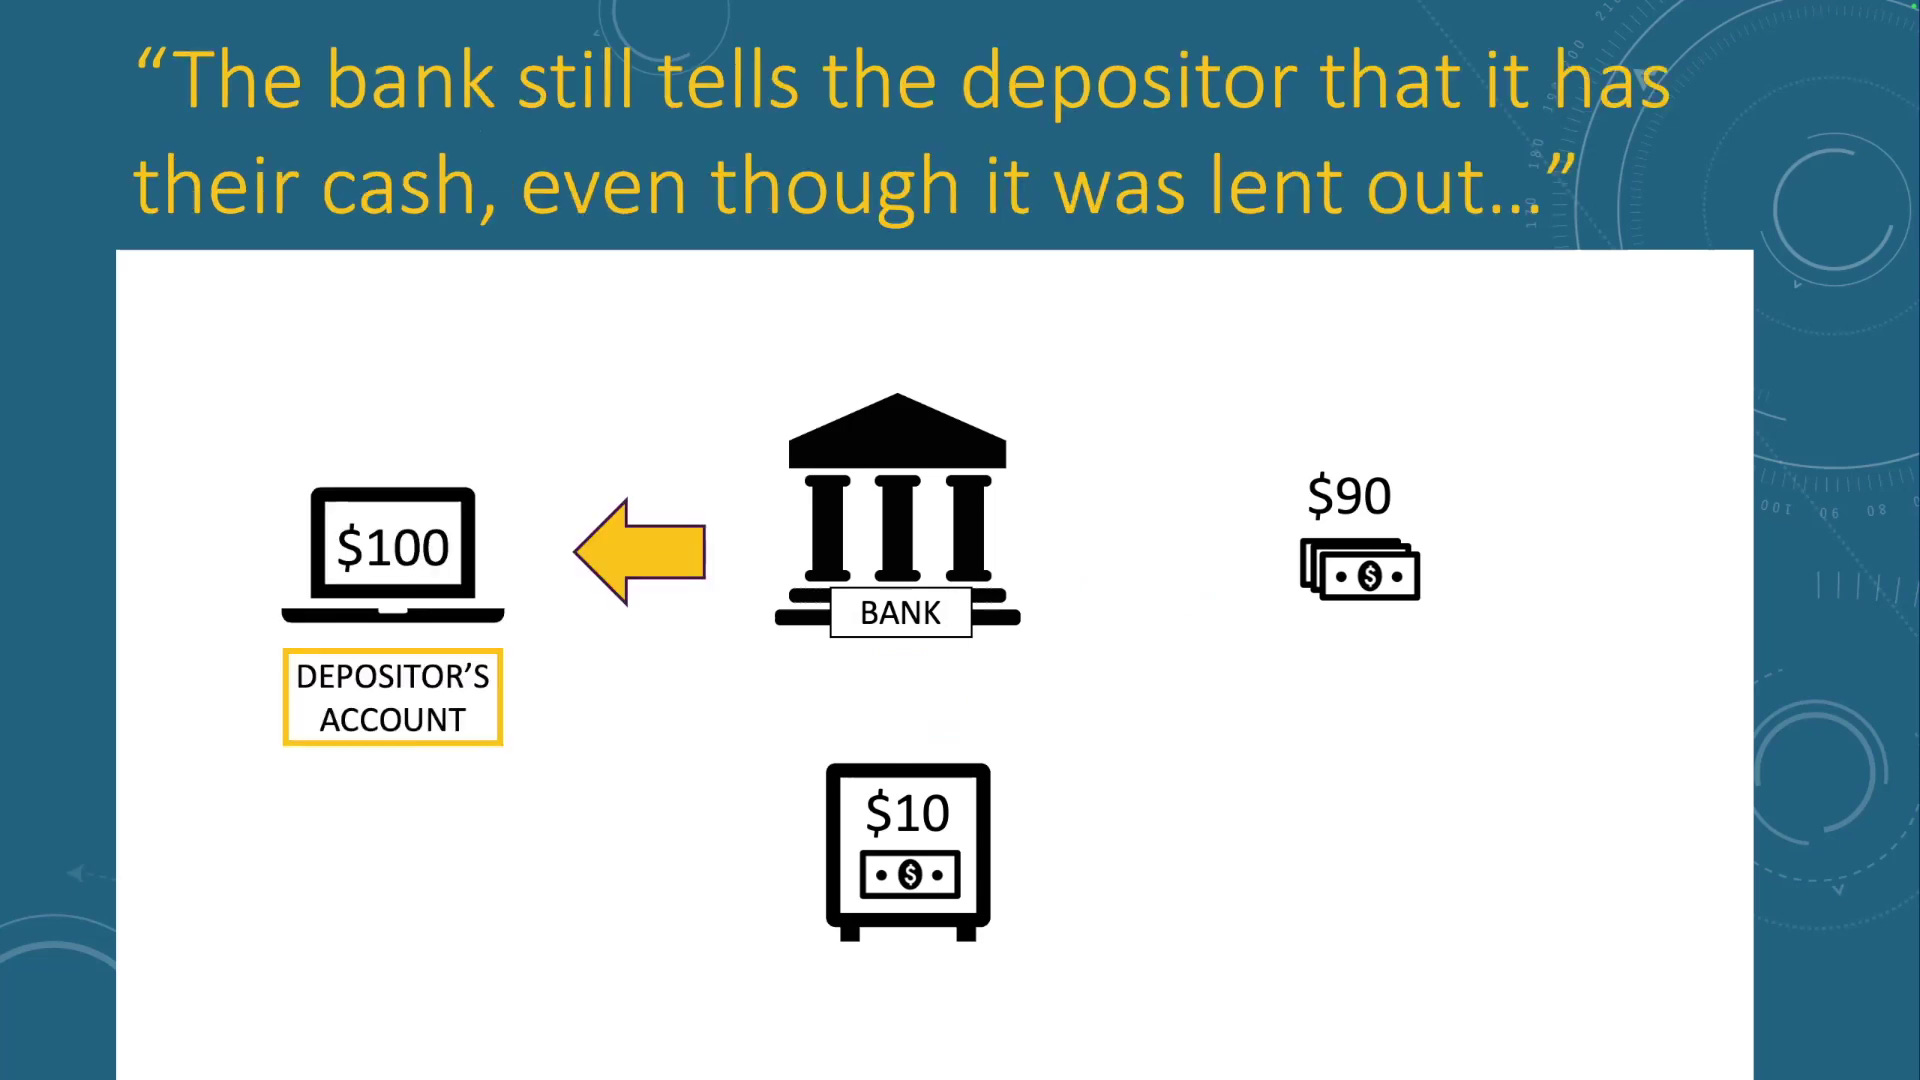
And then, interestingly, most people do understand that banks continue to tell the original depositor that it has their cash, even though it was lent out.
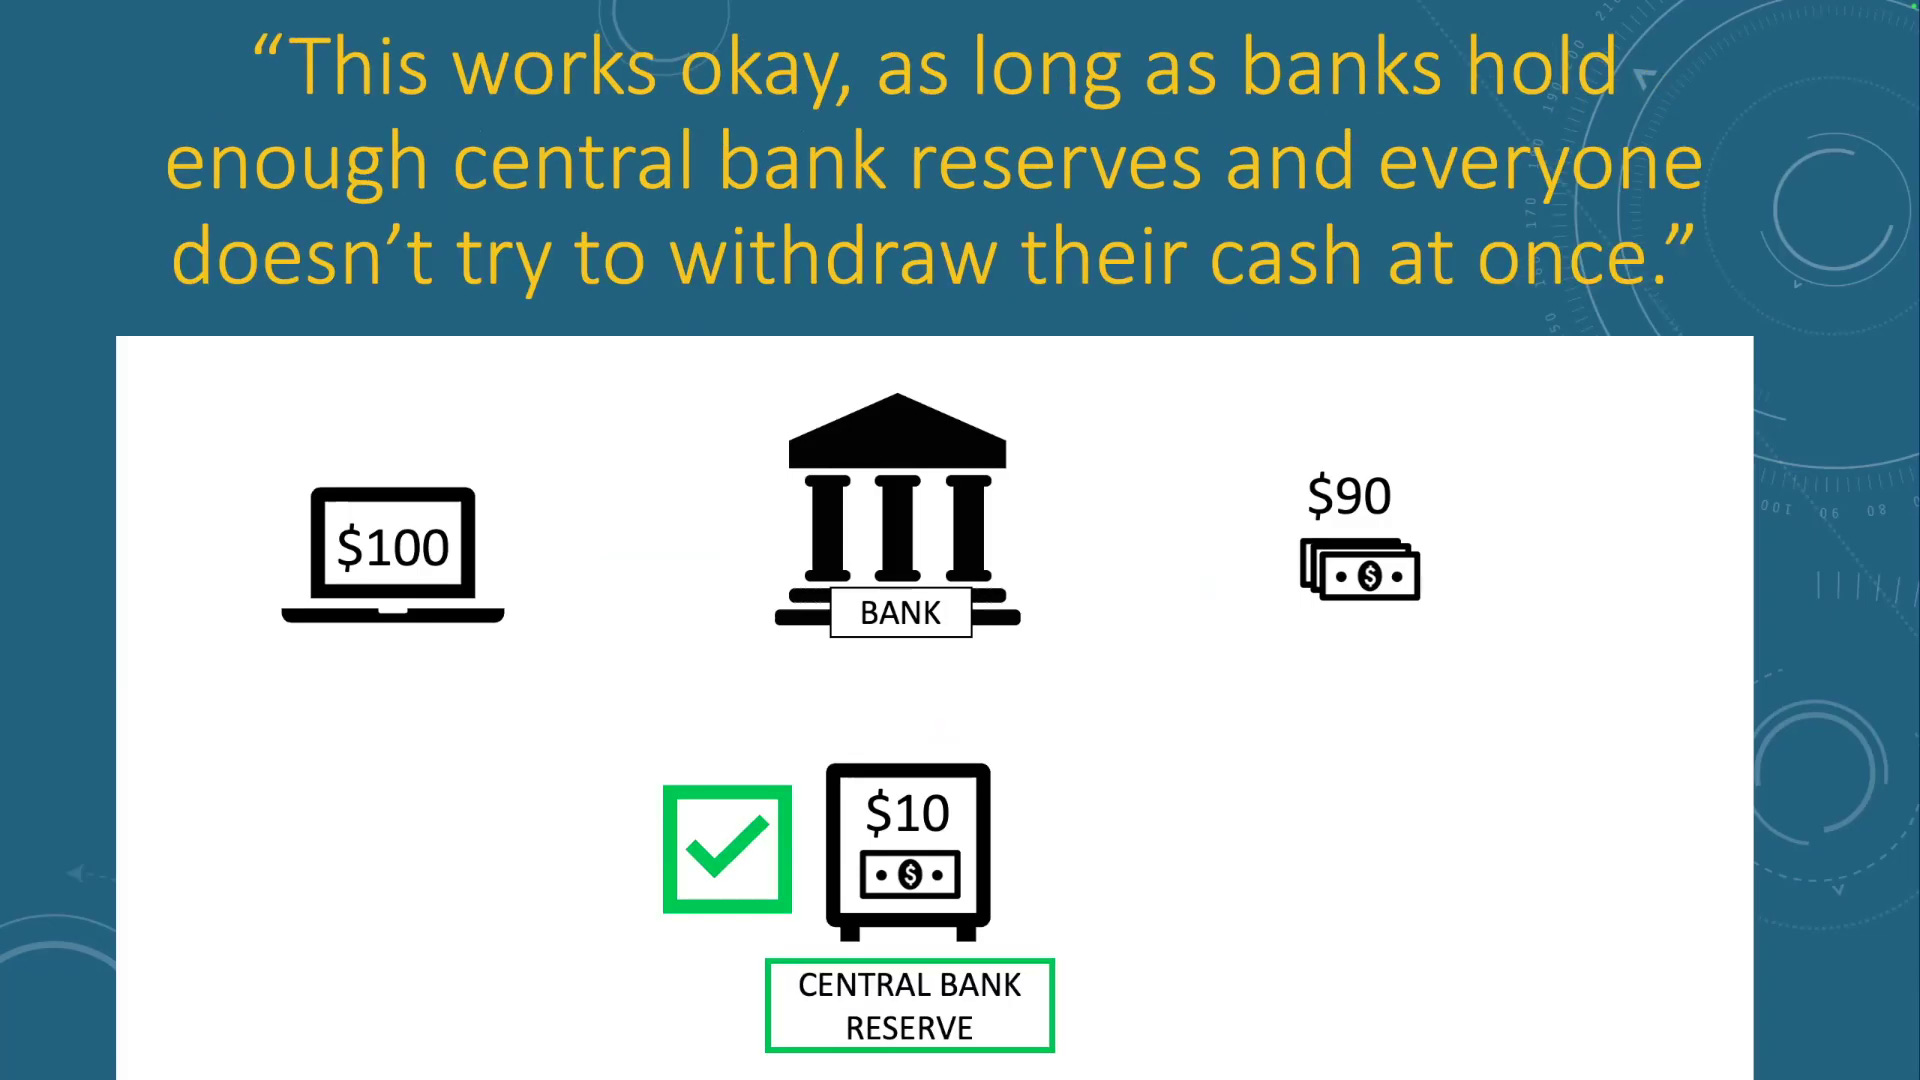
And the thought is that this works okay, as long as banks hold enough cash at the central bank in reserve and everyone doesn’t try to withdraw their cash at once. In fact, this is the story that we often hear in the news.
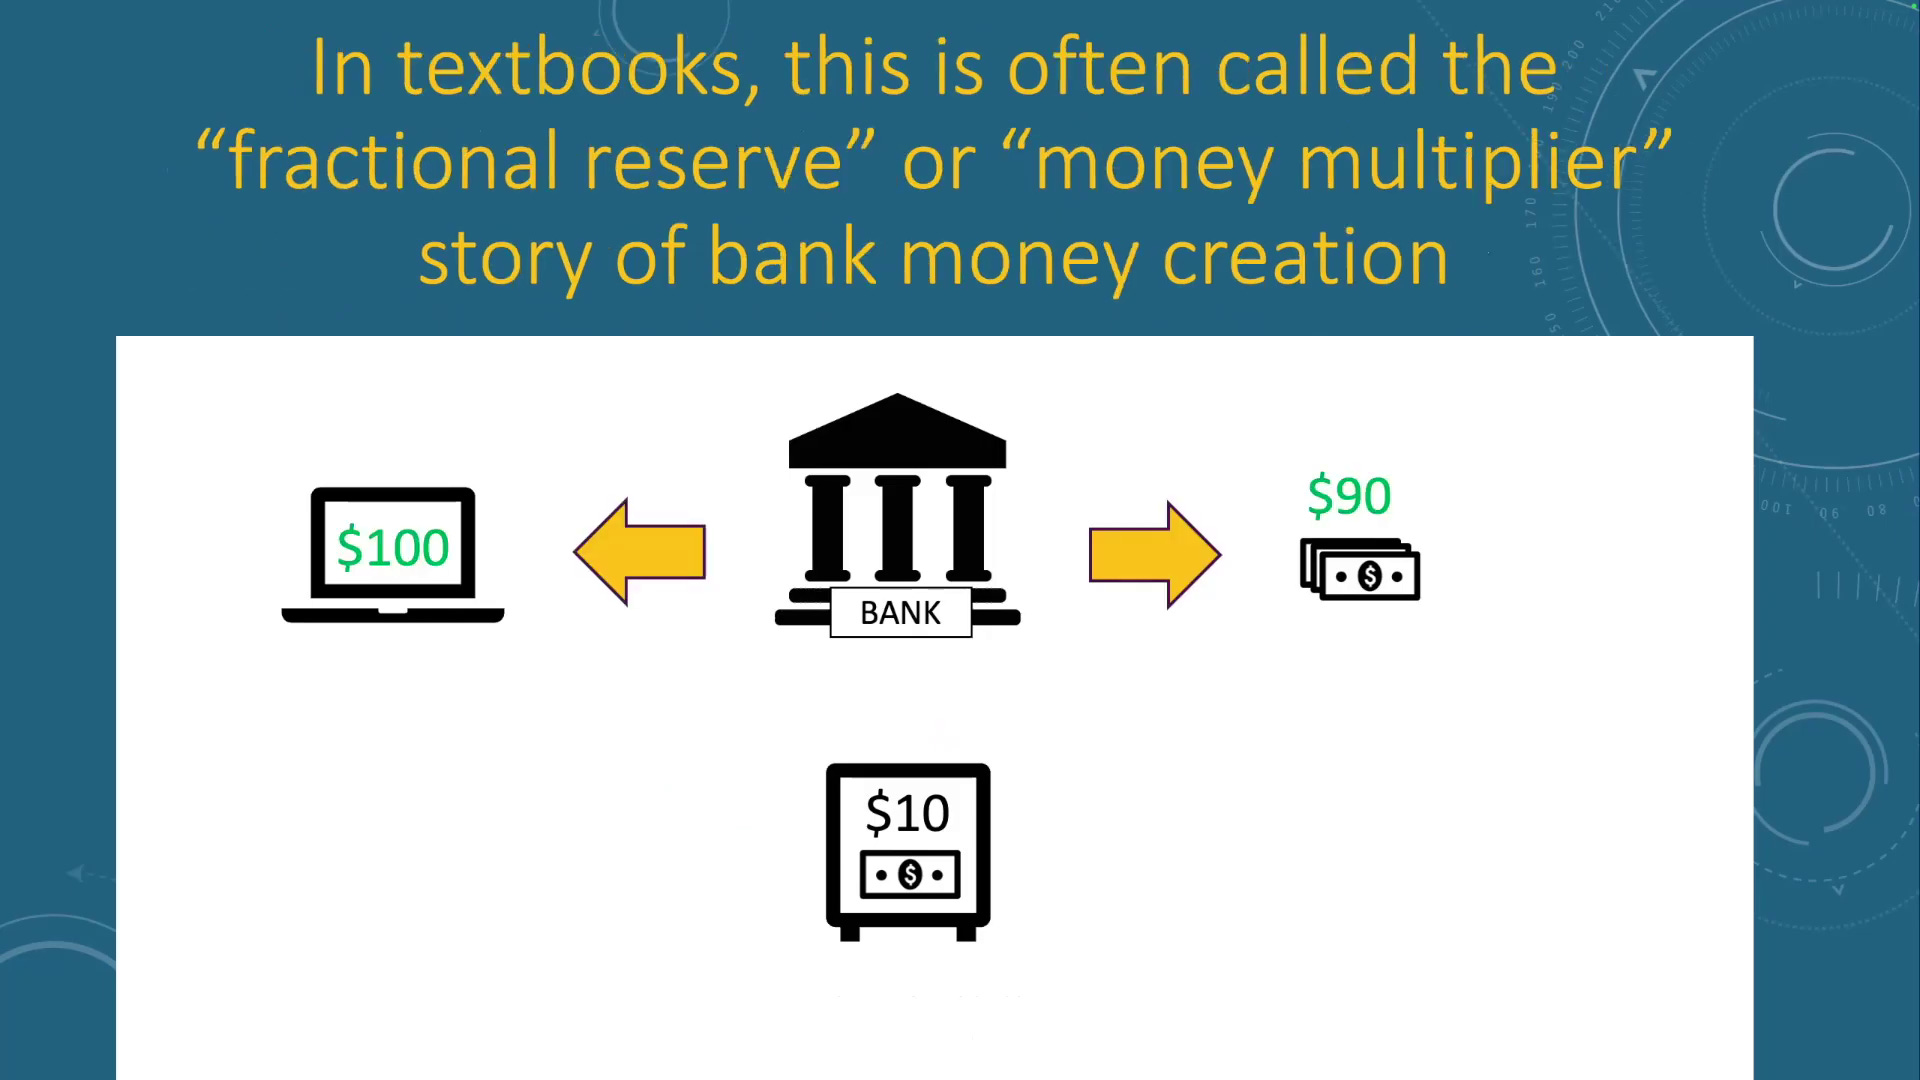
And in textbooks, this is often called the “fractional reserve” or “money-multiplier” story of bank money creation, because as you can see, it expands the money supply. The depositor still has $100 in their bank account when they look in their bank account, and that’s money that they can actually spend. They can write a check or make an electronic payment. Meanwhile, the borrower has $90 in cash. So the economy now has $190 in money that can be spent, whereas it only had $90 or $100 before that was deposited by the original depositor. Again, this is the story. This is what you’ll find in many textbooks. It goes by the name of “fractional reserve” or “money multiplier.”
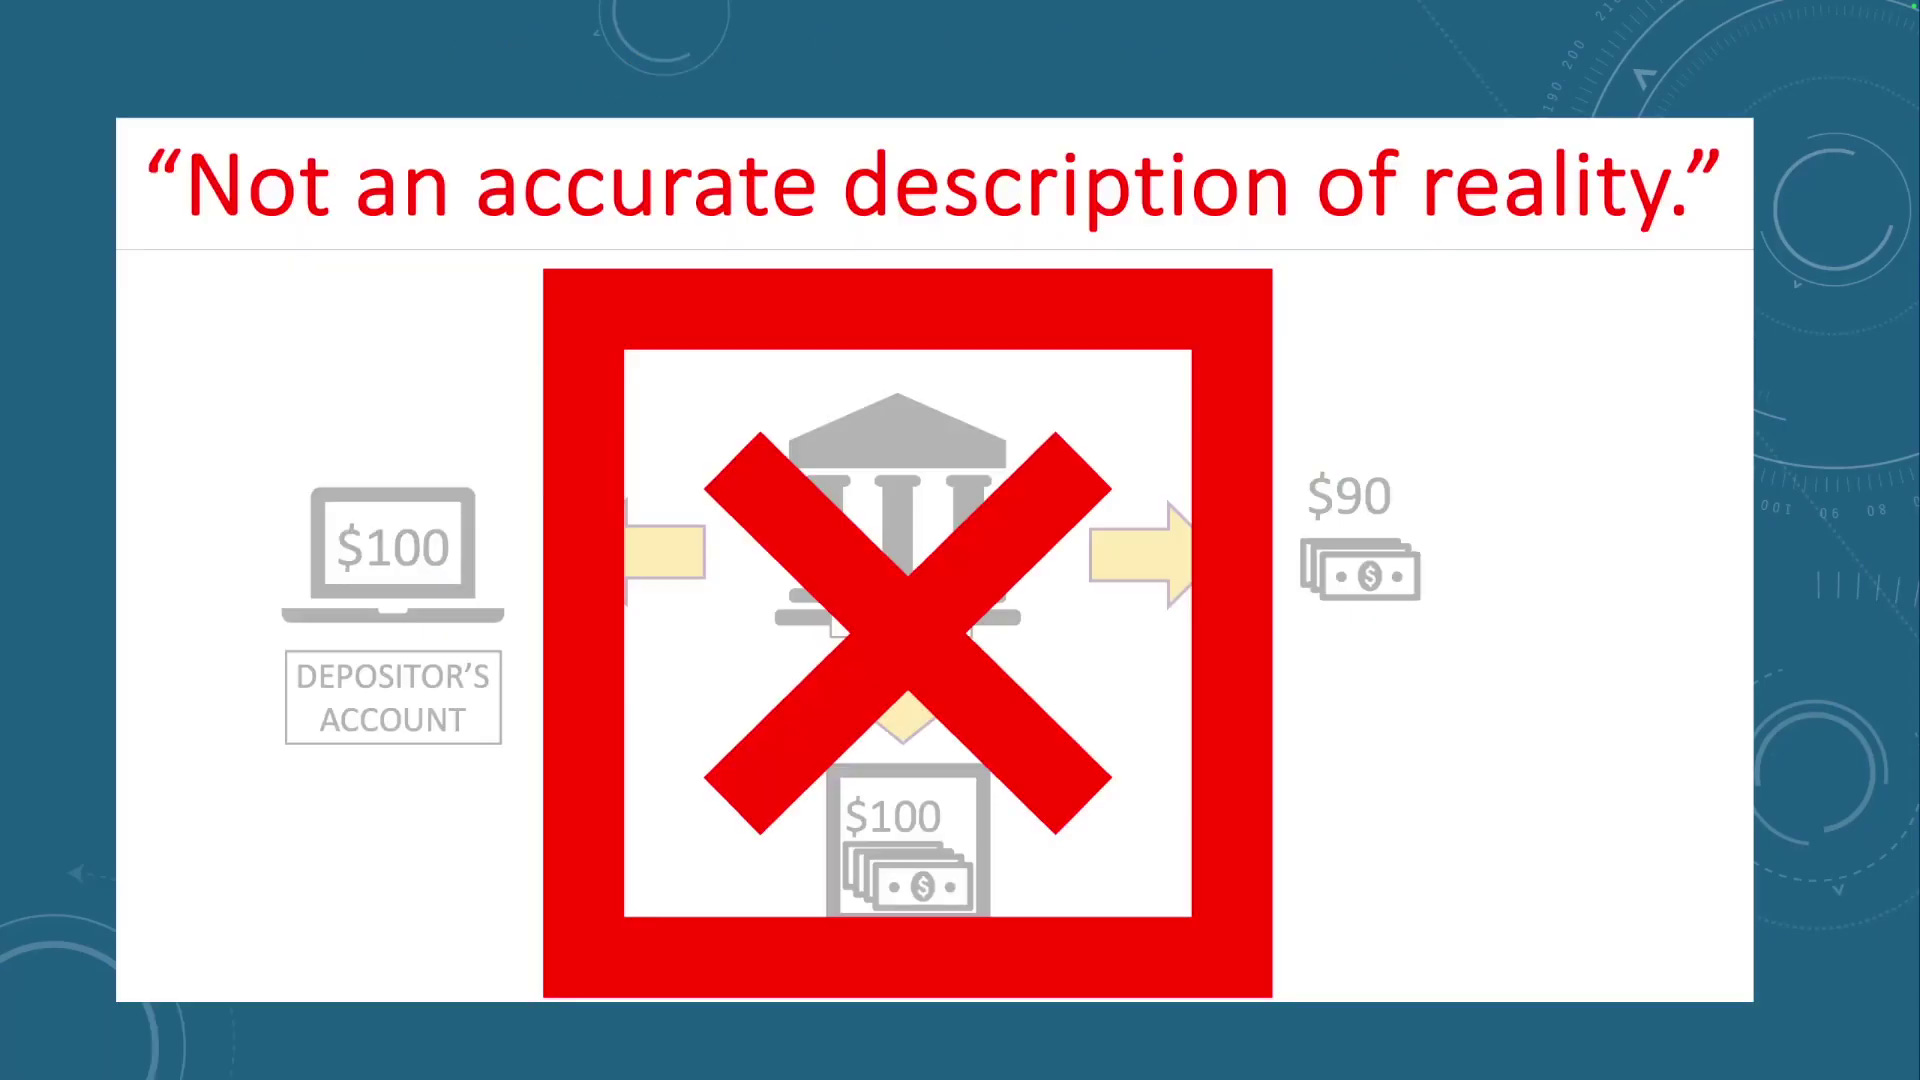
There’s just one problem, which is that it is “not an accurate description of reality.”
And that’s not me saying that, that is the Bank of England, which is one of the most venerated central banks in the world. It’s actually the prototype for all the central banks in the world and really the original source of this national money system when it was formed in 1694, as we told that story in the last video.
So they published a bulletin in 2014 titled “Money Creation in the Modern Economy.” It’s become a seminal publication cited by over 2,000 academic works and books, because it states very clearly some important things.
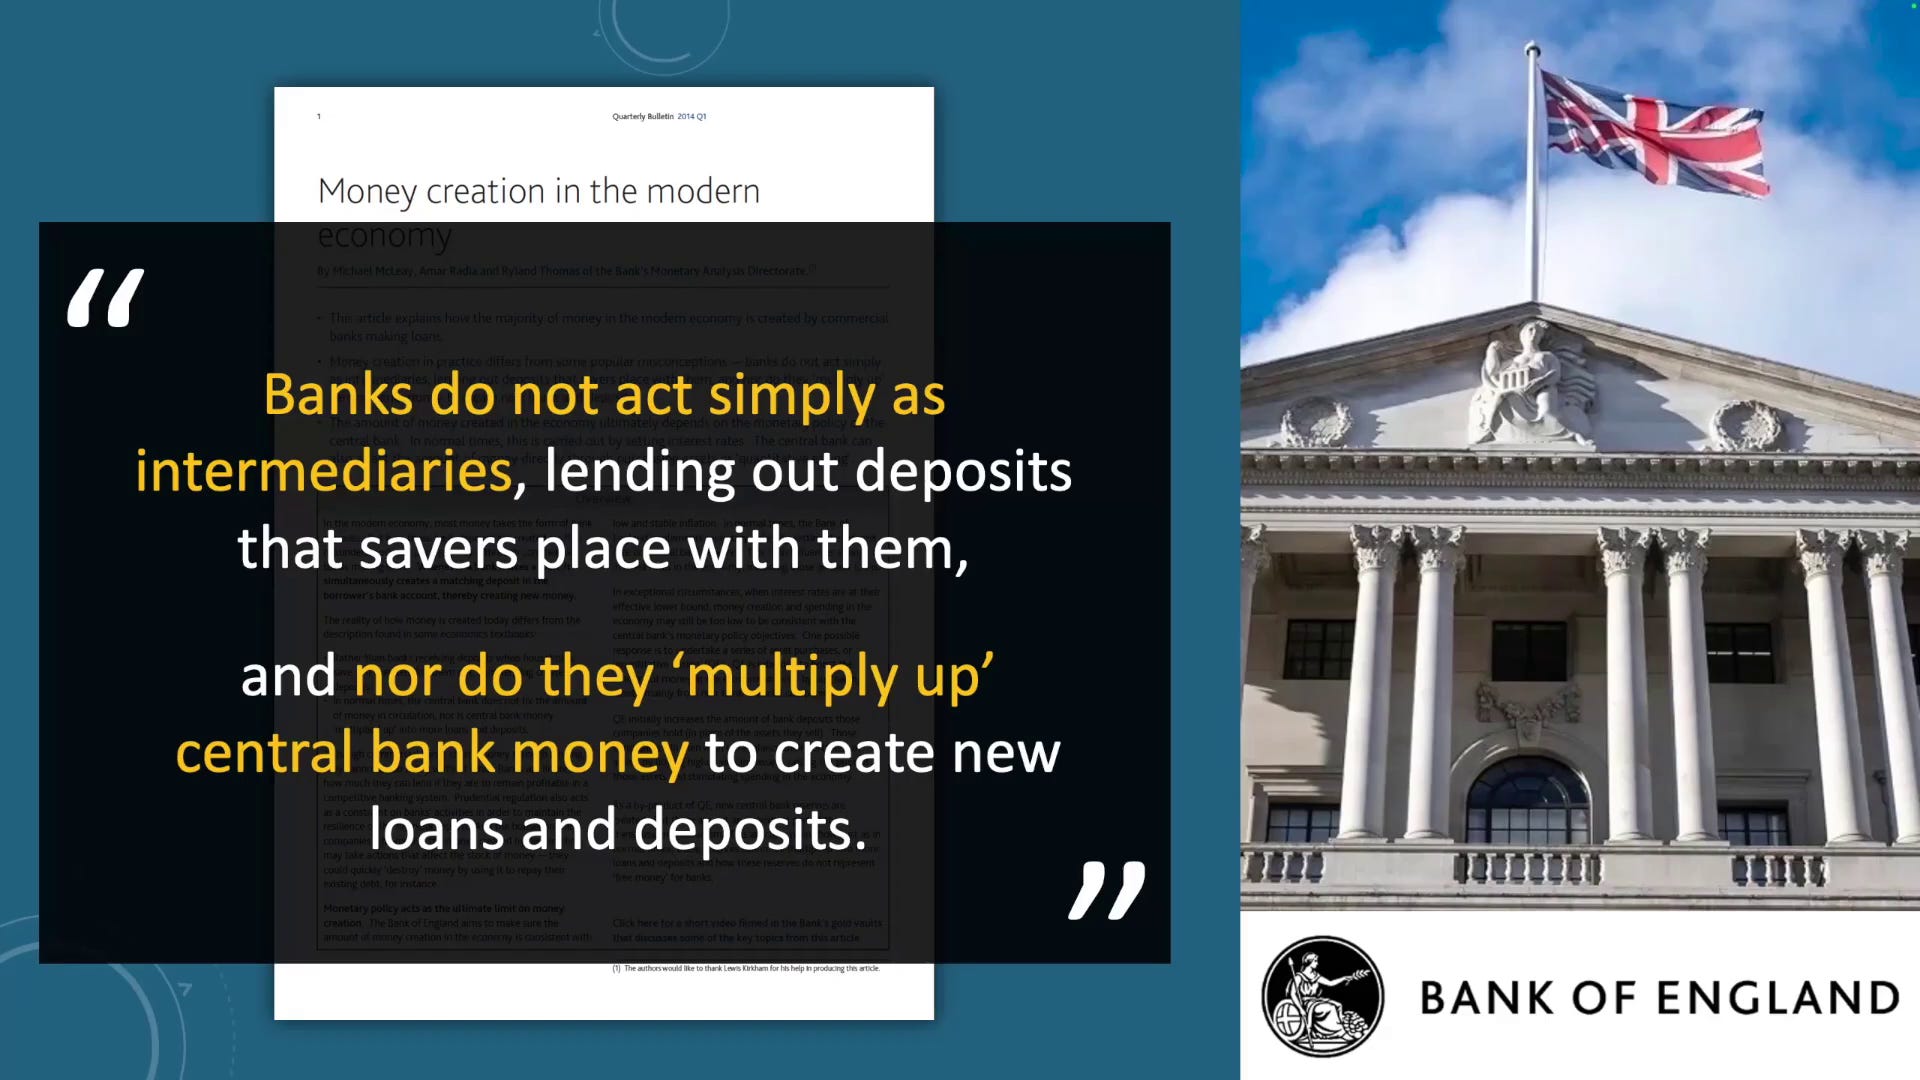
First of all, it says, “Banks do not act simply as intermediaries, lending out deposits that savers place with them, and nor do they ‘multiply up’ central bank reserves to create new loans and deposits.”
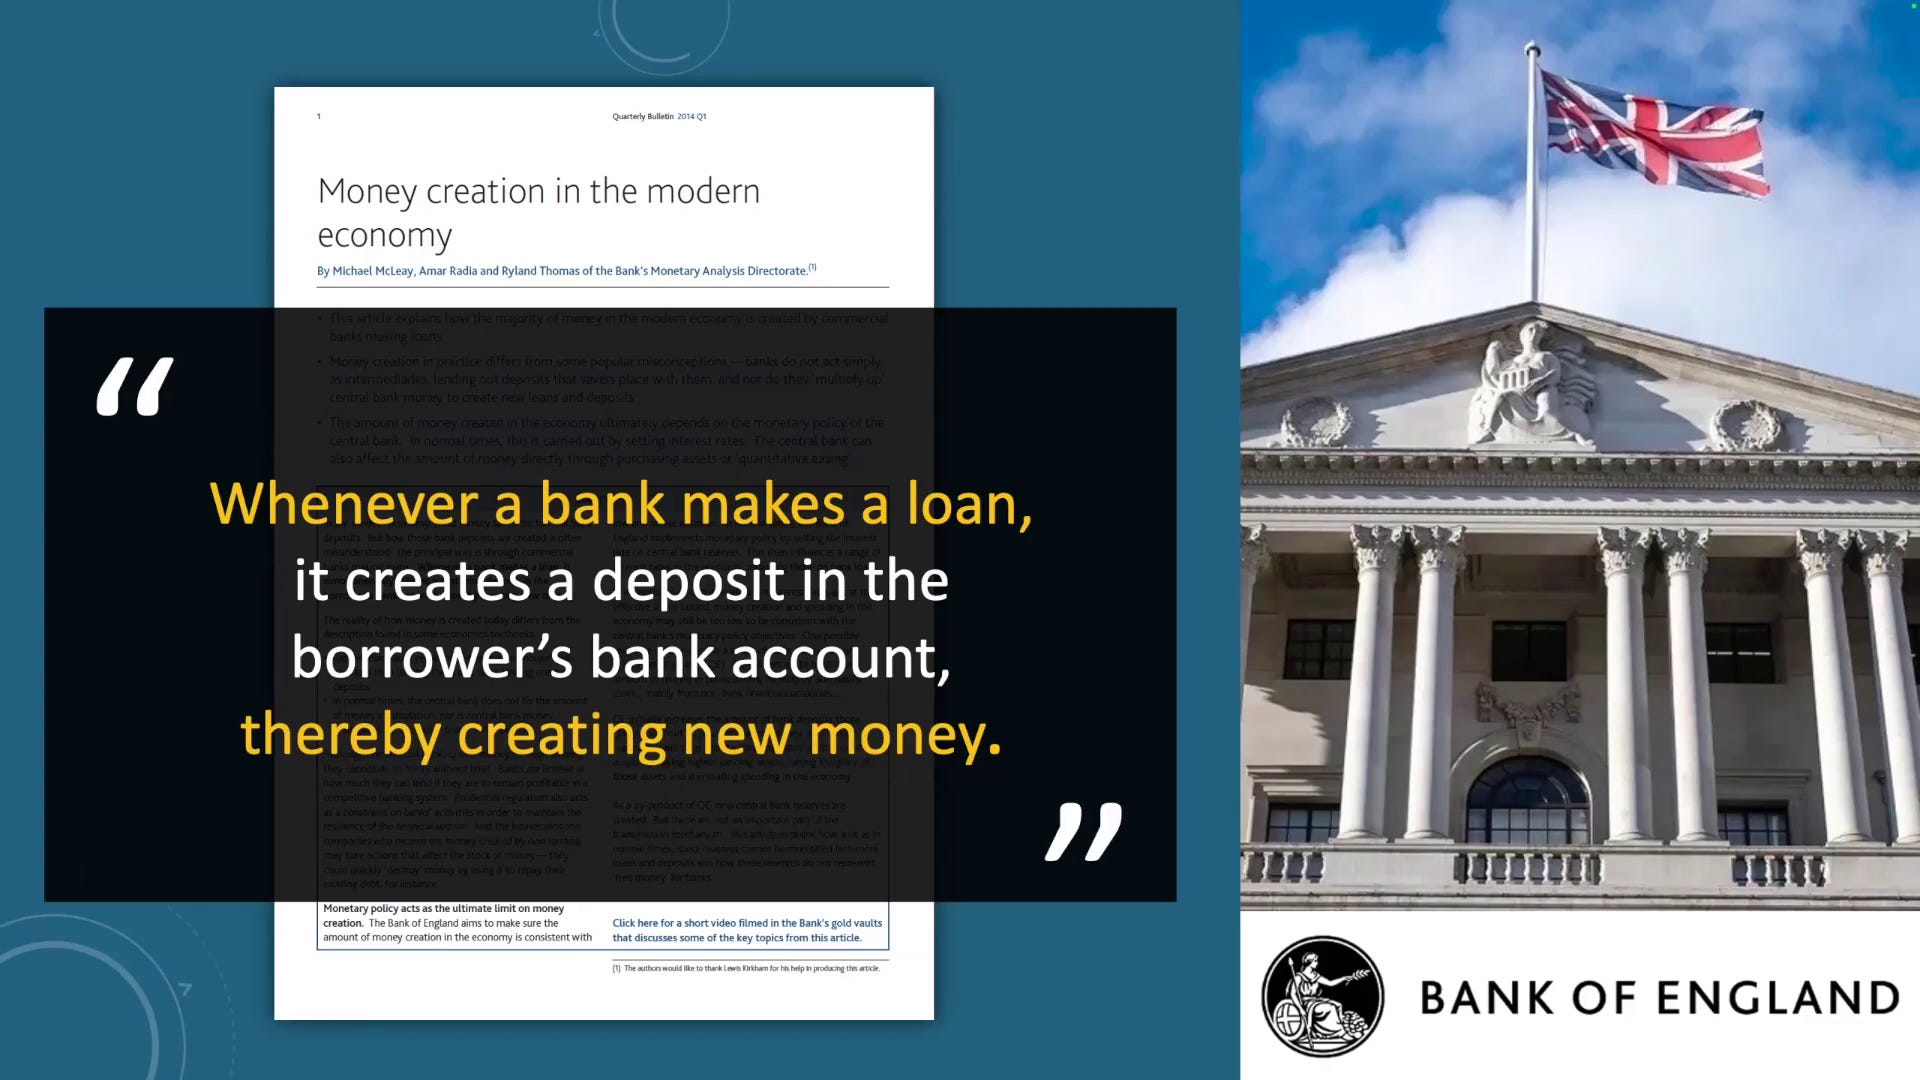
So those two stories that we just saw in the conventional or common understanding, it comes out quite clearly and says those two stories are not true. Instead, whenever a bank makes a loan, it creates a deposit in the borrower’s bank account, thereby creating new money.
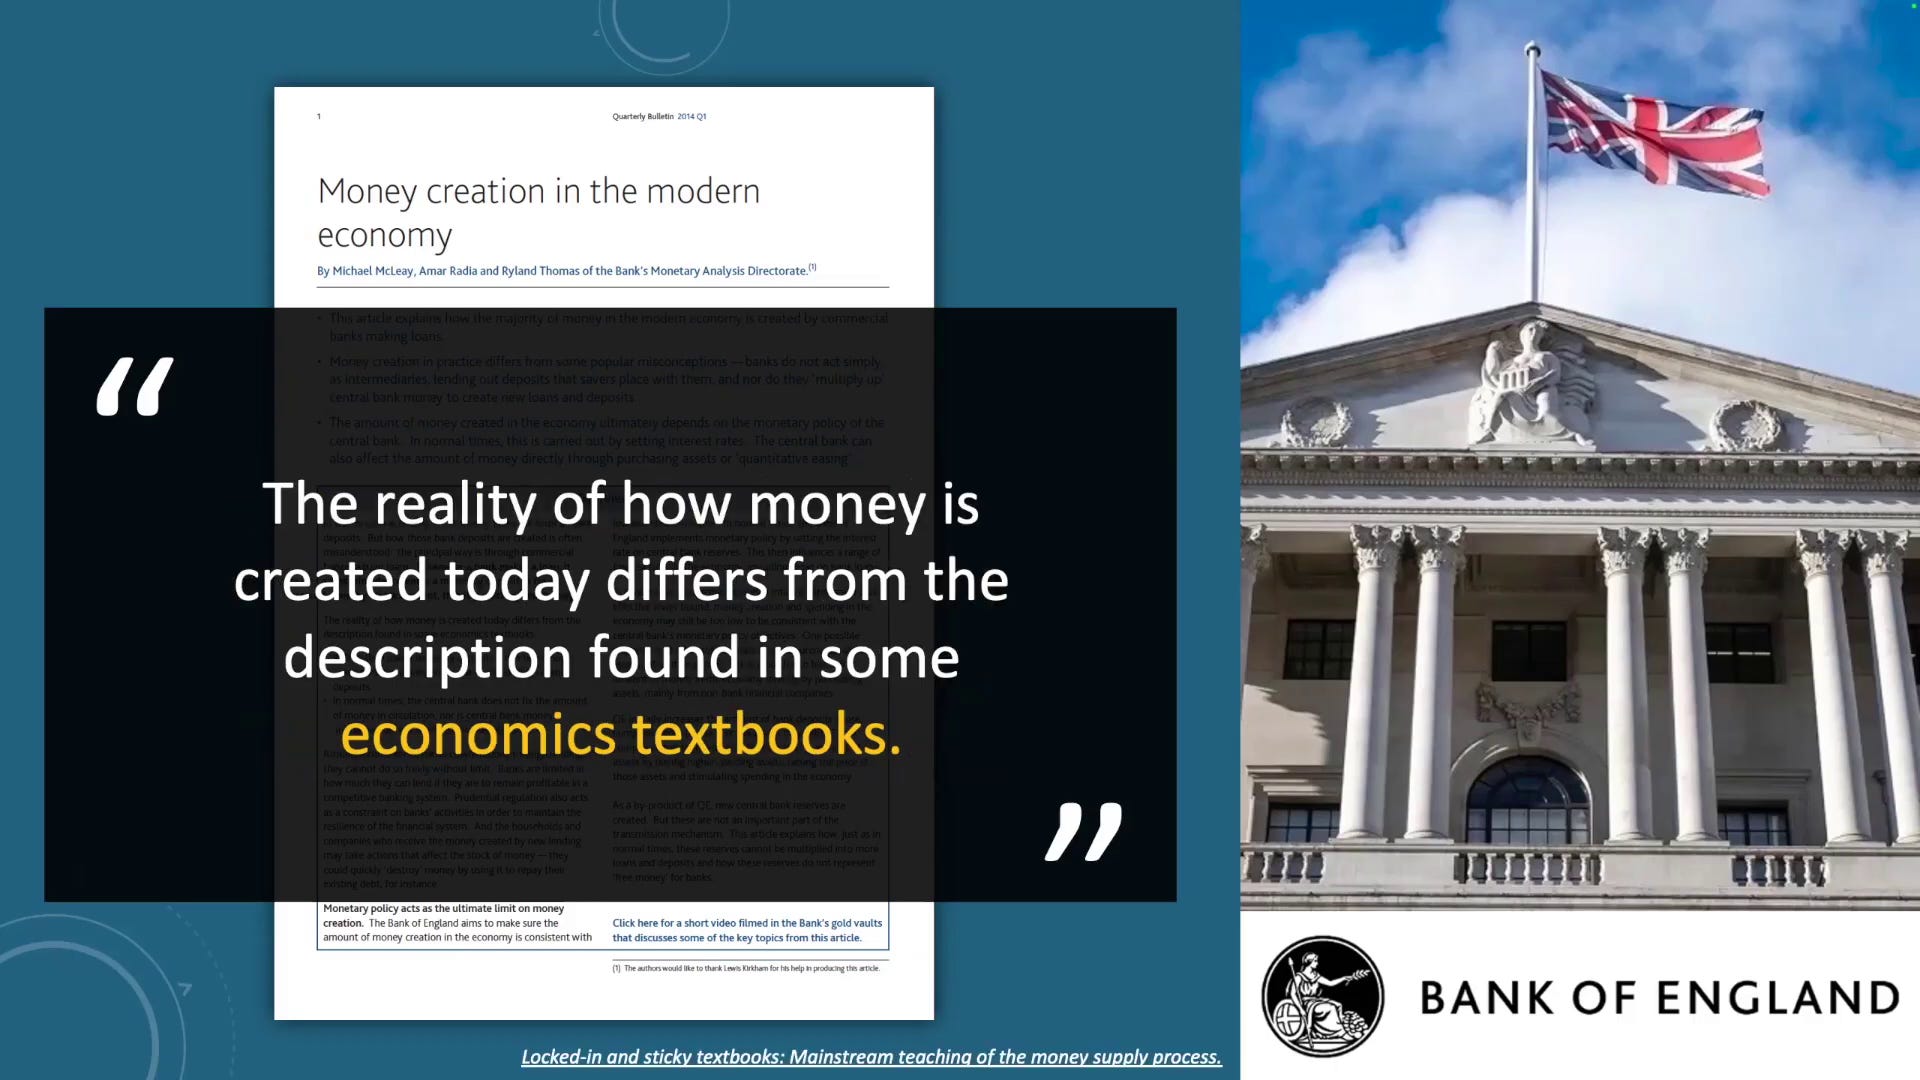
And then it goes on and says, “This reality of how money is created today differs from the description found in some economics textbooks.”
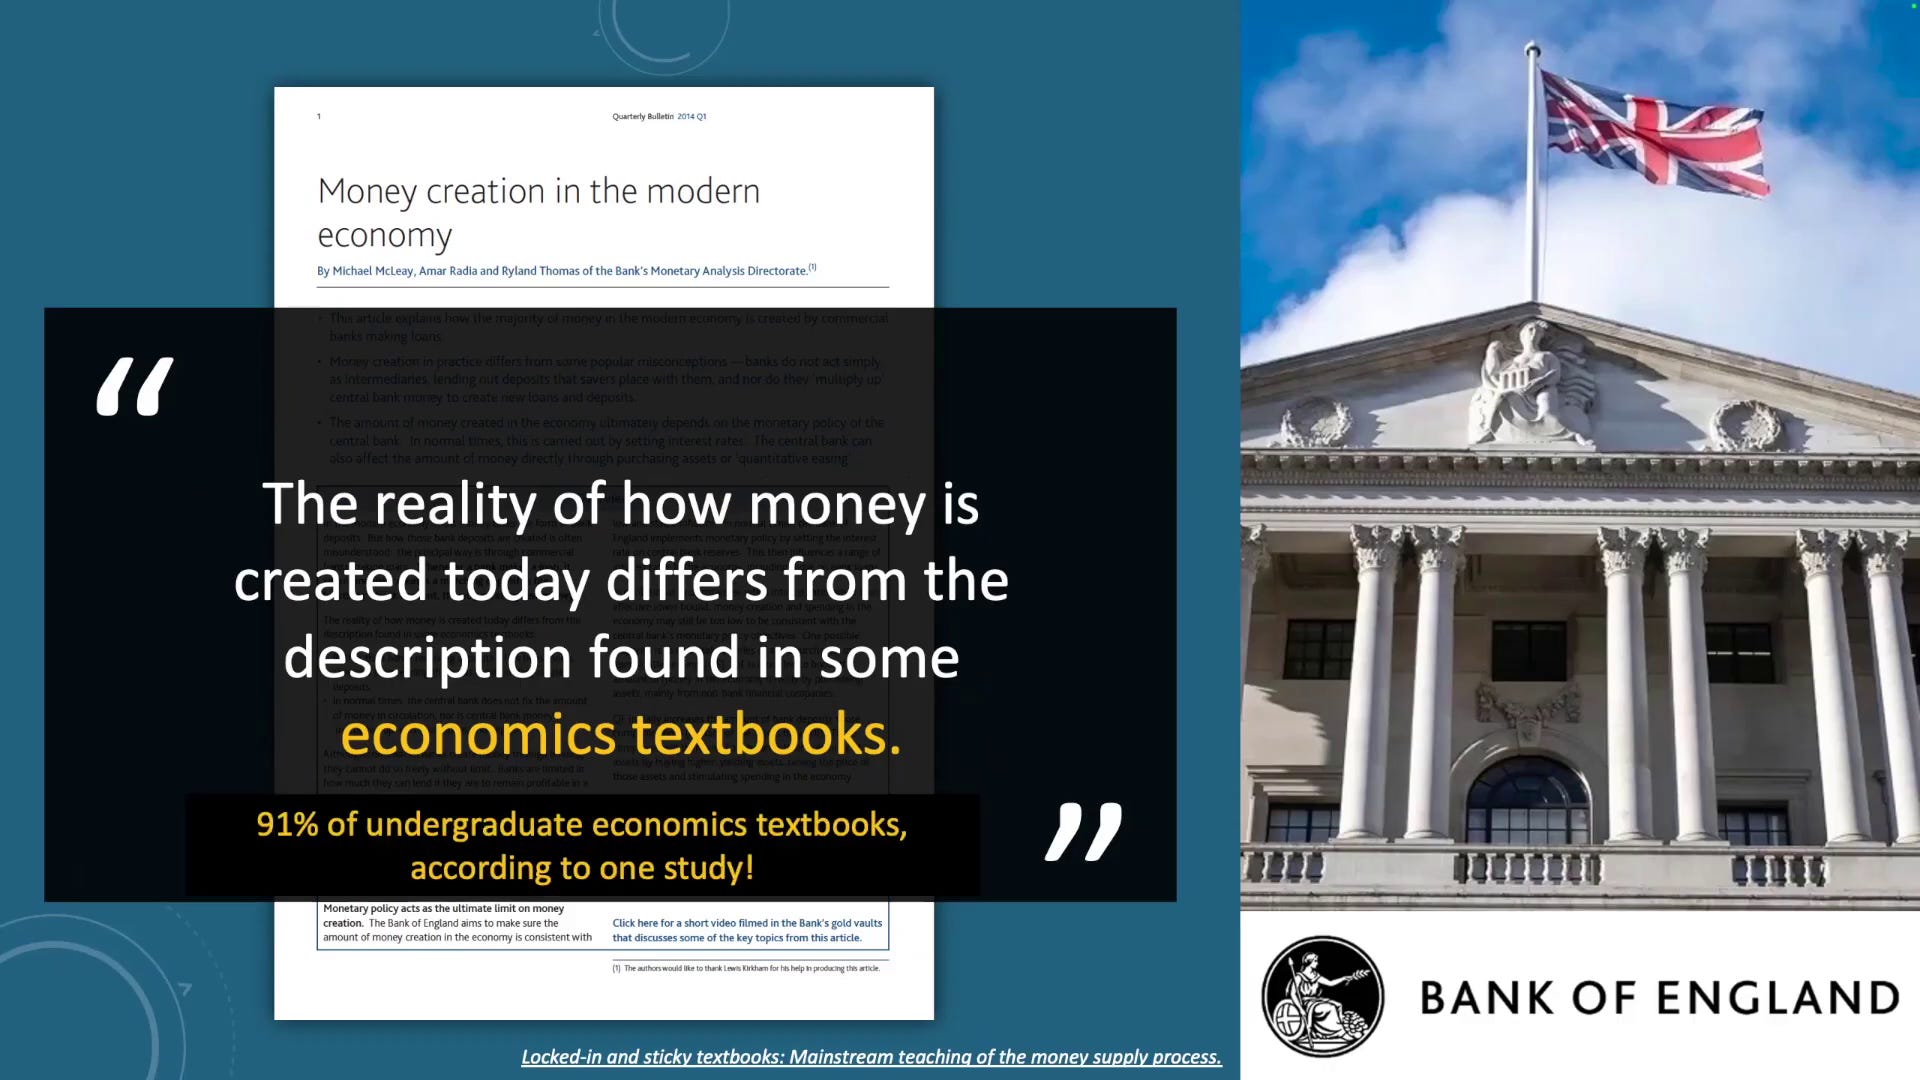
There’s actually a study that was done that found that it was 91% of undergraduate economics textbooks, presented a misleading or incorrect story about how money is created. That was done a few years ago, but I’ve looked at the most recent economics textbooks and that is still the case.
Now, I know that that’s a kind of an unbelievable thing to hear that our economic textbooks could be wrong about where money comes from and how banks work. So, I just want to play you a clip from an interview that was conducted during a conference called “The Money View Symposium,” just last year, with Claudio Borio, who was at that time the head of the Monetary and Economics Department for the Bank for International Settlements.
The Bank for International Settlements is known as the central bank for central banks. It’s where the central banks of the world meet up to coordinate what they’re doing. So, Claudio is going to tell you about his experience learning that banking doesn’t work the way that he was taught in his textbooks.
Claudio Borio: “All of the models of banks that we had studied at the university actually abstracted from capital. If I wanted to be a good economist here at an institution that works for central banks, I had to broaden my horizons. So, I worked in financial markets, I worked in banking, and worked in regulation and supervision. I even taught myself accounting. Then I worked a lot on payments and settlement systems. I worked on monetary policy implementation. And there I did learn that everything that I had learned at the university was wrong, that it had been no resemblance to what was going on in the real world. And that was a major eye opener.”
So where does bank money come from in reality?
Well, I’m going to go into the accounting for you, and again, don’t worry if you don’t catch the details. I think you will get the broad strokes. If you want the details, there’s an excellent and approachable set of resources here. One of them is a “Banking 101” video series, animated and produced by Positive Money – a monetary reform organization based in the UK. And then the other one is a book titled “Where Does Money Come From?” produced by the New Economics Foundation, also in the UK.
The important thing as we go forward here is just remember that it’s not actually that complicated. As John Kenneth Galbraith, a famous economist and the author of a book “Money: Whence It Came, Where It Went” writes, “The process by which banks create money is so simple that the mind is repelled.” And I think that I’ve seen that many people expect it to be more complicated and that causes a problem.
So let me first give it to you from the human perspective, and then we’ll look at the accounting.
So step one: A borrower signs a loan contract at a bank.
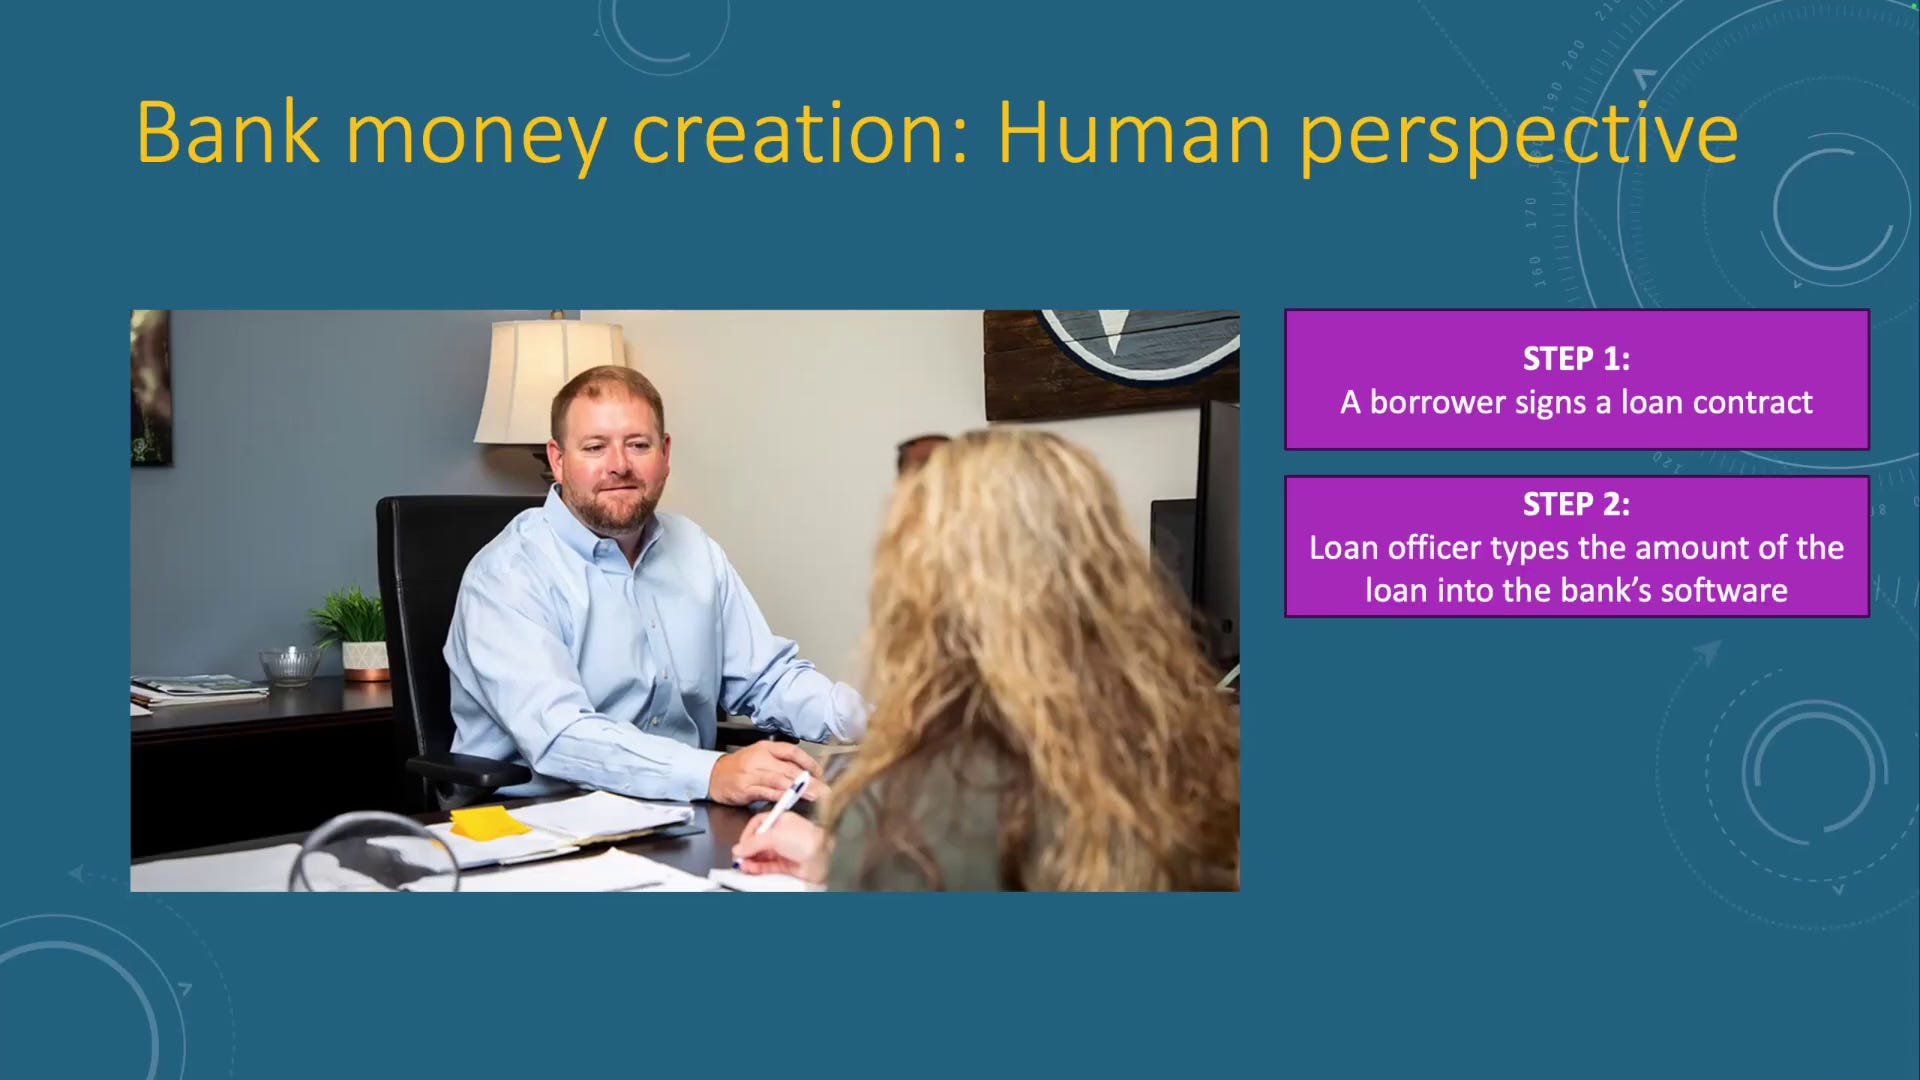
Step two: The loan officer types the amount of the loan into the bank’s software – accounting software.
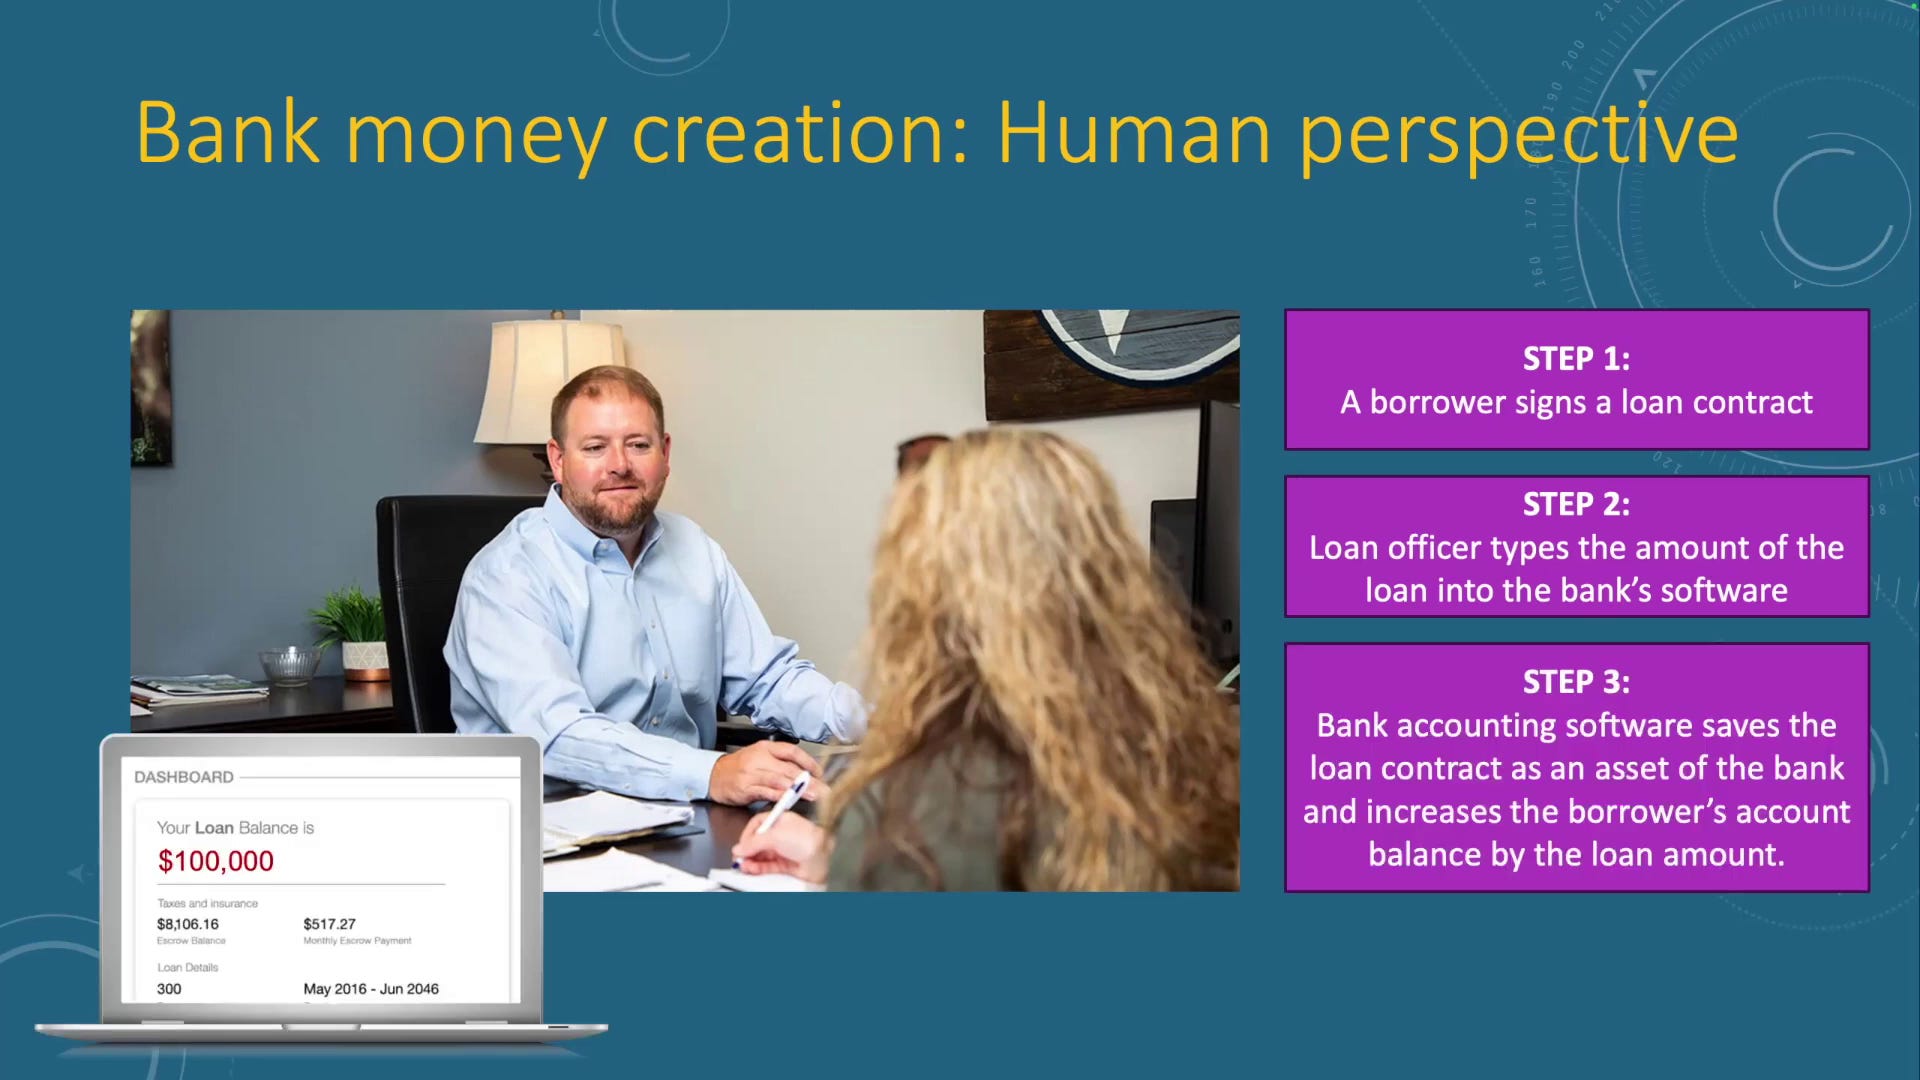
And the bank accounting software saves the loan contract as an asset of the bank and increases the borrower’s account balance by the loan amount.
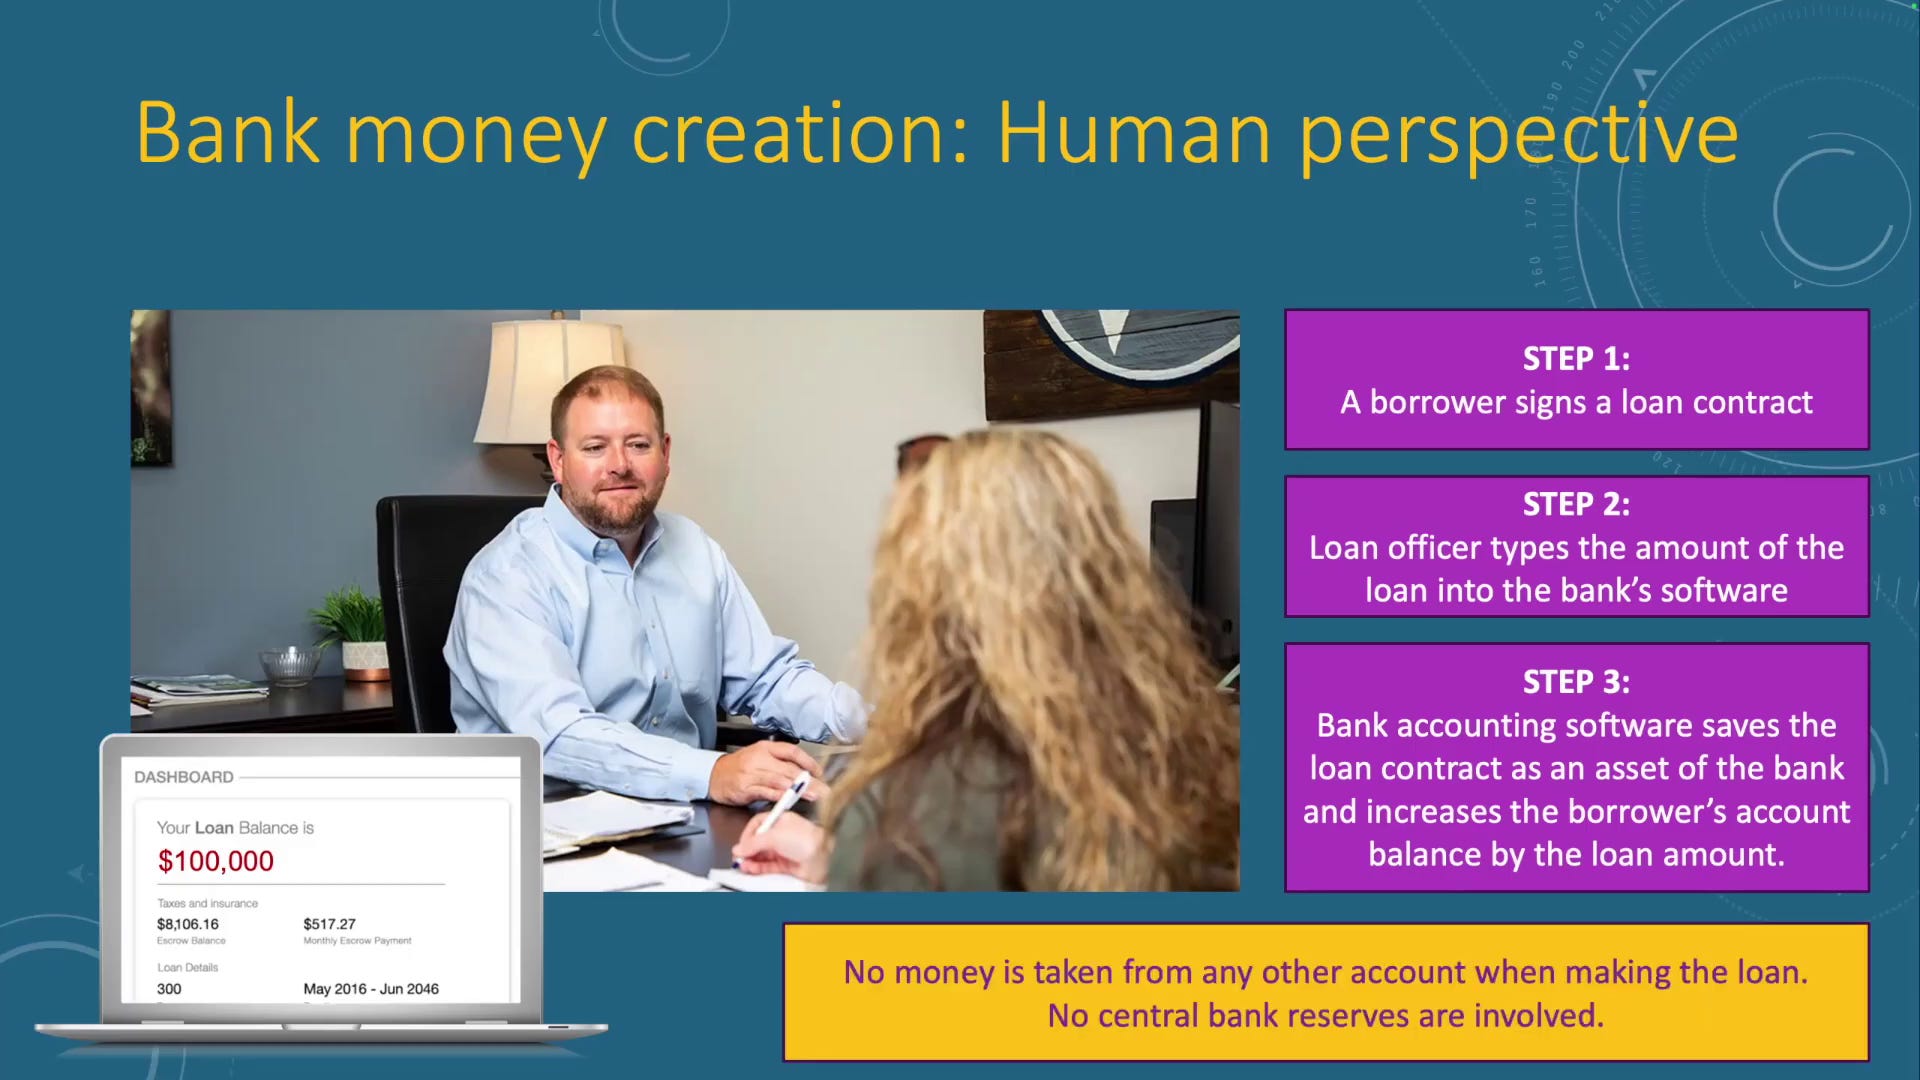
No money is taken from any other account when making the loan, and no central bank reserves are touched.
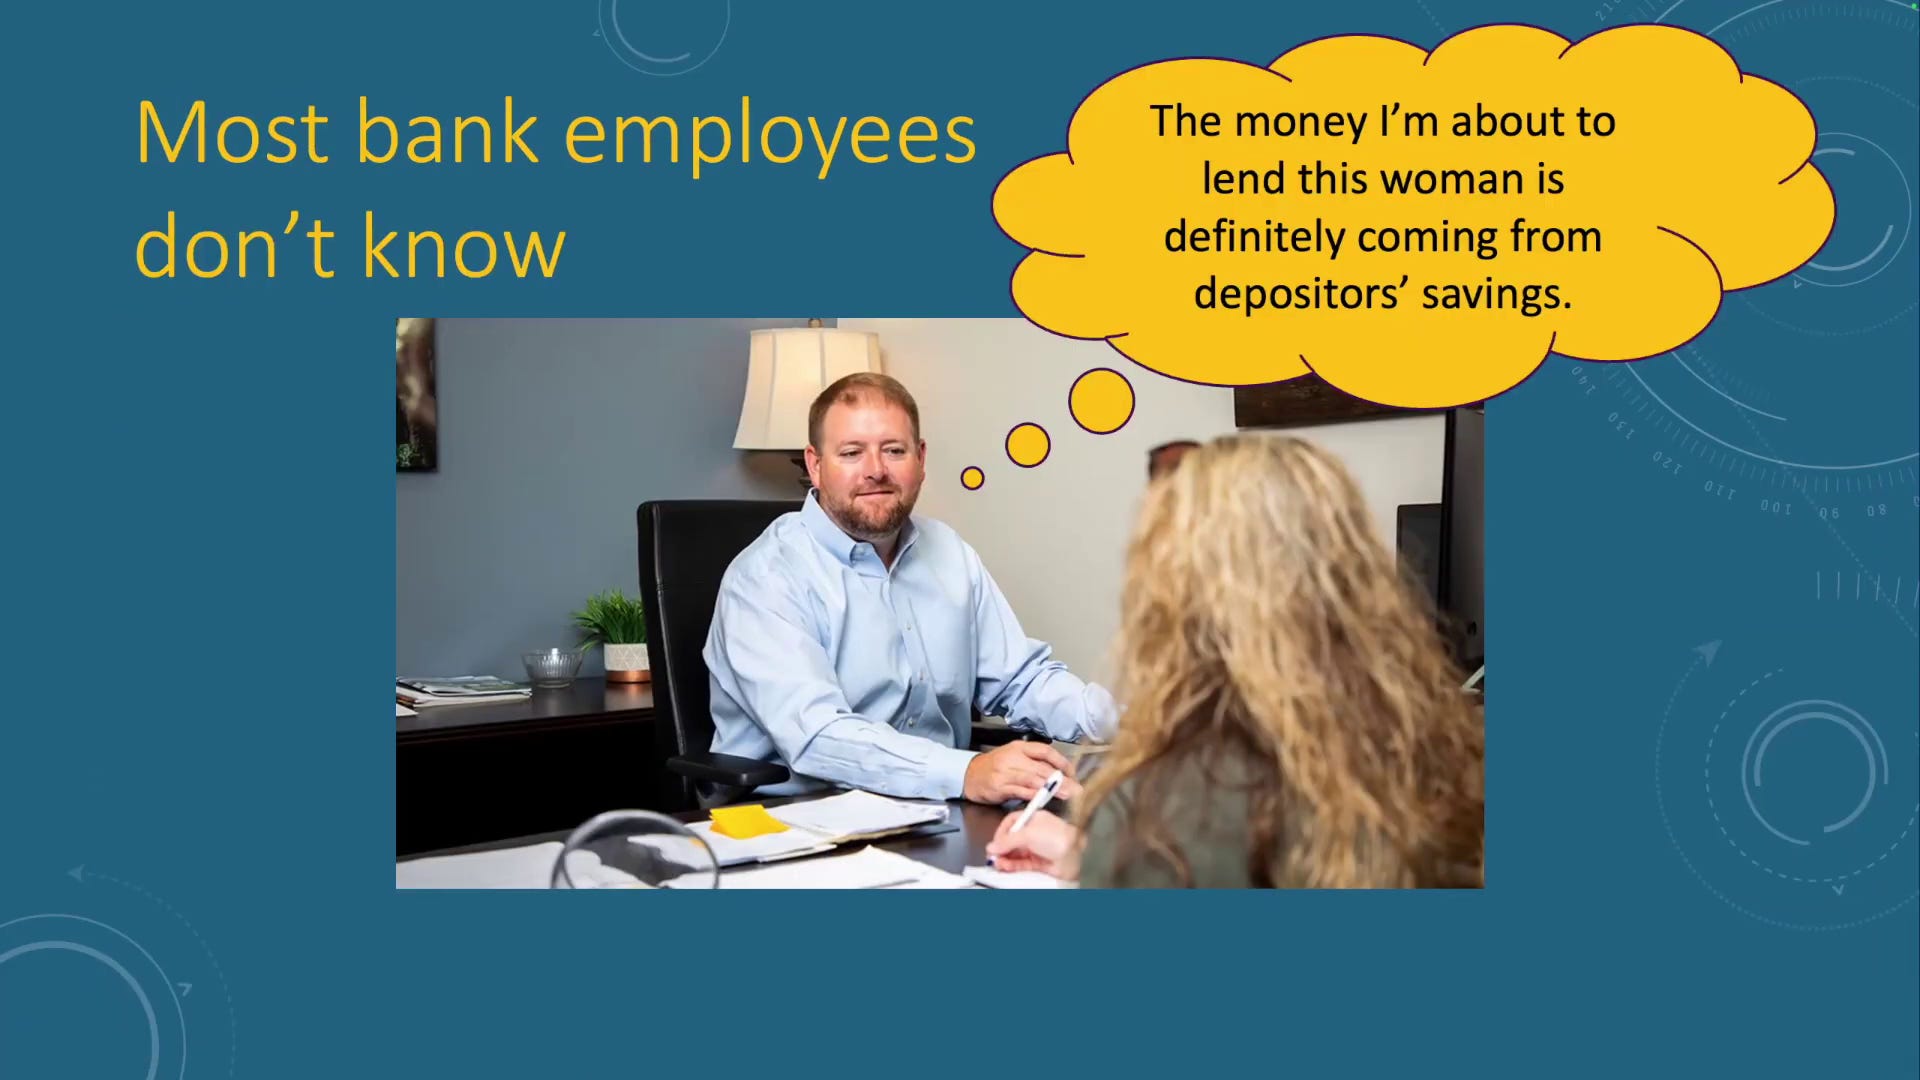
Now, we know from research as well that most bank employees don’t know this. Most of them think that they’re lending out depositors’ savings.
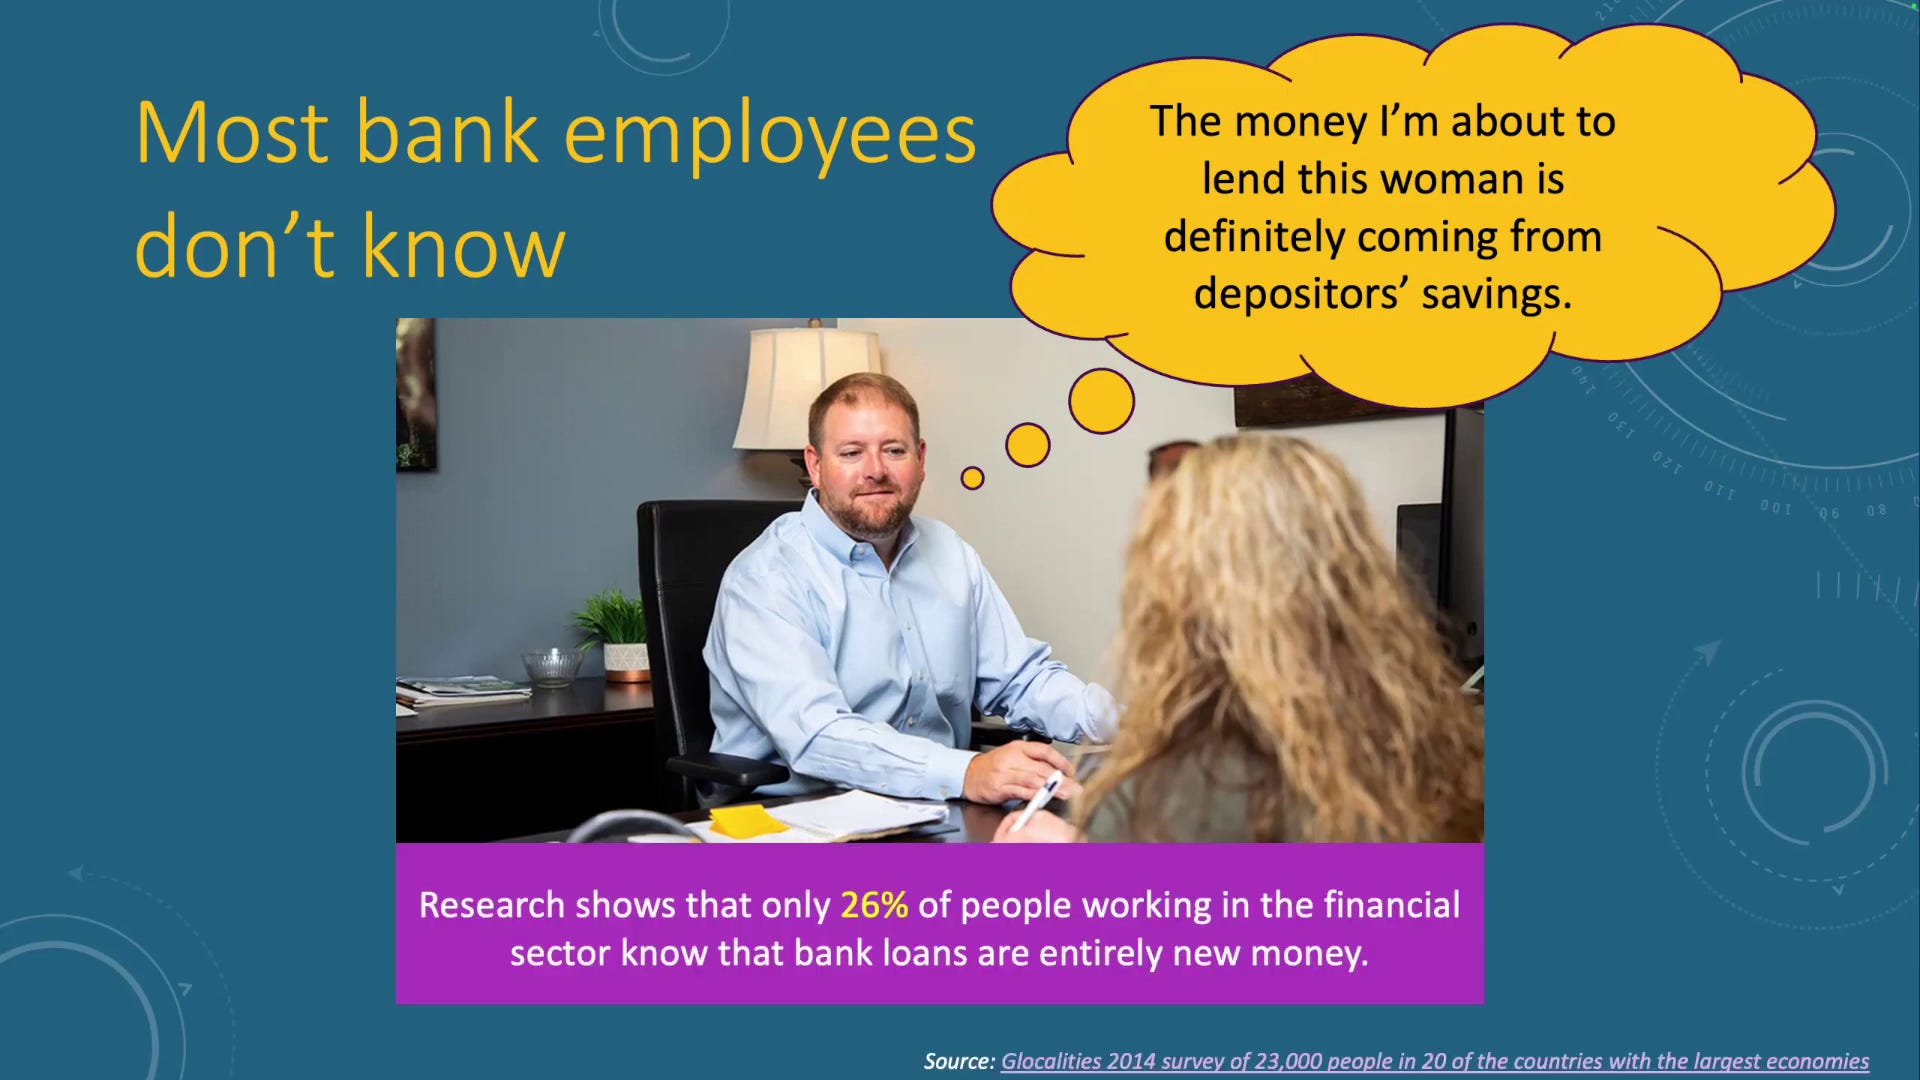
And there’s actually a research study that showed it was only 26% of the people working in the financial sector that know that bank loans are entirely new money. In fact, I’ve had a friend who is a former CEO of a small bank, tell me, “Sam, if my bank was creating money out of nothing, I would have known.” So this is just hidden in the accounting system and within this story about where banks are lending out depositors’ savings.
So, let’s get the accurate story.
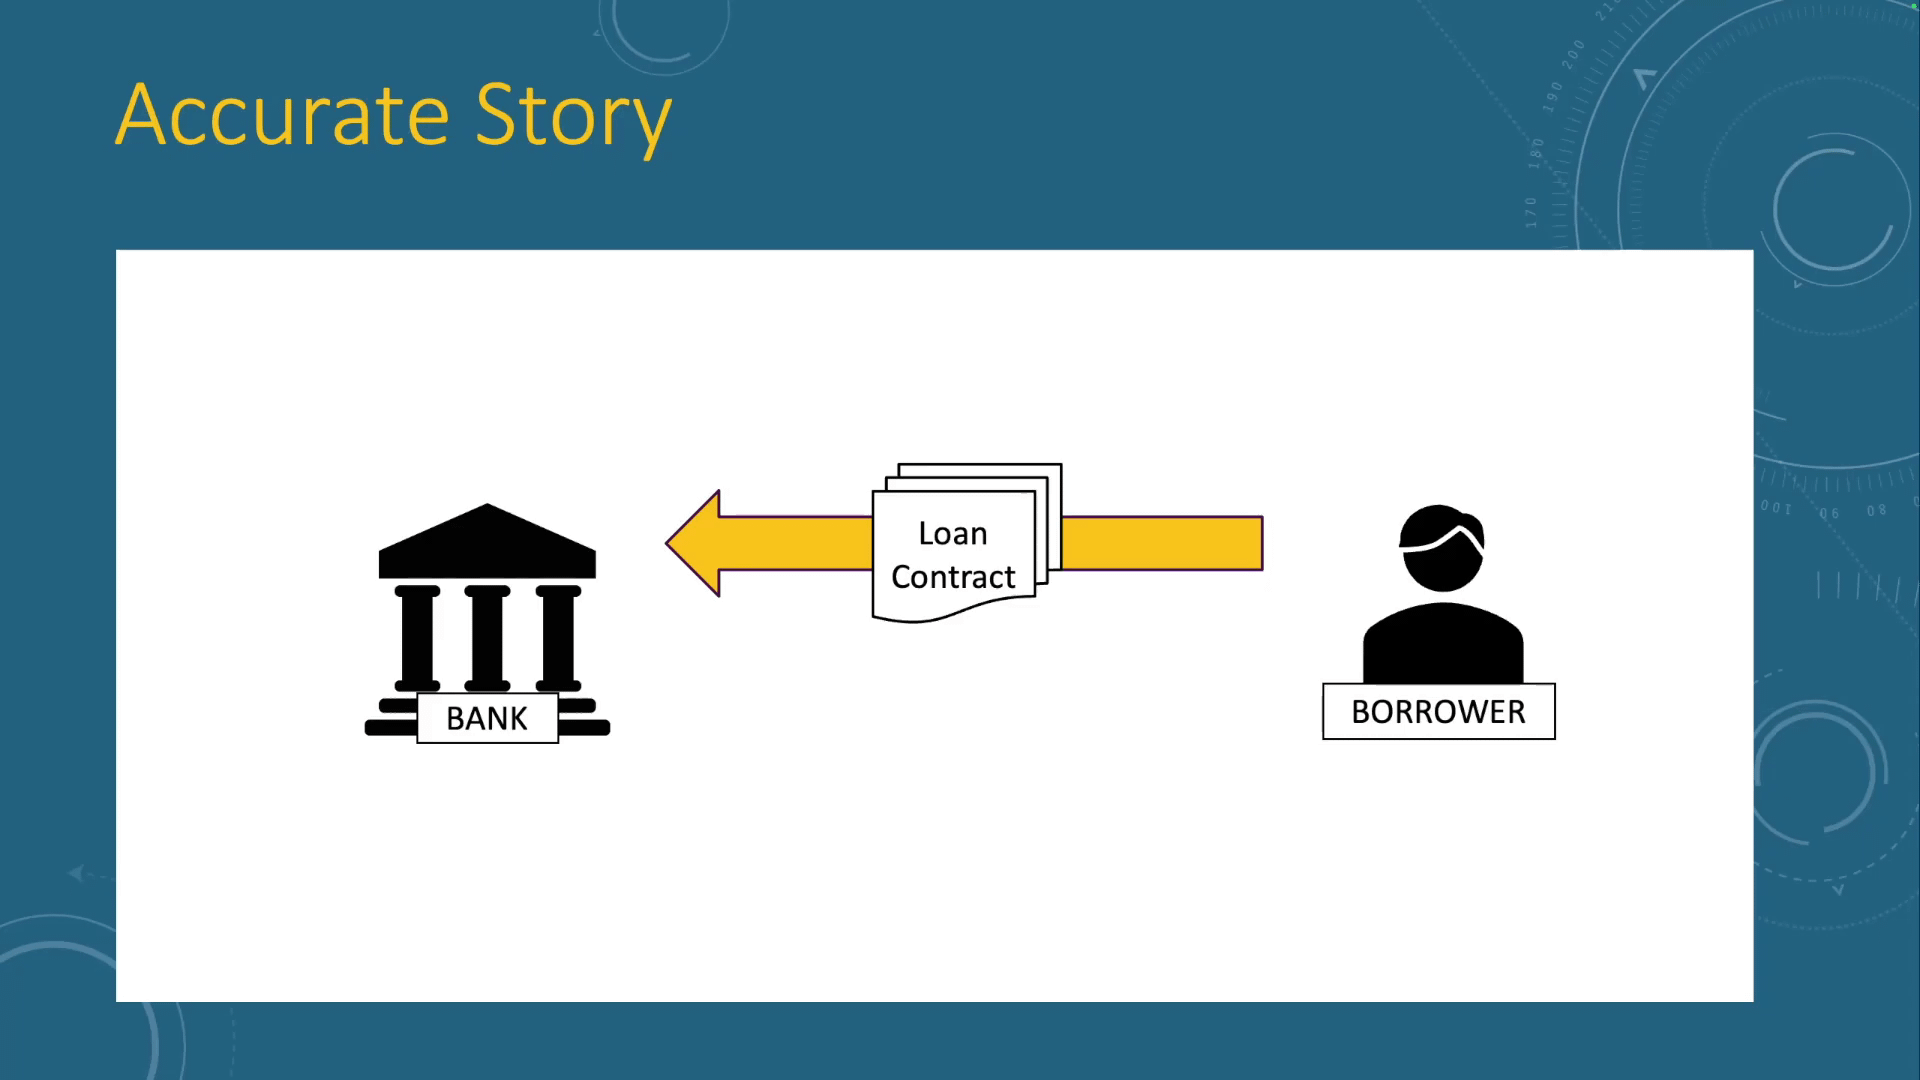
A bank has a borrower sign the loan contract and that is received by the bank as an asset for the bank. It’s an asset because it’s going to earn interest for the bank. The money is going to come back and it’s going to earn interest. So that’s an asset for the bank.
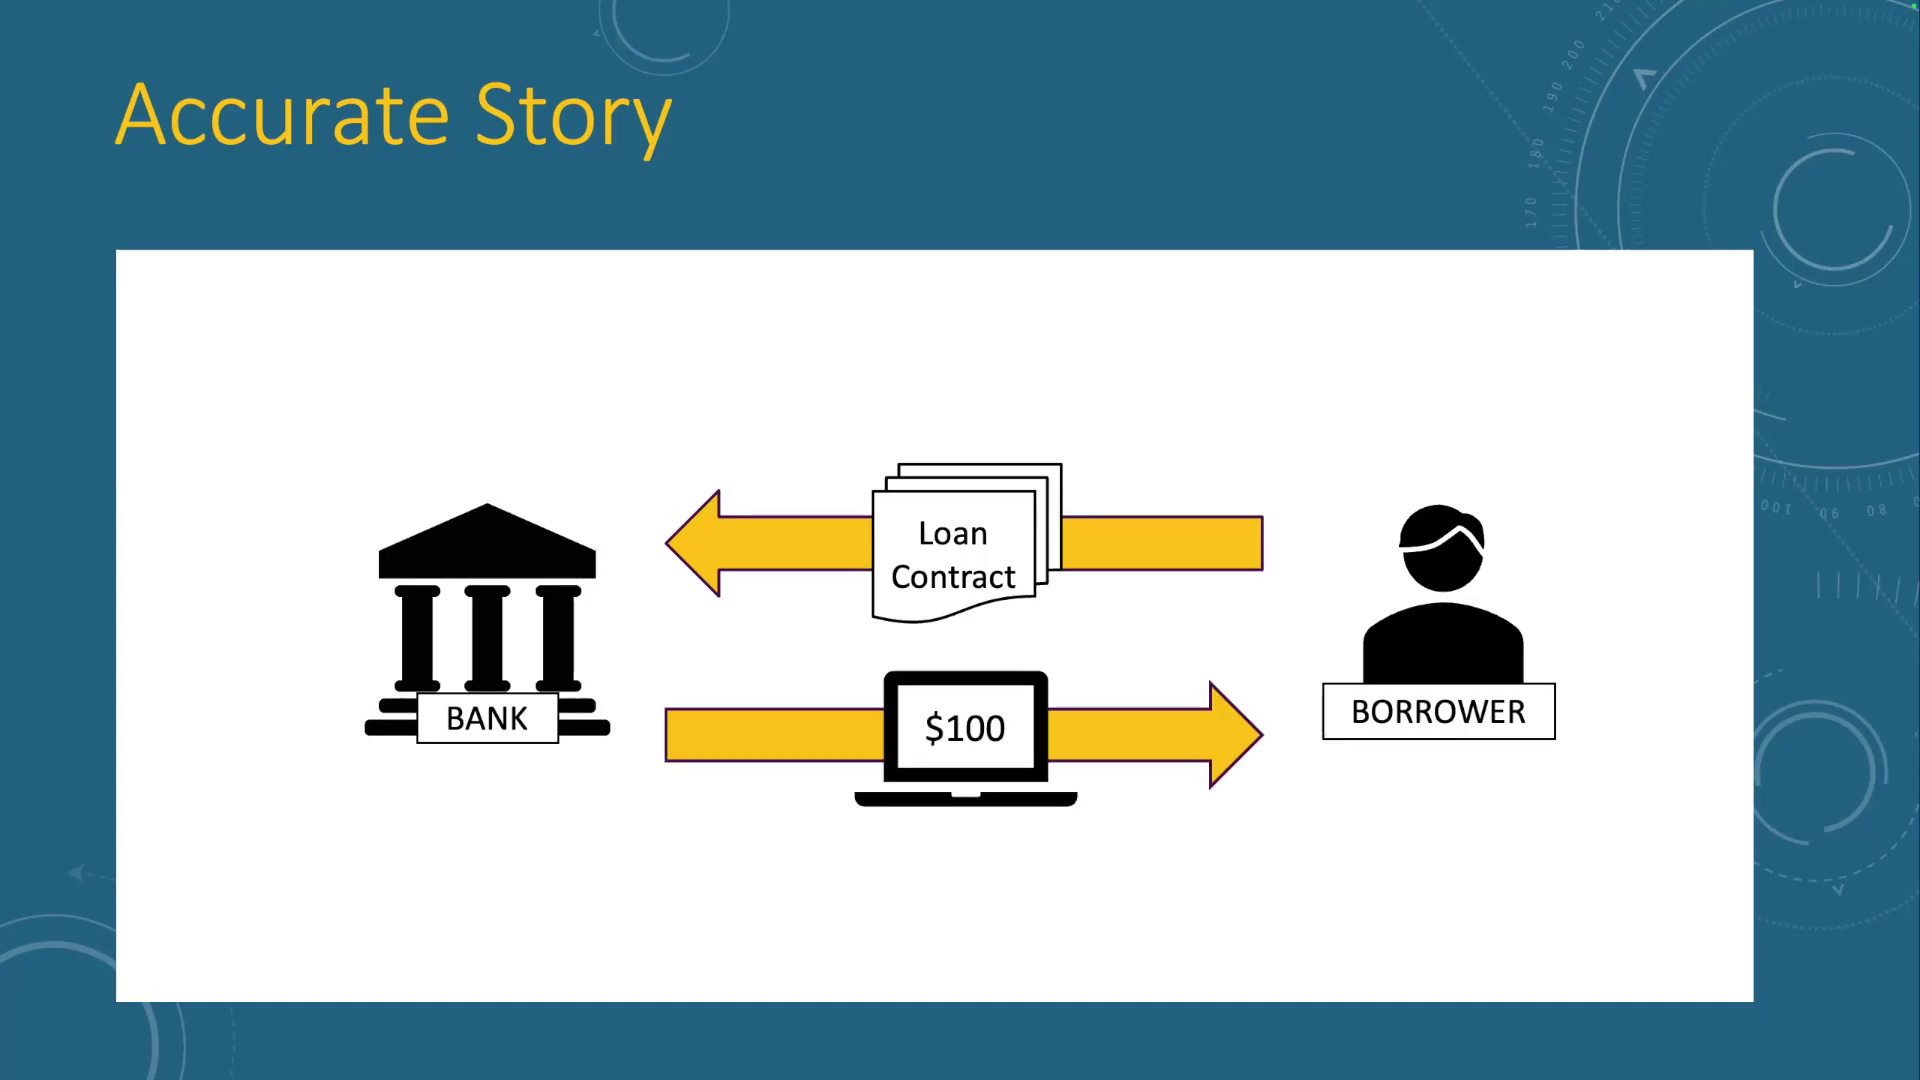
And then the bank turns around and types into the borrower’s account the amount of the loan. It’s that simple. So, this is a much simpler picture than the picture that you saw earlier. It’s very, very simple.
And if you have any doubts about how that works, just know that there was an Oxford-trained banking scholar, we’ll hear from him later, who said, “You know, we should have conclusive evidence of which of these stories is right. And the conclusive evidence is going to come from the accounting software that’s used by banks.” Thousands of banks, they use the same accounting software. So, he went and looked at it and wrote a paper titled, “A Lost Century in Economics” that settles the discussion.
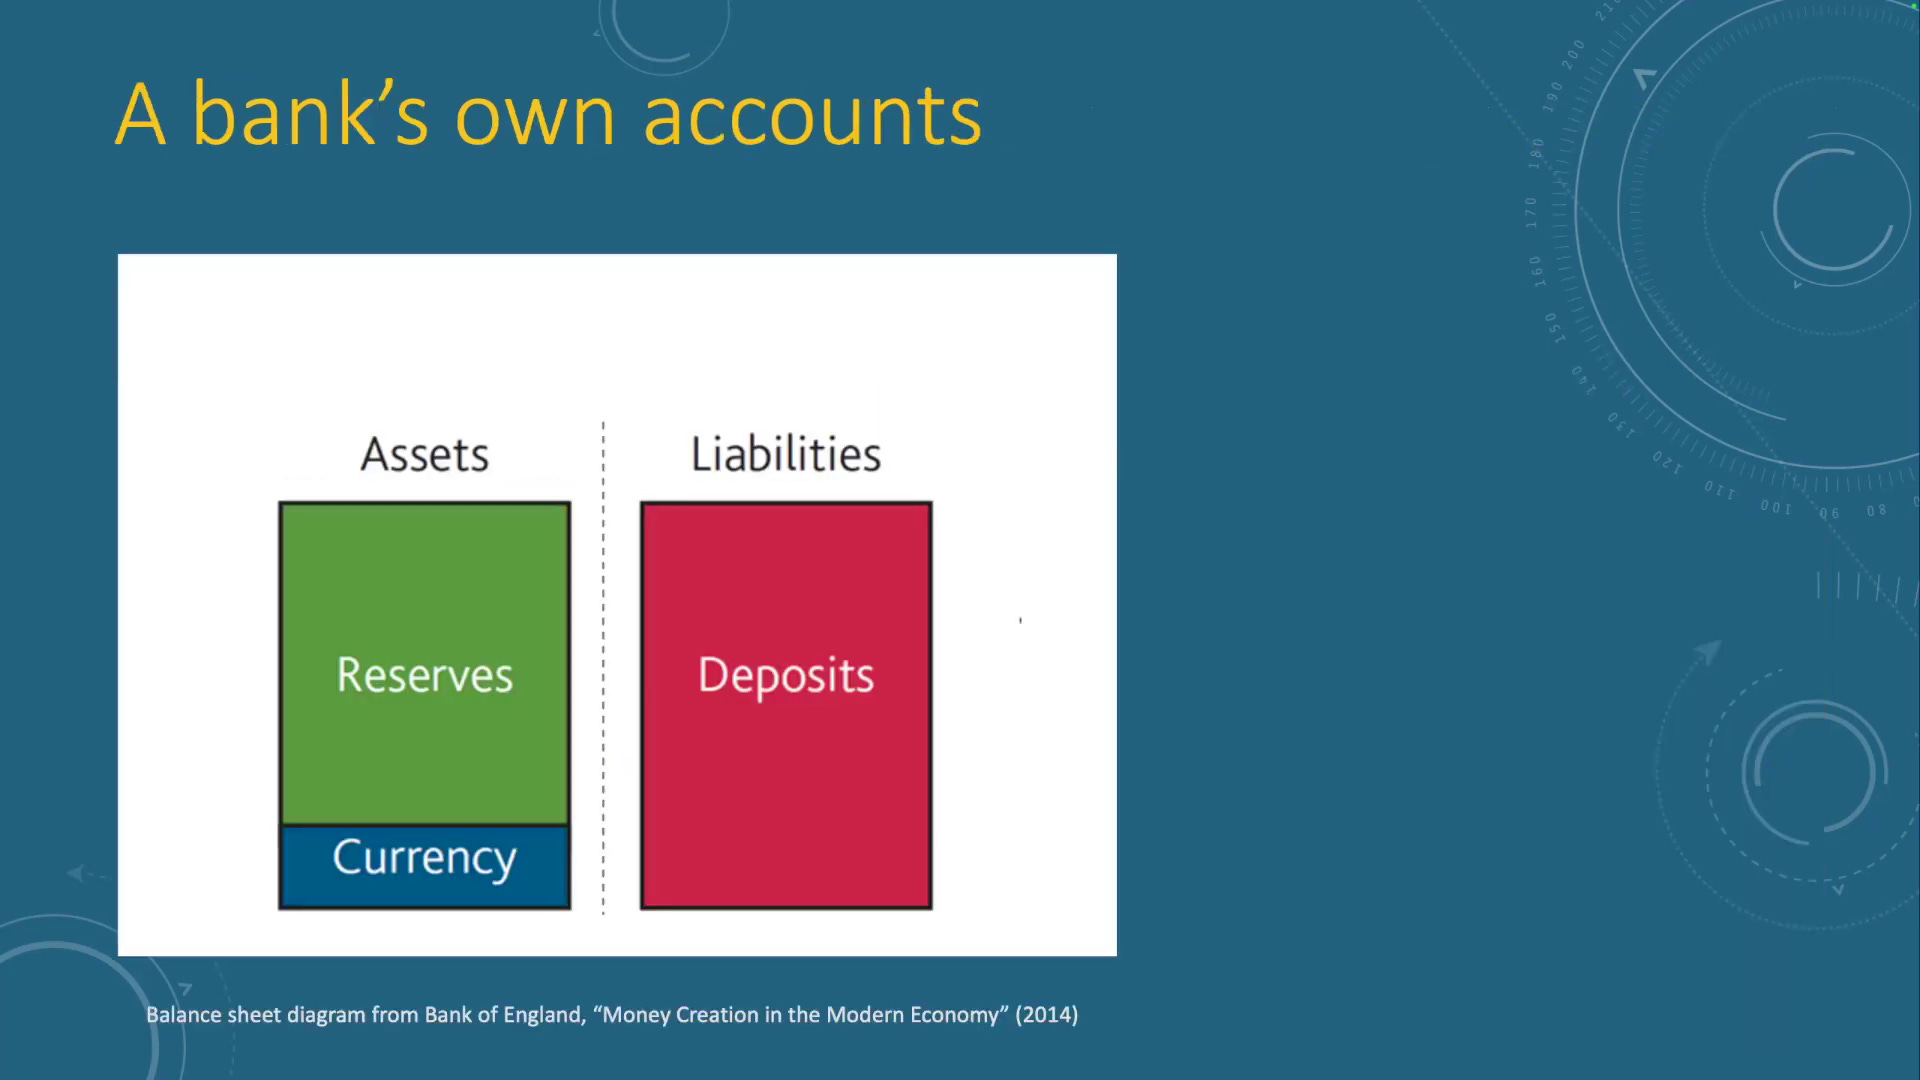
So now, let’s look at it from the accounting perspective. And this is really the only important thing that you need to understand in order to understand all of this is that, in accounting, a bank has a balance sheet. And on the one side, it has its assets, which are usually the loan contracts and things that are going to pay it interest. So, those are an asset for the bank. It’s going to collect the money and the interest. And so, that’s an asset for the bank.
On the other side of it is the balance sheet. It has customer deposits, and the customer deposits are liabilities of the bank. And these two things, the assets and liabilities, always must match.
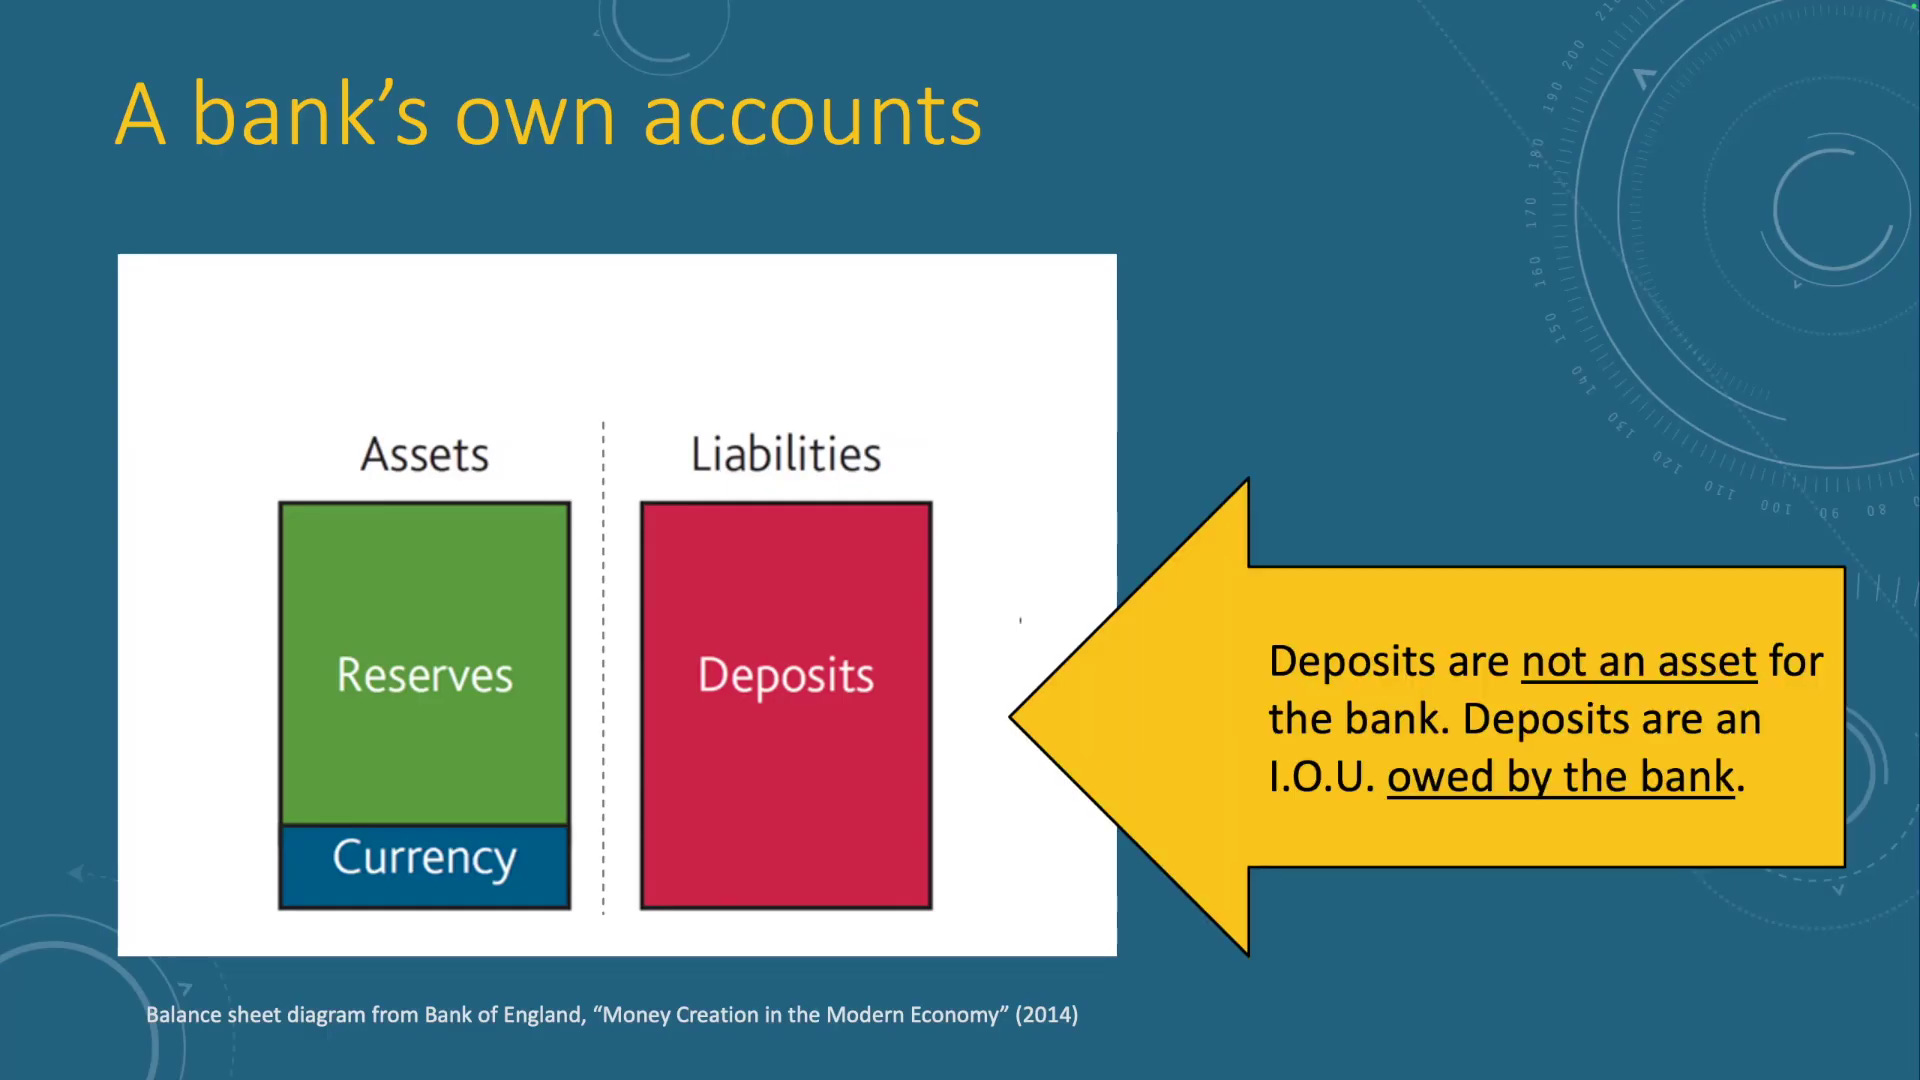
Now what’s important to notice here is, as I said, the deposits are not an asset for the bank. They are in fact an IOU. It’s the bank saying in your bank account – when you look in your bank account – it’s the bank saying, “I owe you that much money, and if you ever want to pay it to somebody else, I will provide it.” So that’s why deposits aren’t something that the bank can lend out. They’re not an asset that the bank has to lend out. Instead, they are a liability.
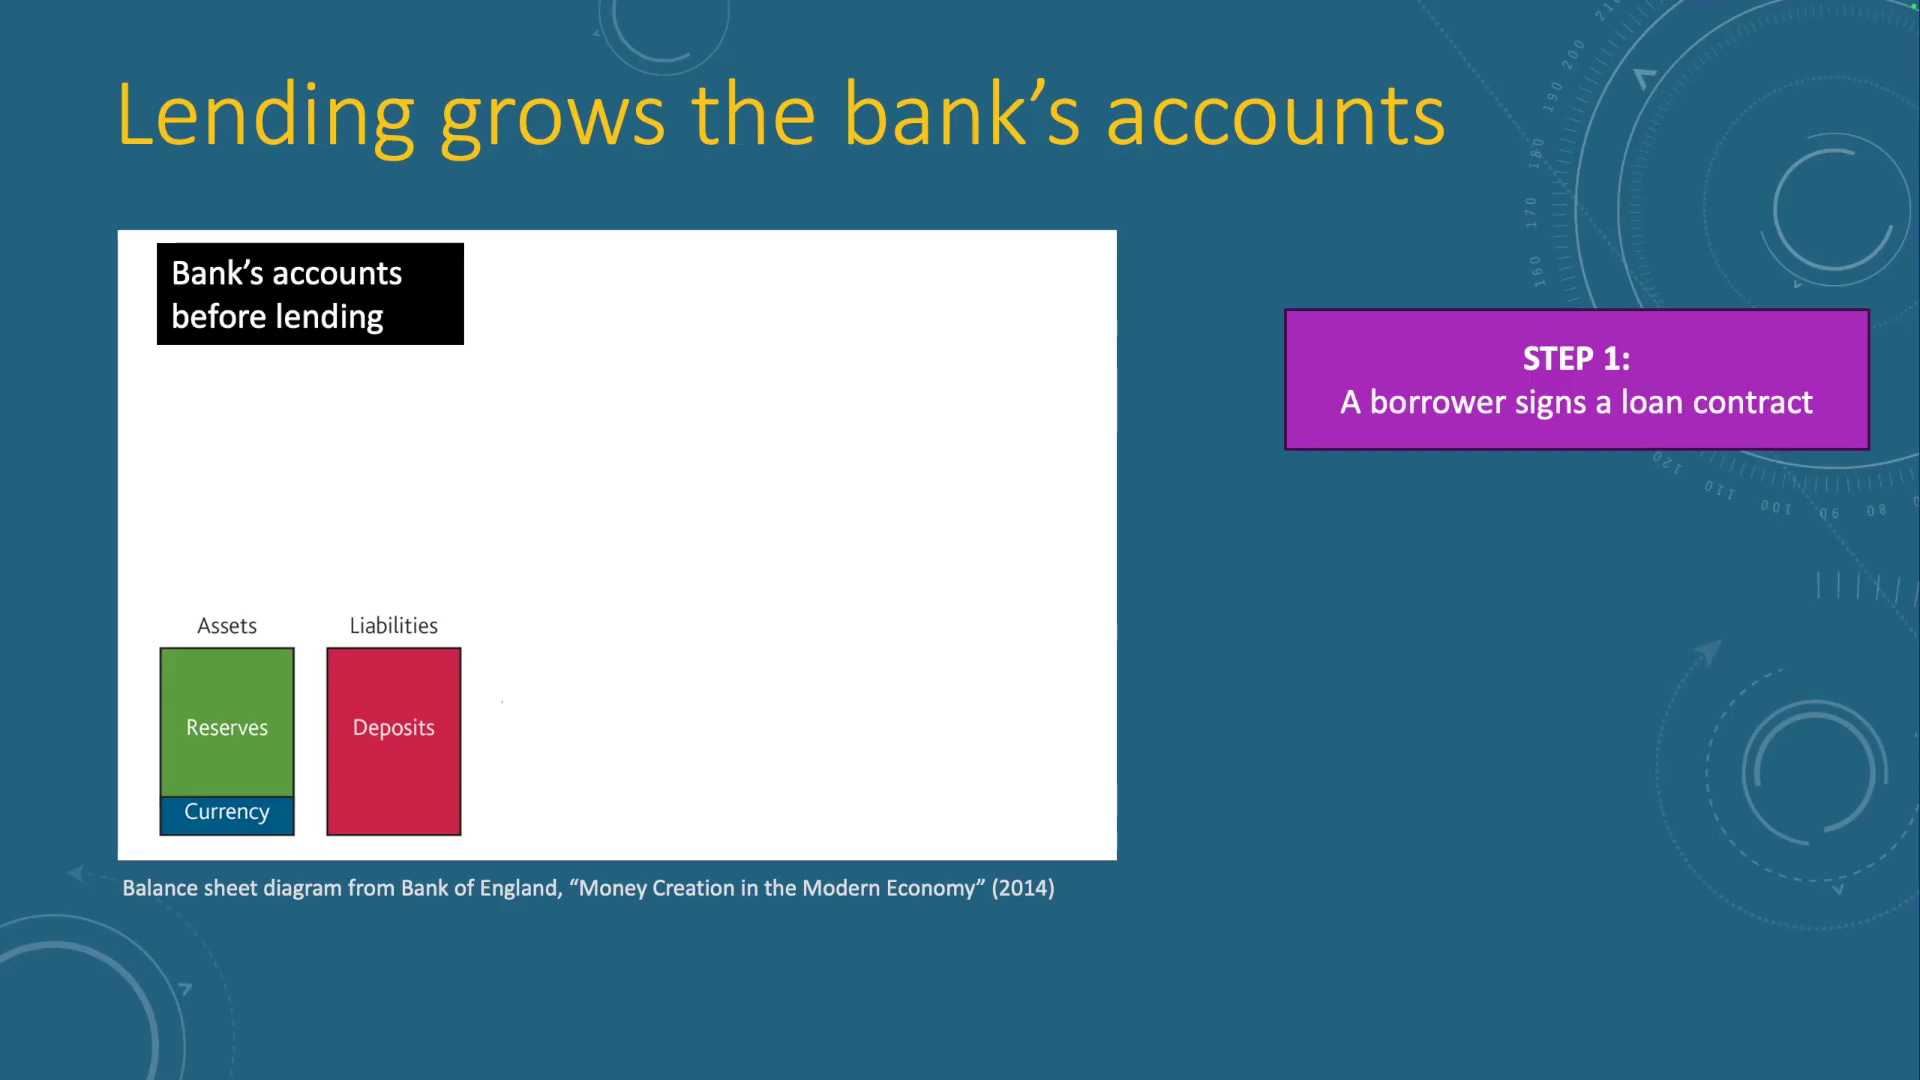
Now, what happens when a bank makes a loan is that – and these pictures here are taken straight from the Bank of England’s paper – so, if you go look at the “Money Creation in the Modern Economy,” this is how they’re presenting the accounting. So, before the loan is made, the accounts are balanced in this way.
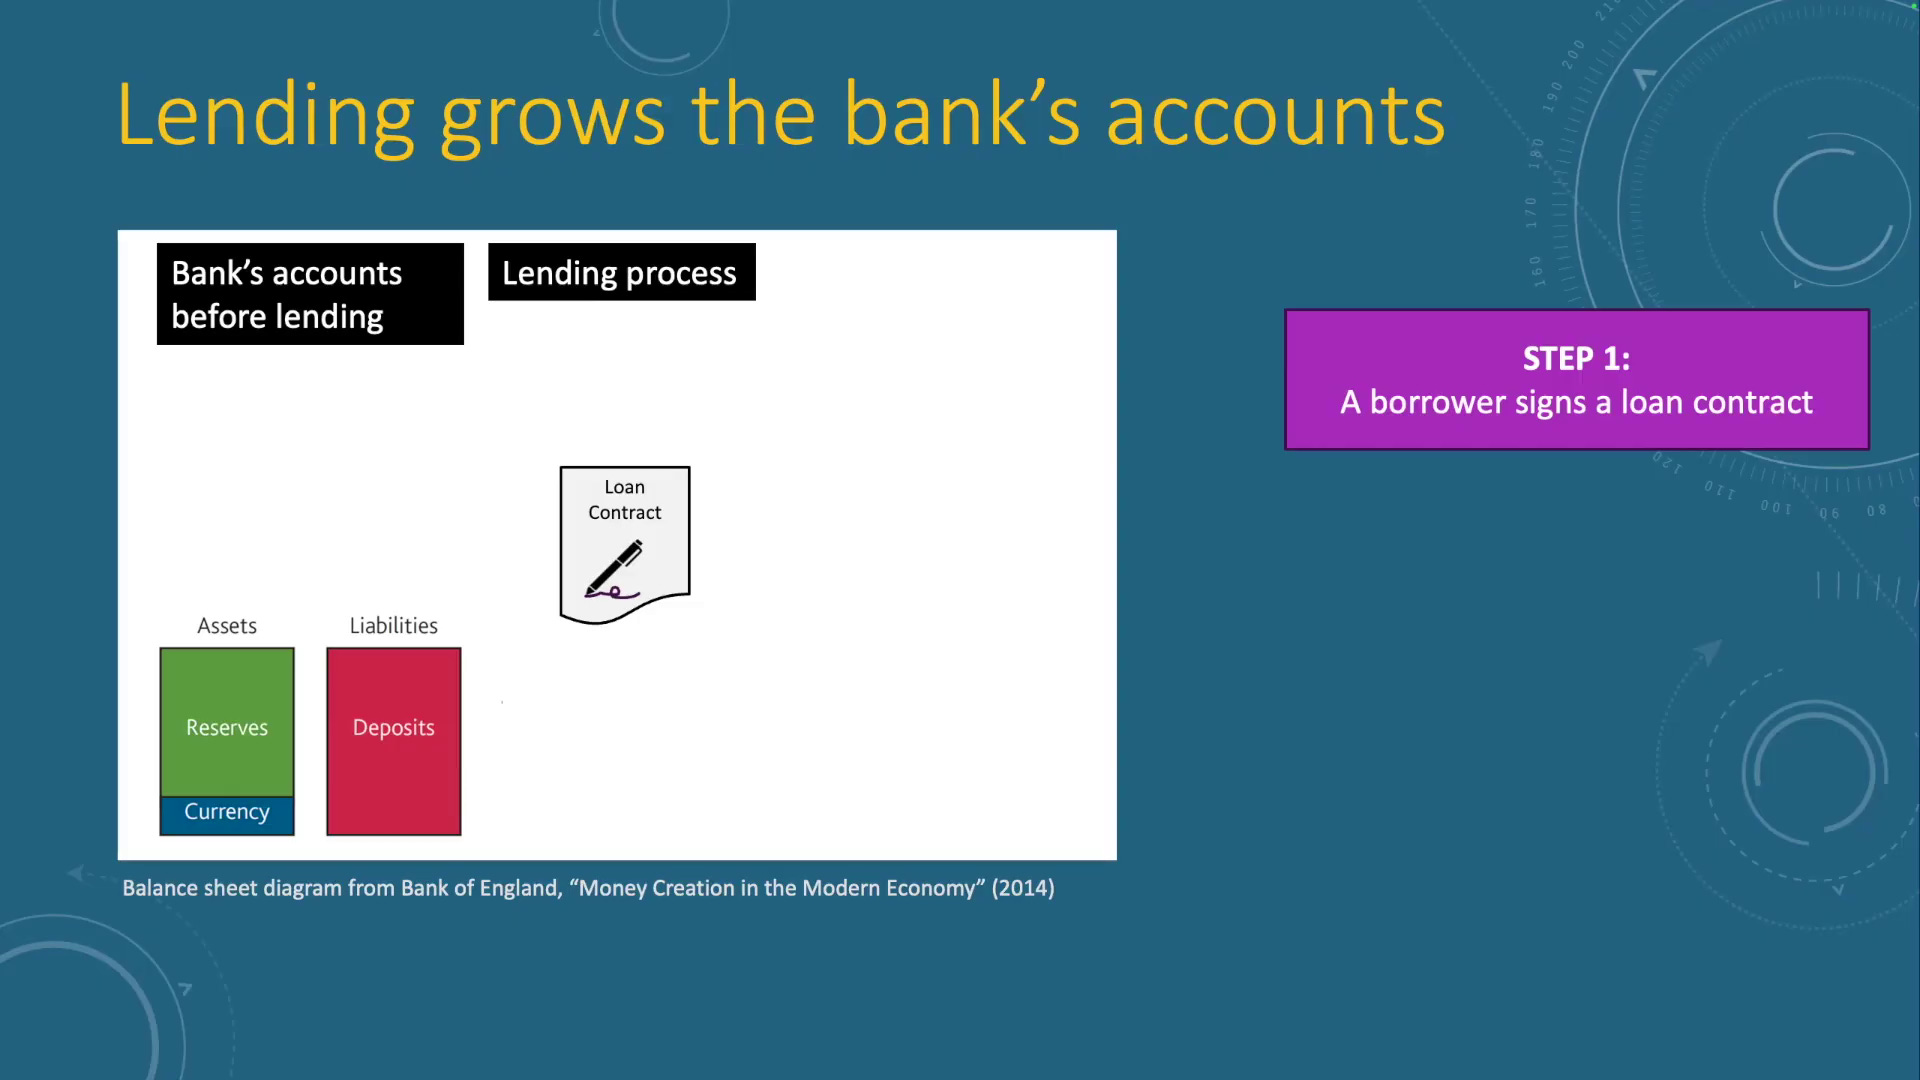
The lending process involves a loan contract being signed and the loan being deposited in the borrower’s account.
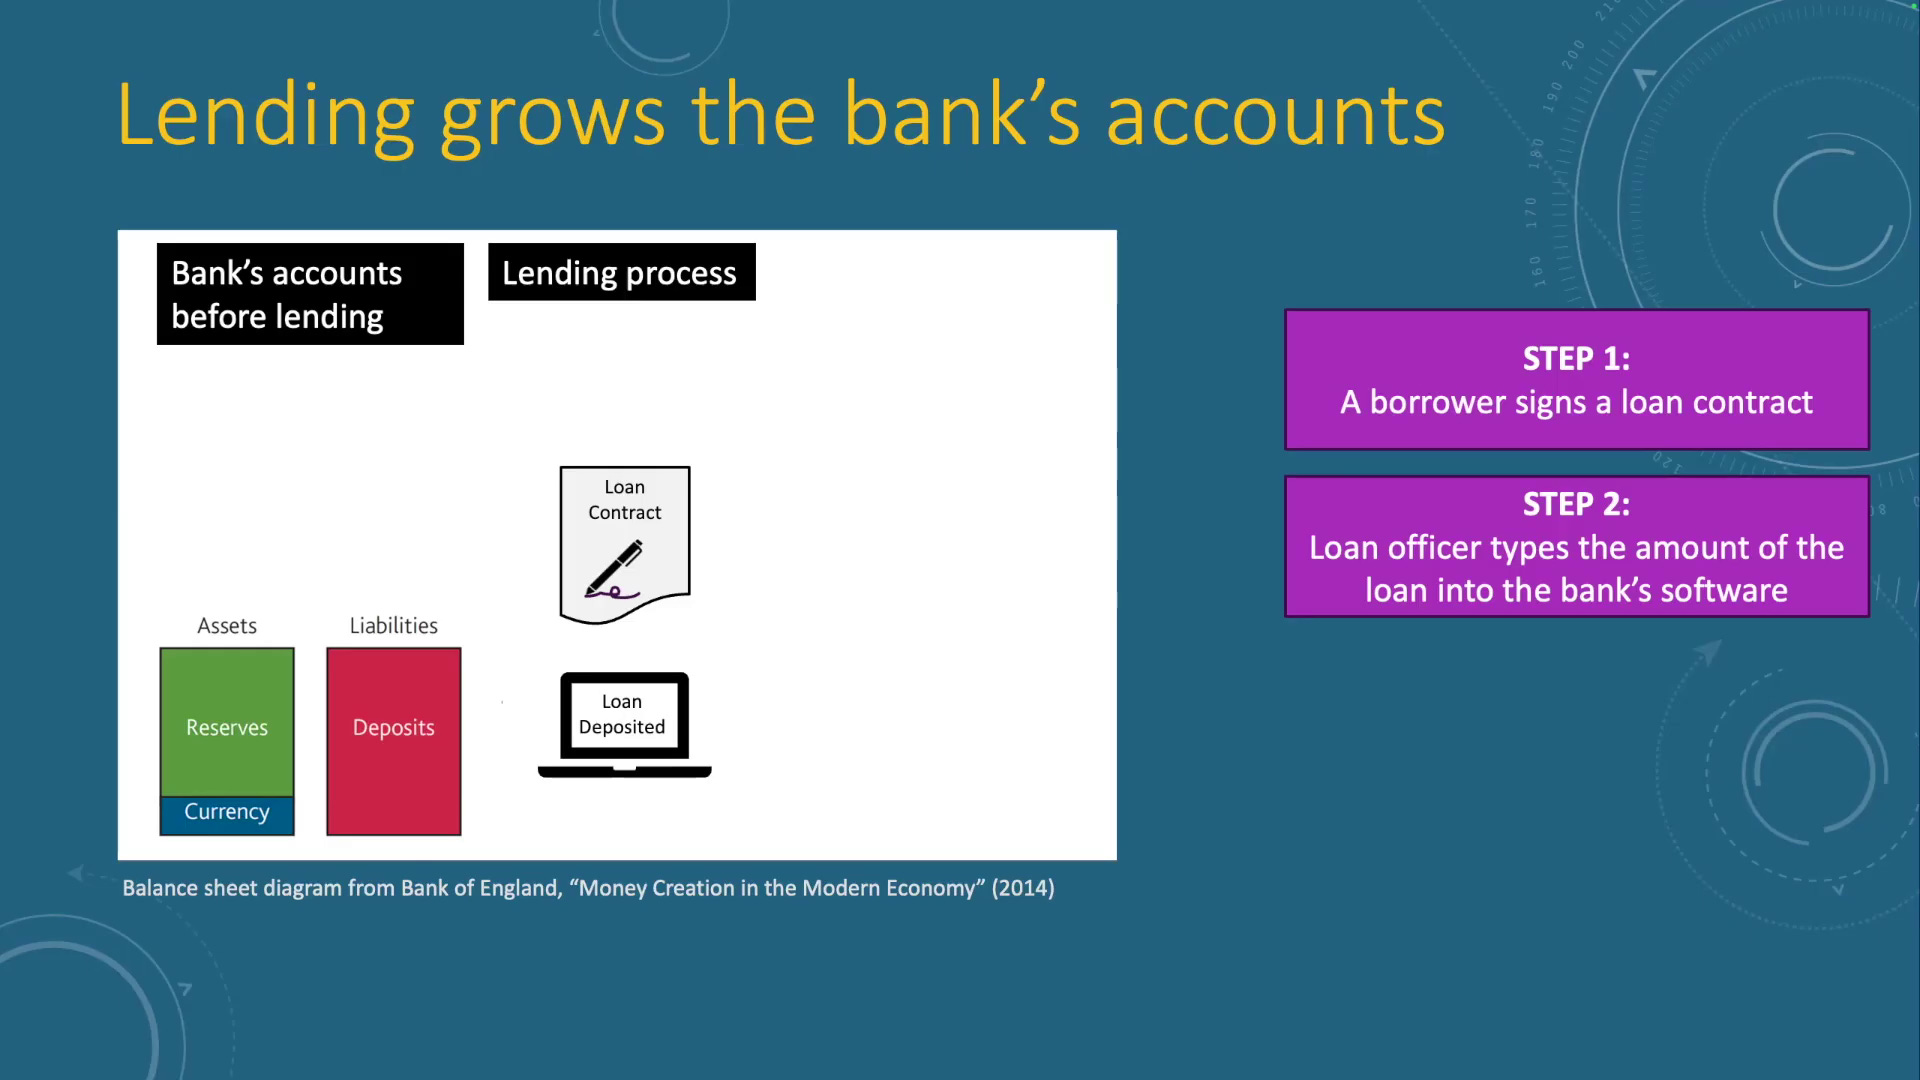
And again, I added these two here: this is the two parts that we talked about before.
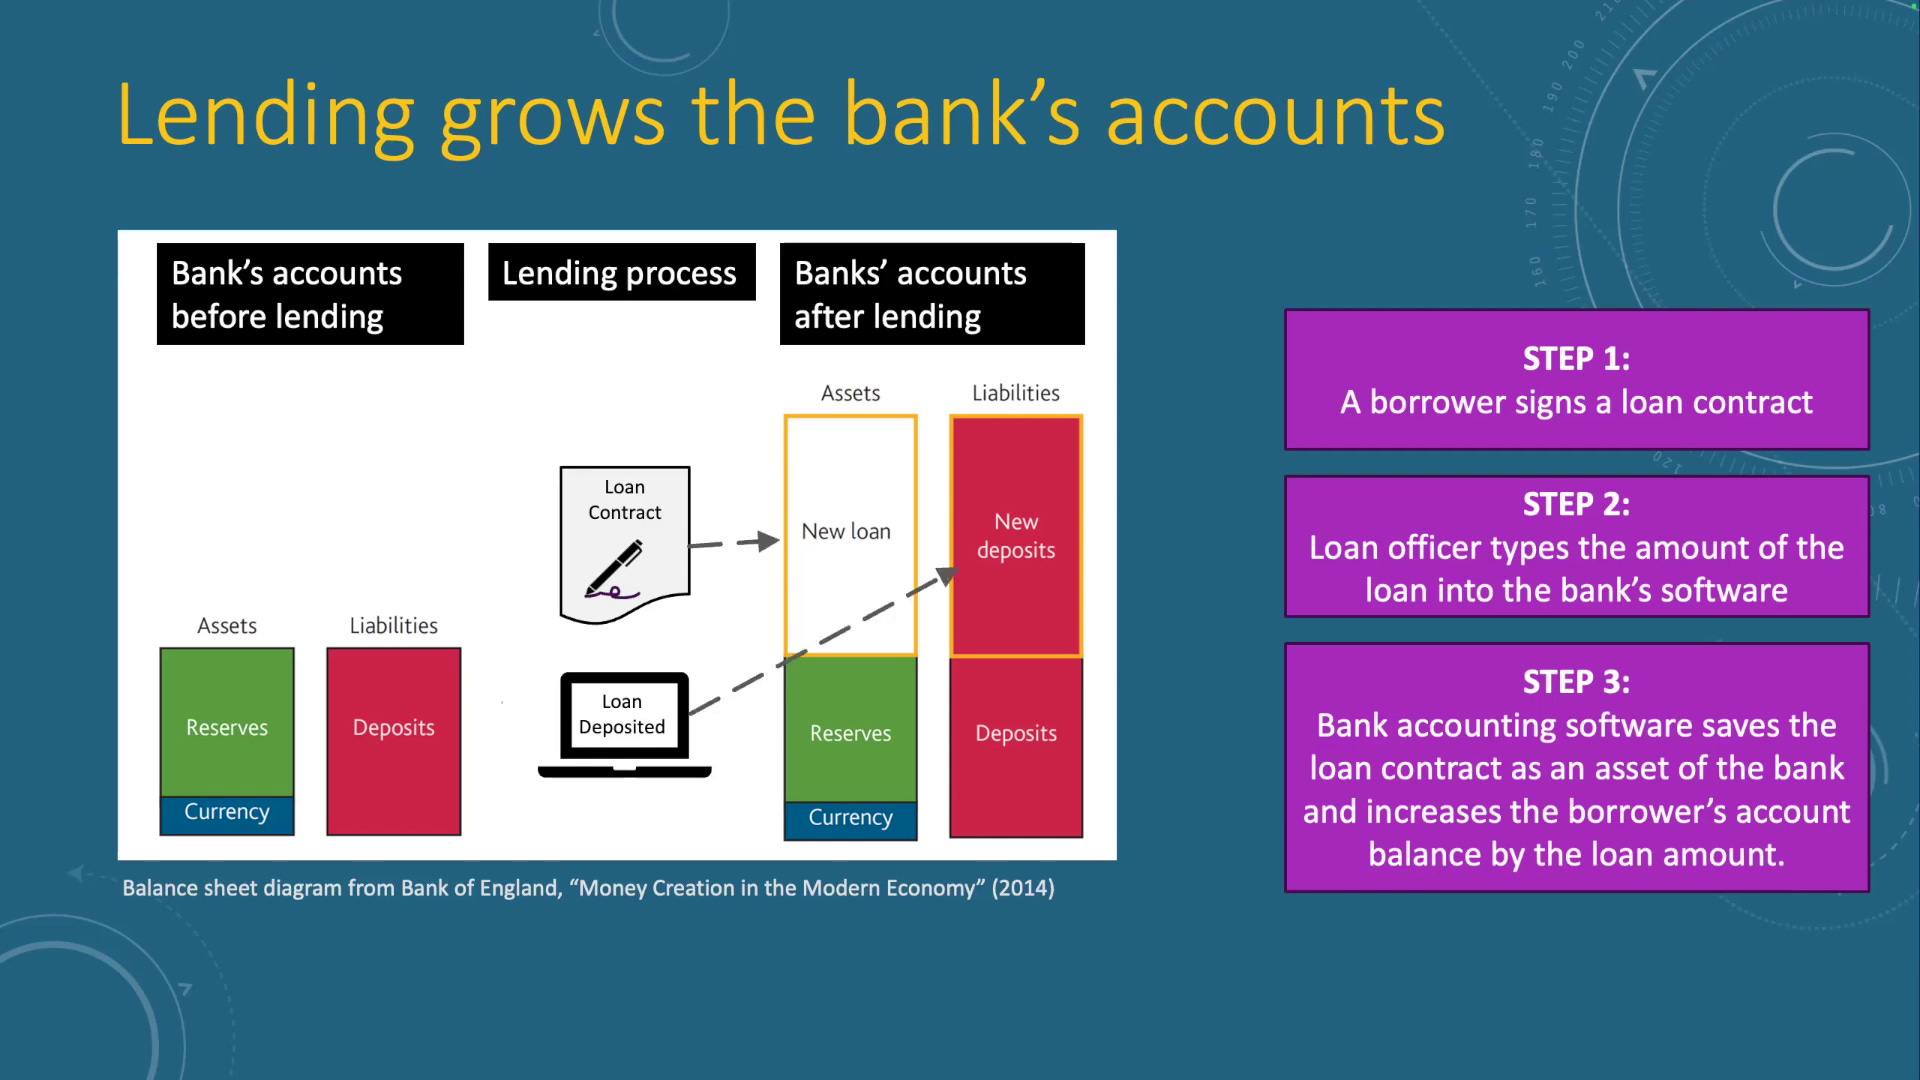
And what the Bank of England shows is that the result is that the accounting records have simply grown. So, the asset side has grown – that’s the loan contract, and the deposit side has grown. And that’s the deposits that were typed into the borrower’s account to match the loan contract.
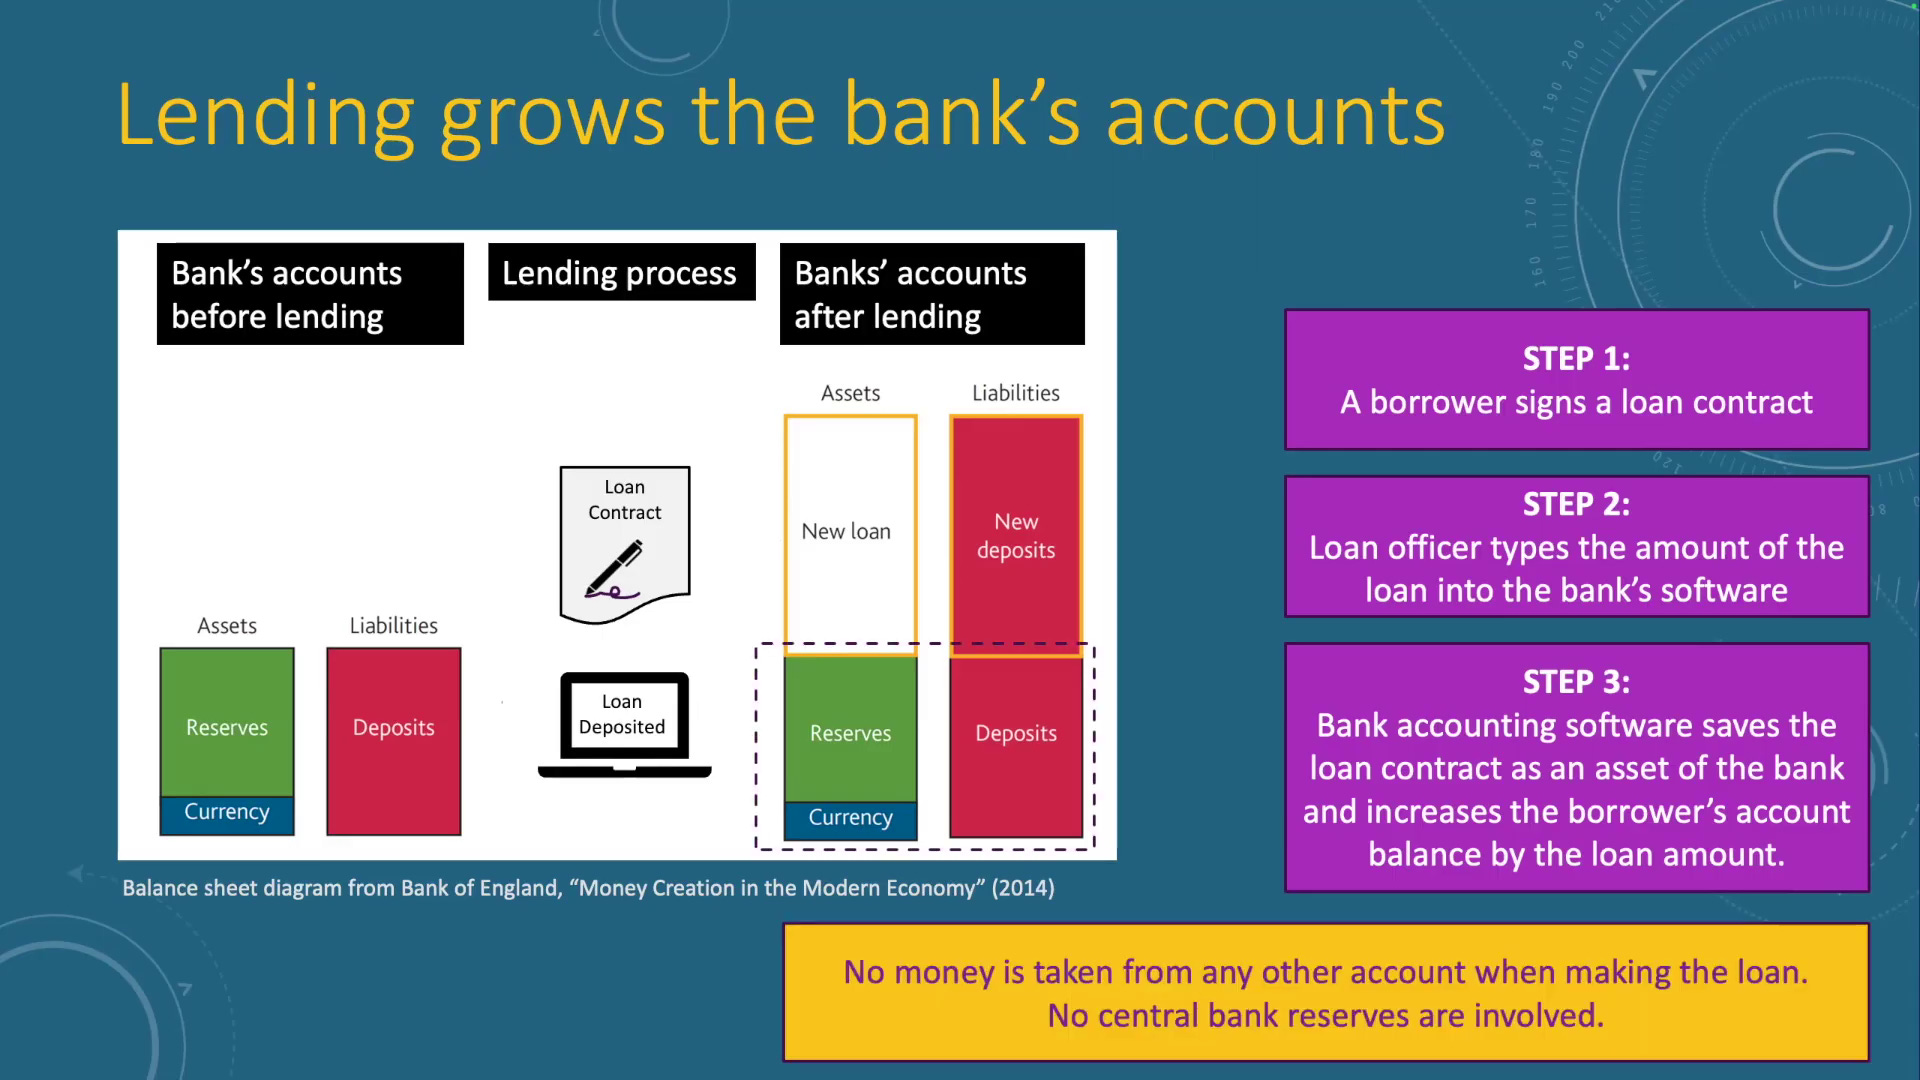
Again, no money is taken from any of the other accounts that were already on the balance sheet of the bank, and no central bank reserves are involved.
Now, some people like to say, “Well, you’re making a big deal out of this, but it’s actually just a mutual swap of IOUs. The customer is providing to the bank a loan contract, which is an IOU statement, and the bank is providing the customer with bank deposits, which is an IOU from the bank.”
But here’s the thing, and you can hear this directly in an excellent course that’s online. Anyone can take it, over 100,000 people have, taught by a Columbia University professor. He’s now at Boston, University of Boston, Boston College. And it’s titled “The Economics of Money in Banking.” And he teaches the accounting that I just showed you.
And what he says is, “Look, when Citibank signs an IOU, it’s money. When I sign an IOU, it’s just credit.” So, that’s the thing. And we’ll talk about this in the law section in the next video, but there’s something special that happens in the law that makes bank IOUs, money.
So here’s a question that often comes up when people learn about this, which is “Why isn’t the economy just overflowing with money?” If every time somebody takes out a mortgage, or a car loan, or a business loan, banks are just creating new money, the economy should just be overflowing with money.
Well, the European Central Bank and actually the Bank of England in its paper as well, explains why that’s not the case. But I just thought you’d want to hear from another bank, another central bank, one of the other largest ones in the world.
And they explain the same thing as the Bank of England, they say, “If a commercial bank grants you a loan to buy a car, they create new money in that way.”
“And when you repay the loan, the money created disappears.”
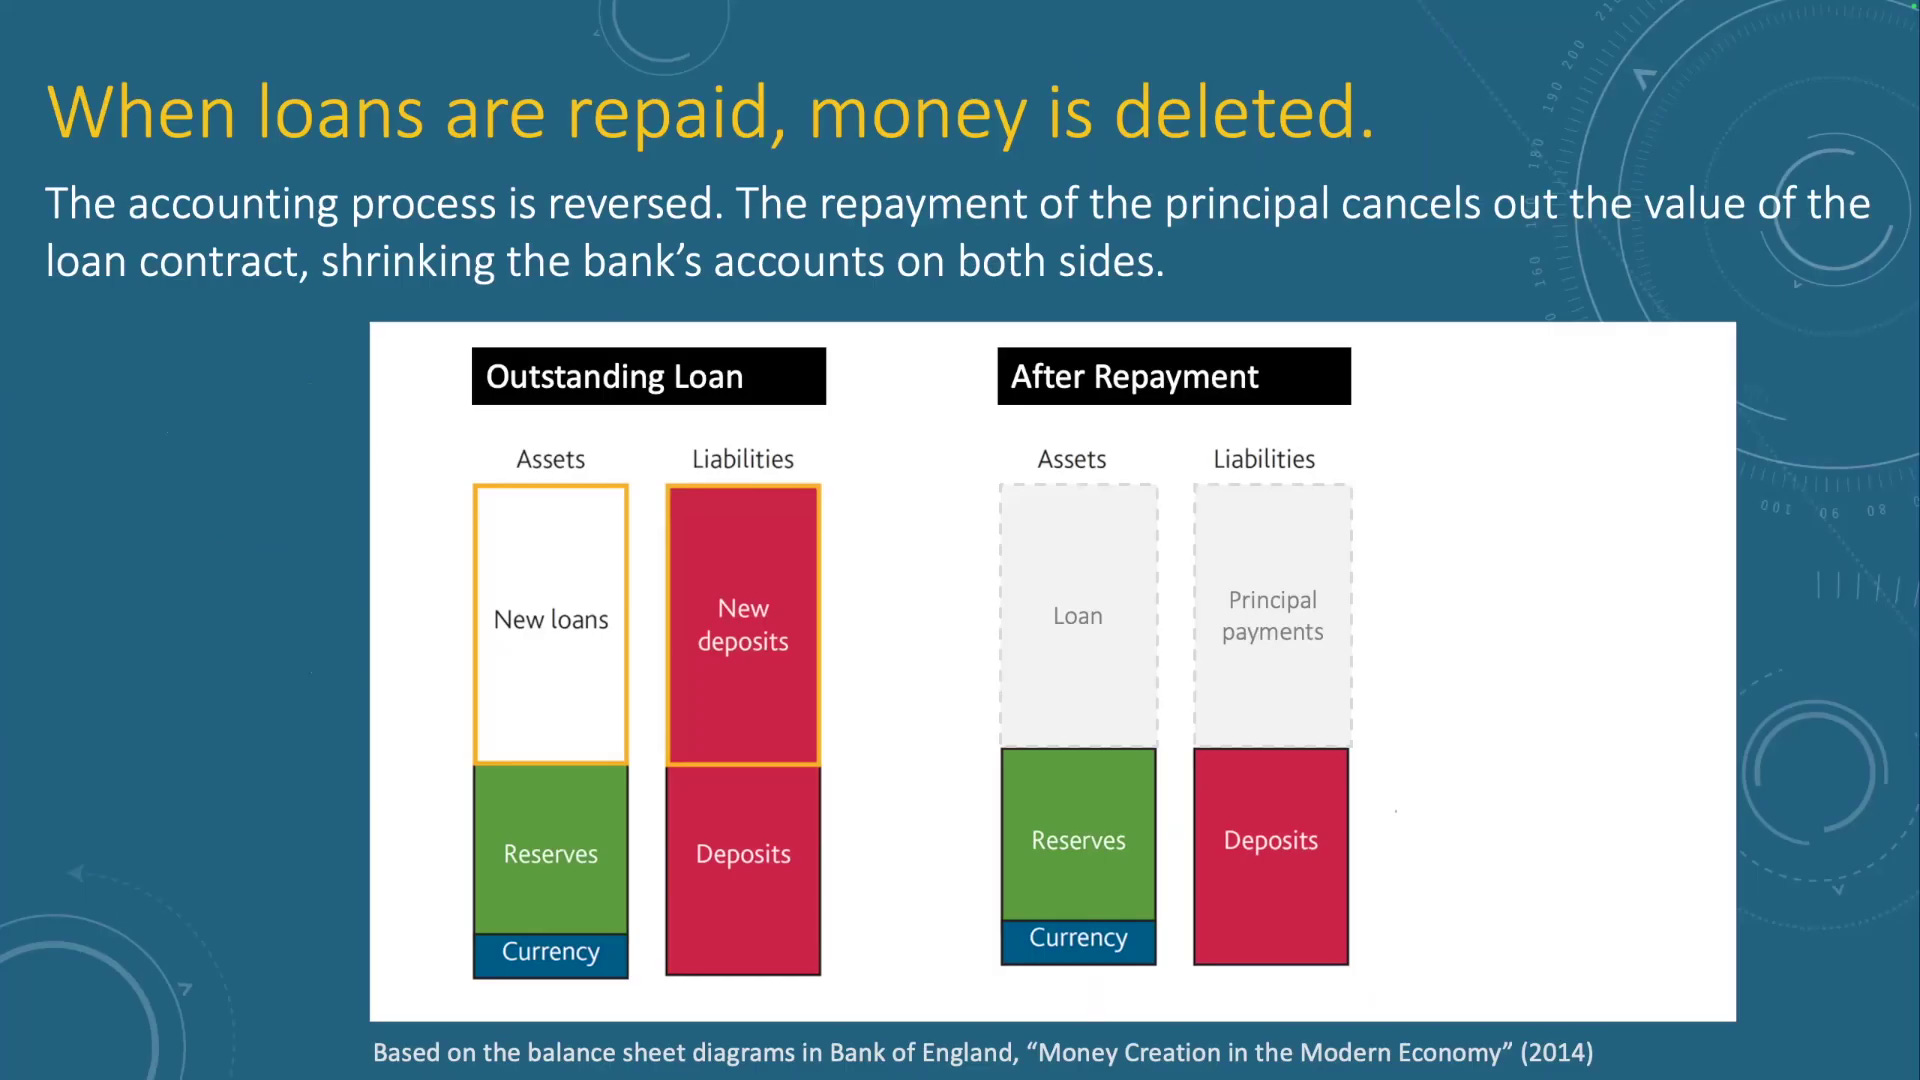
Okay, so that money that you repay to the principal on the loan is simply deleted. It doesn’t get recirculated in the economy. And this is because the accounting process that I showed you before is simply reversed. The repayment of the principal cancels out some of the value of the loan contract. Ultimately, cancels out all of the value of the loan contract, shrinking the bank’s accounts on both sides.
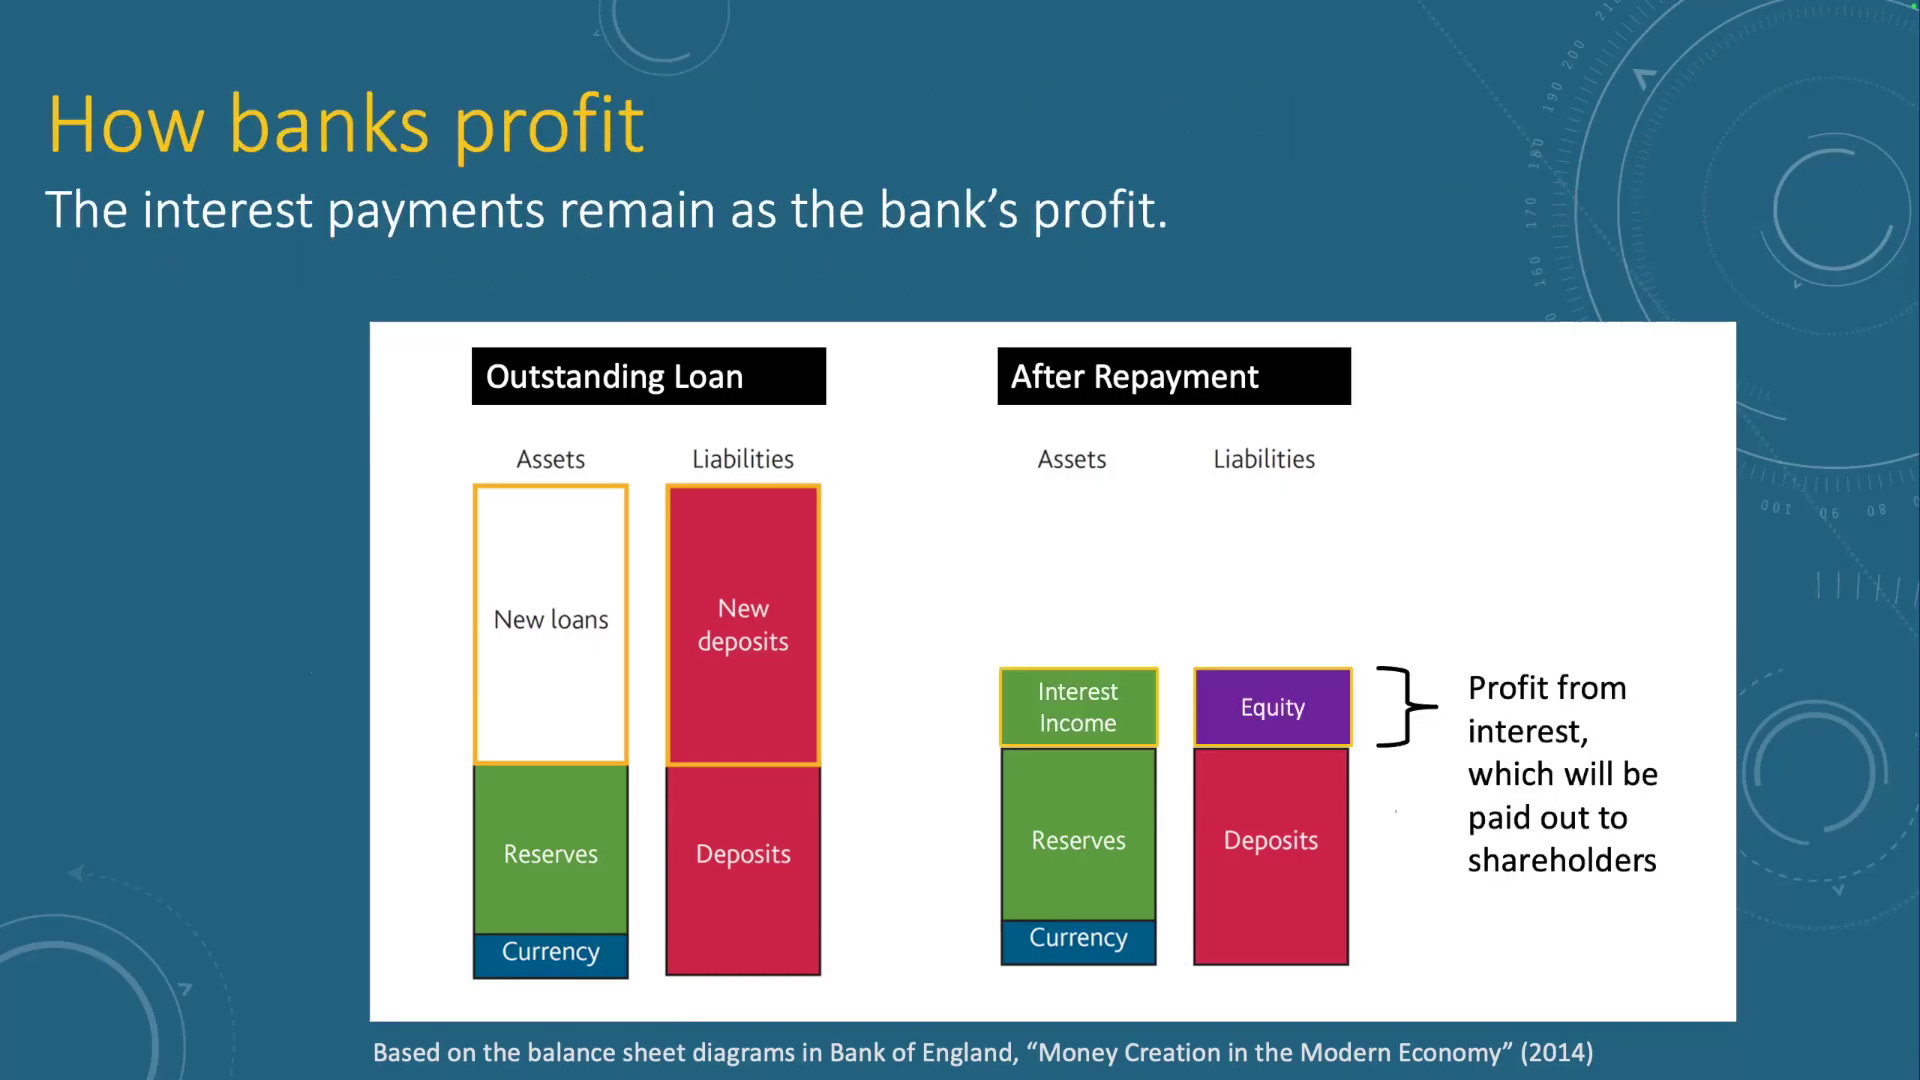
So now how does a bank make a profit if that’s the case? And the reason is that the interest payments, which are in addition to the principal payments, are what the bank gets to keep as its own profits. Now, interestingly, the profits show up on the liability side of the balance sheet. And that’s because the profits from the interest will ultimately be paid out to shareholders. So, they are owed out to shareholders.
So what about cash? Most of us think that cash is something the government creates and we put it in the bank and that’s where bank deposits come from. But as I told you before, that’s not the case.
So, in a different Bank of England paper, they explain how this works, and say, “Cash can only be withdrawn against a pre-existing electronic deposit that has first been created in some other way.” That some other way being, for example, a loan.
Now, as I mentioned earlier, the money system that we have today is pretty unique, in that, the accounting records, it’s an accounting record monetary system like the Sumerians and the Egyptians were using it for thousands of years. But in this case, it also has the physical transactable money that the Grecians invented back in ancient Greece, with the coins. But they come together in the sense that the electronic deposits, the accounting records are created first, and then the cash is created to represent those electronic deposits when customers would like a physical representation of their bank deposits.
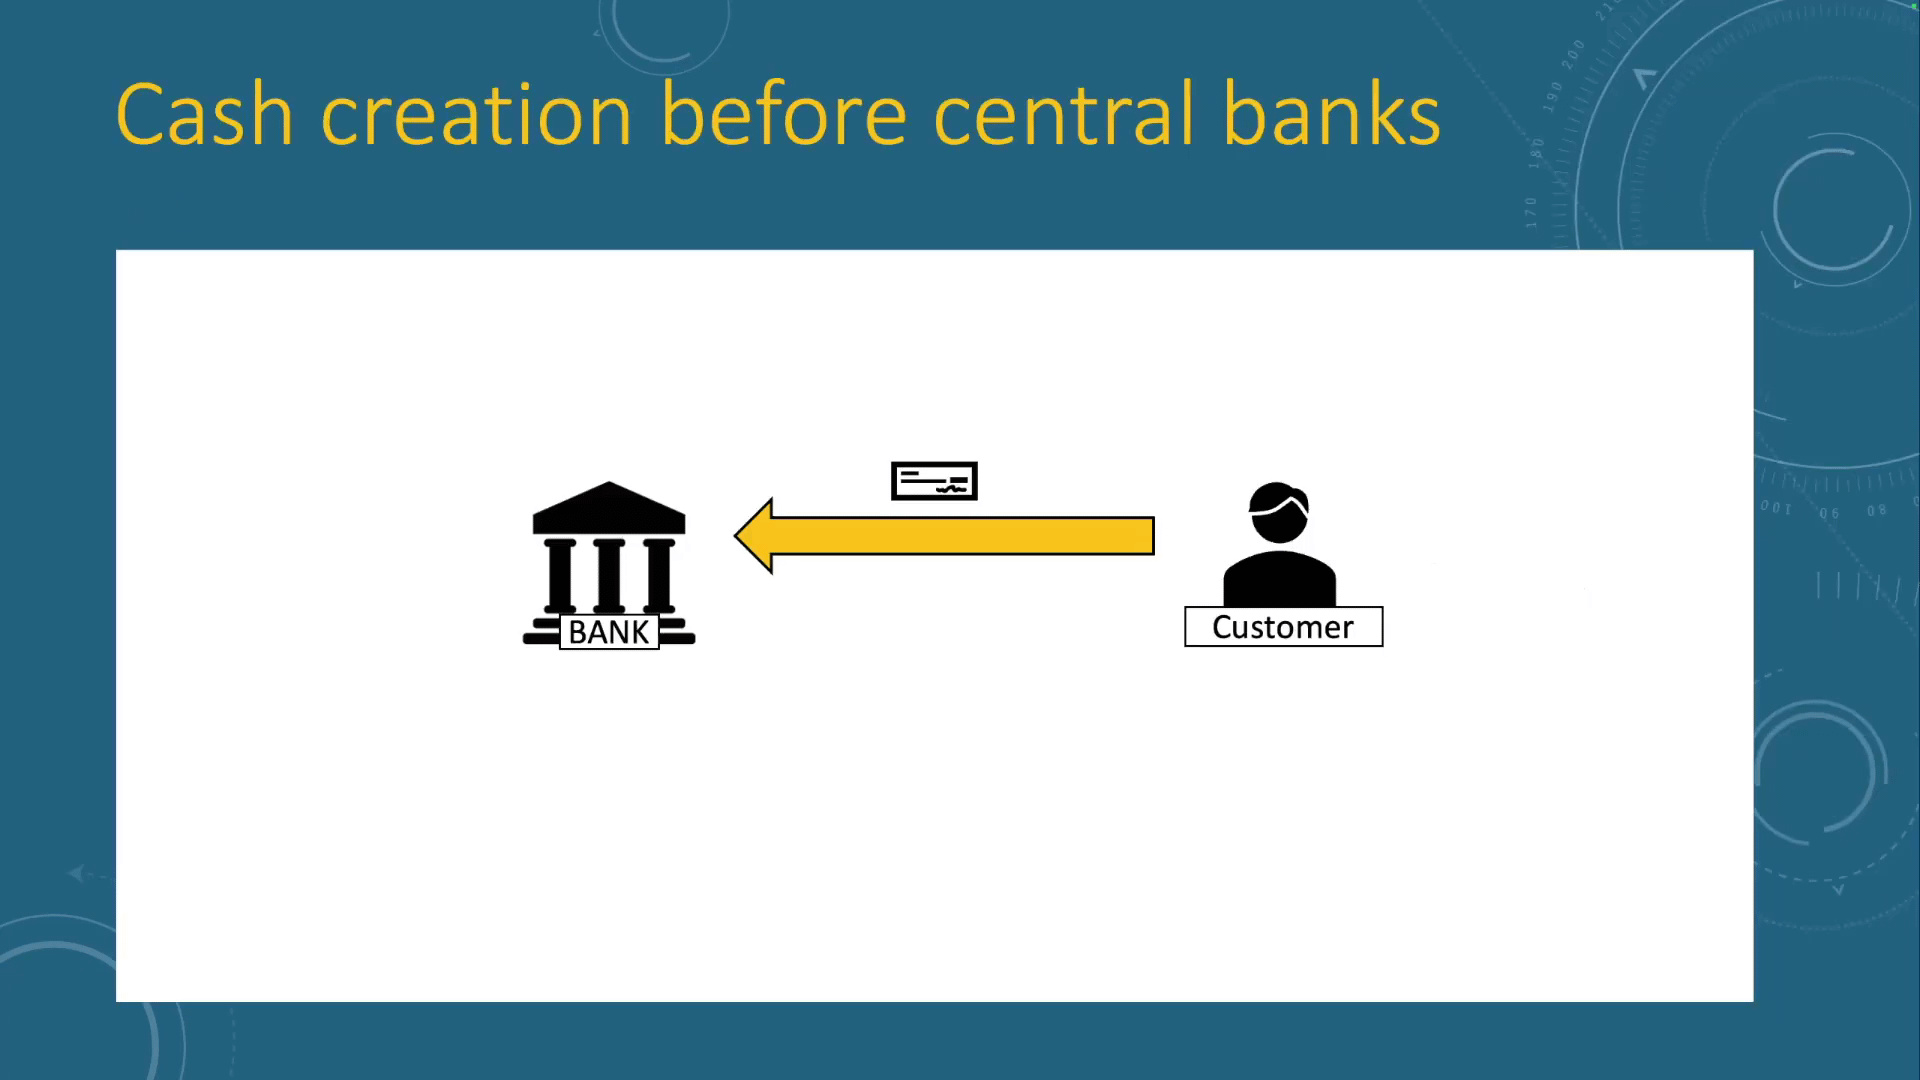
So let’s look at that. So before central banks existed, we have to remember that central banks are very new in human history. Most countries in the world only got a central bank after the 1940s, really after the Great Depression and World War II. Before that, for over 300 years, banking in this way, this banking created by commercial bank accounting system with physical bills and coins, already existed before central banks existed.
So how did cash come into existence? Let’s take, for example, here a customer. They’re bringing a check or a deposit slip to their bank, and they’re saying, “I want my bank money. I want it in physical form.”
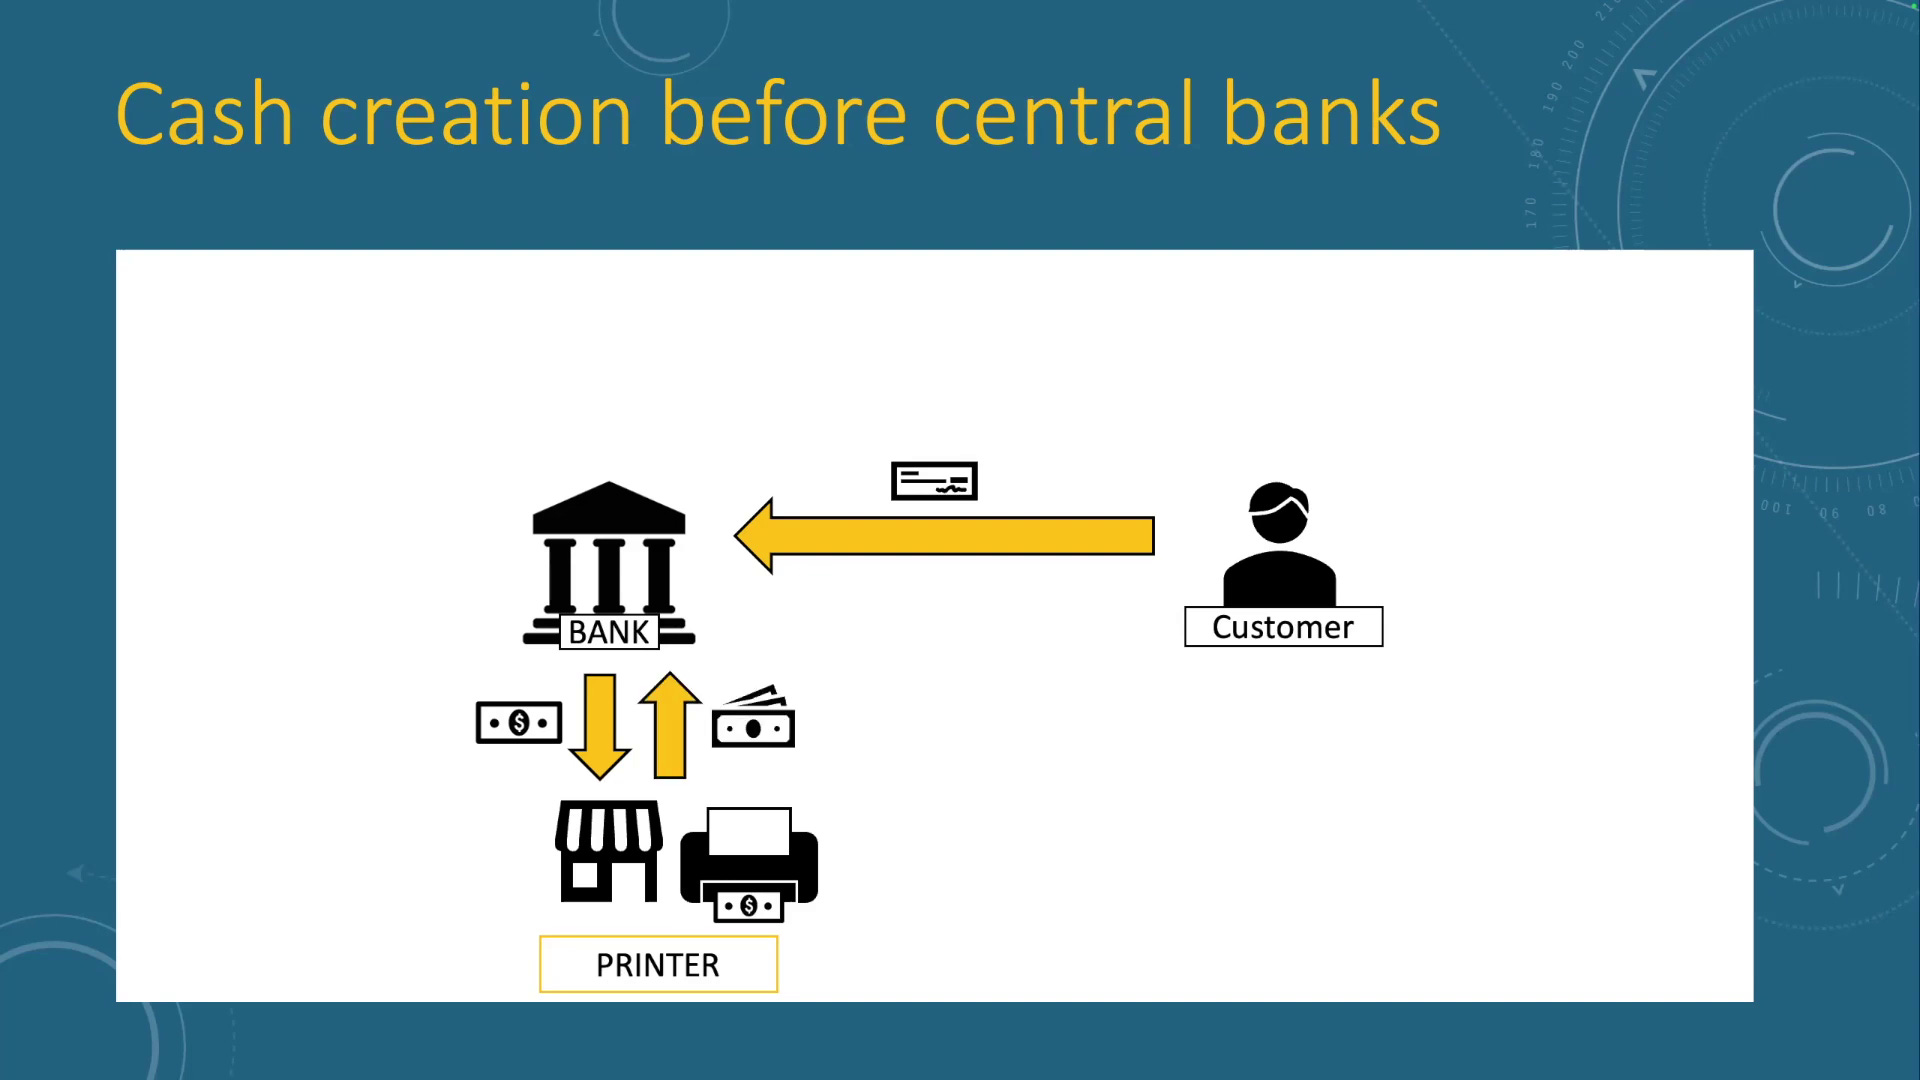
In the past, the way it would work is that the bank would turn around to a printing and engraving business and pay them a small amount of money to get back from them a large number of bank notes. So, they might pay, you know, five cents to the printer for every $1 bank note that they would get back. And this was because the paper and ink involved in printing it only cost five cents, and they’re getting back notes that are worth a dollar to them when they provide it to customers.
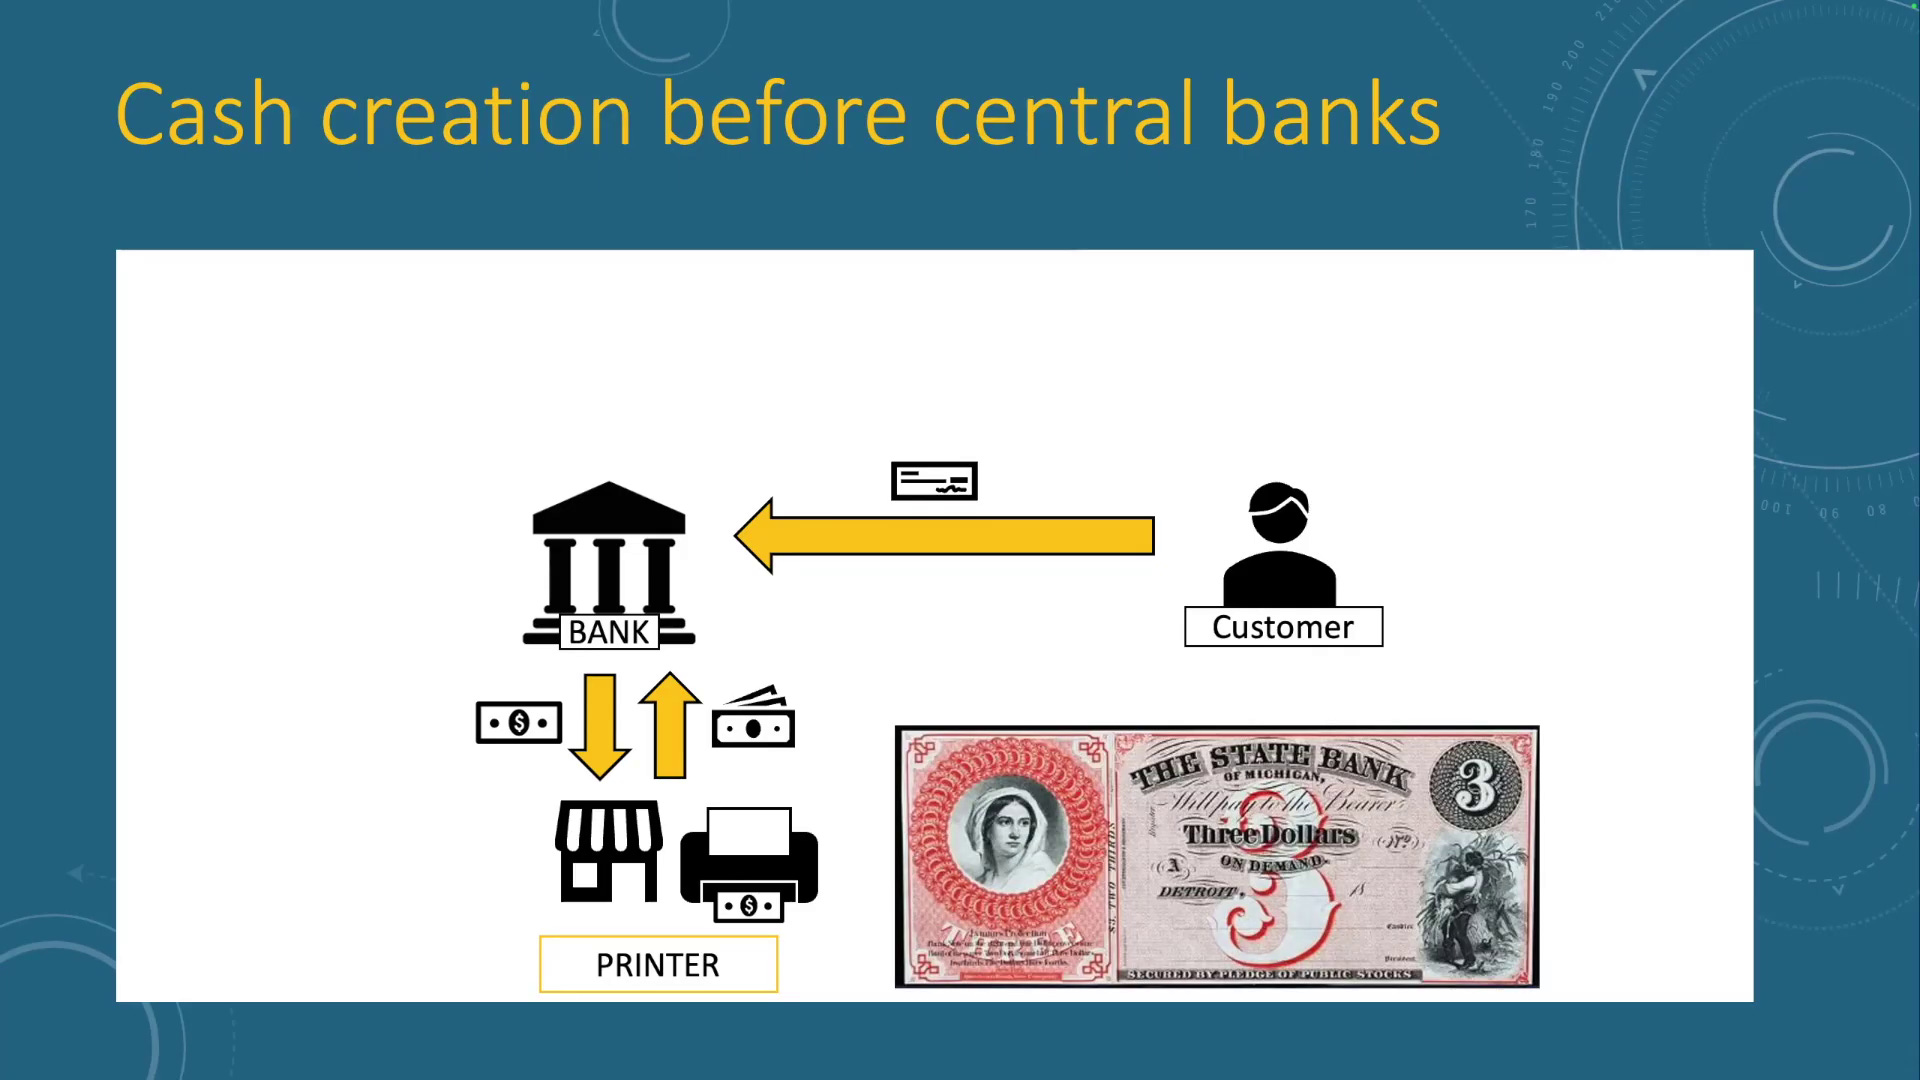
And you can actually see this is totally fascinating. Before central banks came along and made all the notes look the same, you would find in the economy many different bank notes that would say on them, “This is from the State Bank of Michigan.” And if you were in the United States before 1913 and you opened your wallet or went to the market, you might have bills that were from the State Bank of Michigan, or you might have them from the Central Carolina Bank or any other bank.
And you would know, you would understand that banks are creating this money. And I can see which bank created the money even when I’m using the money in the physical world.
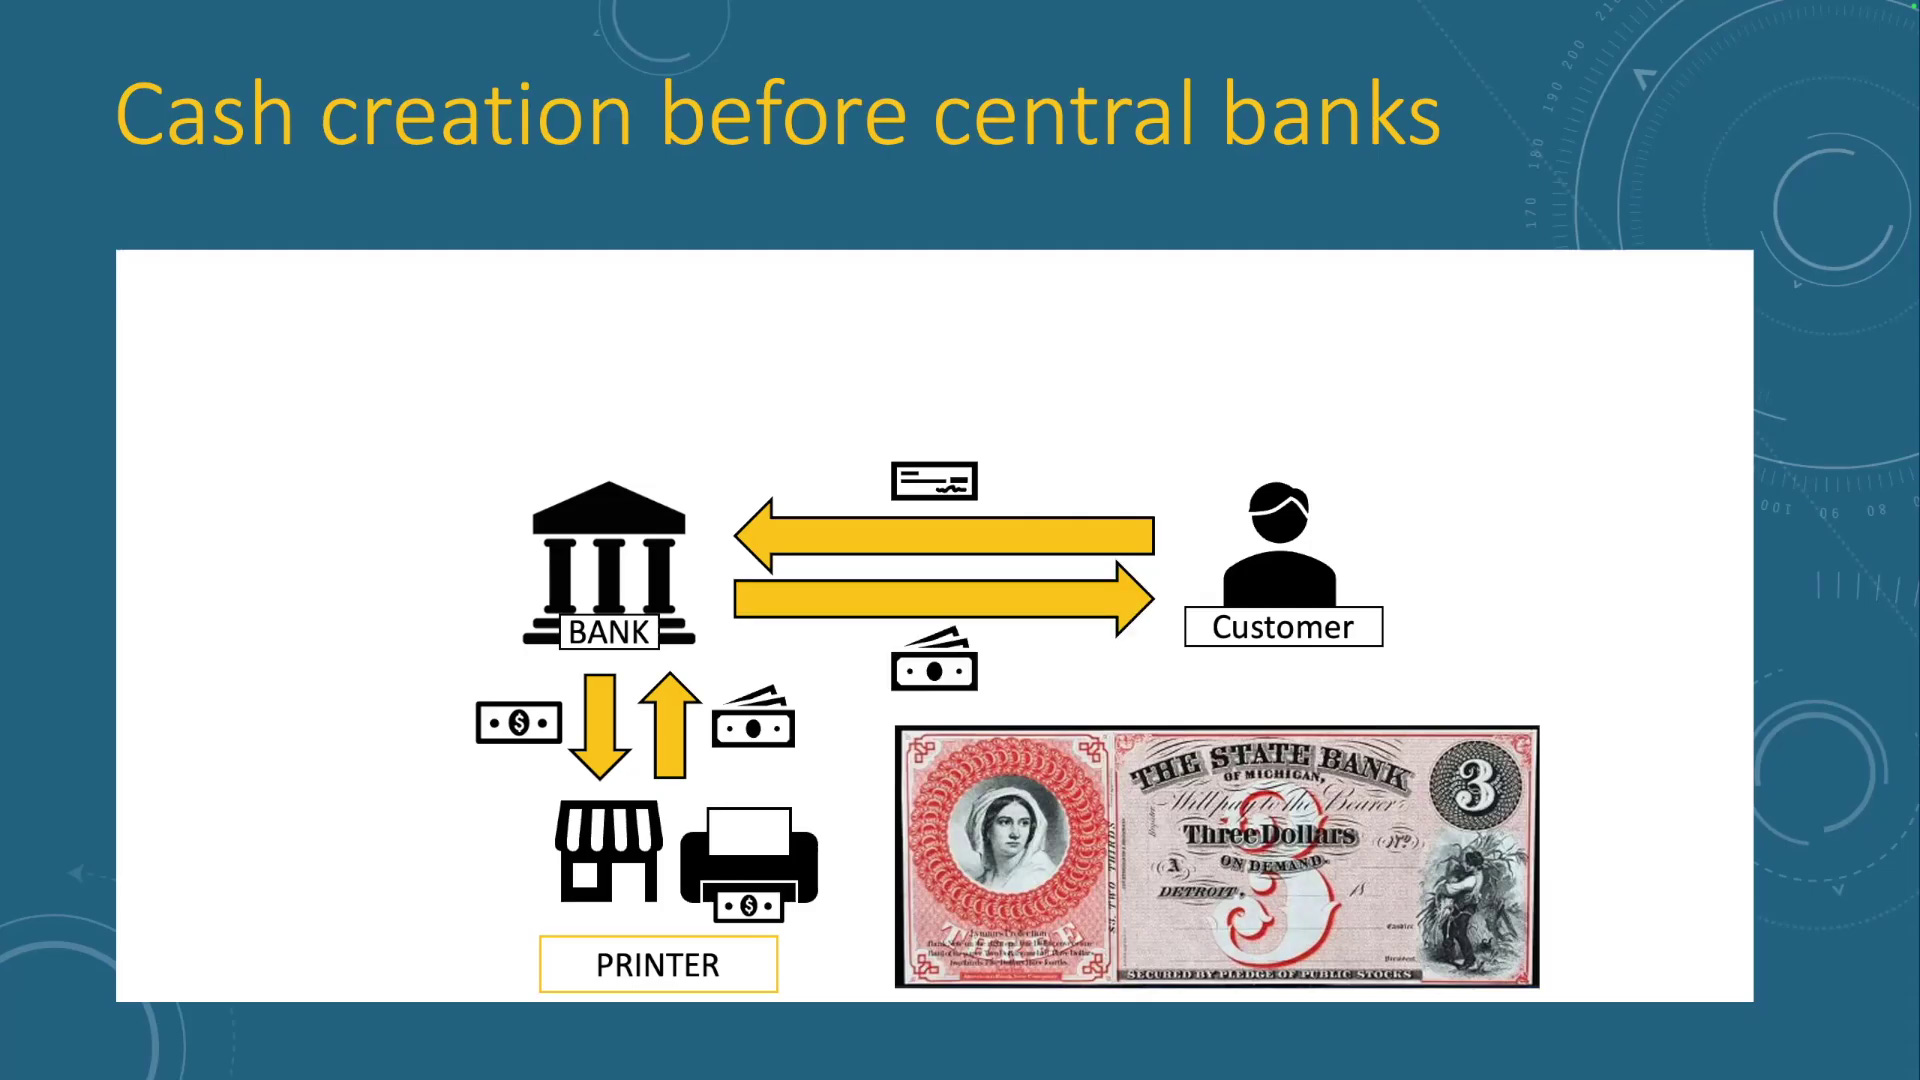
That ability, so in that last step, the bank provides those to the customer.
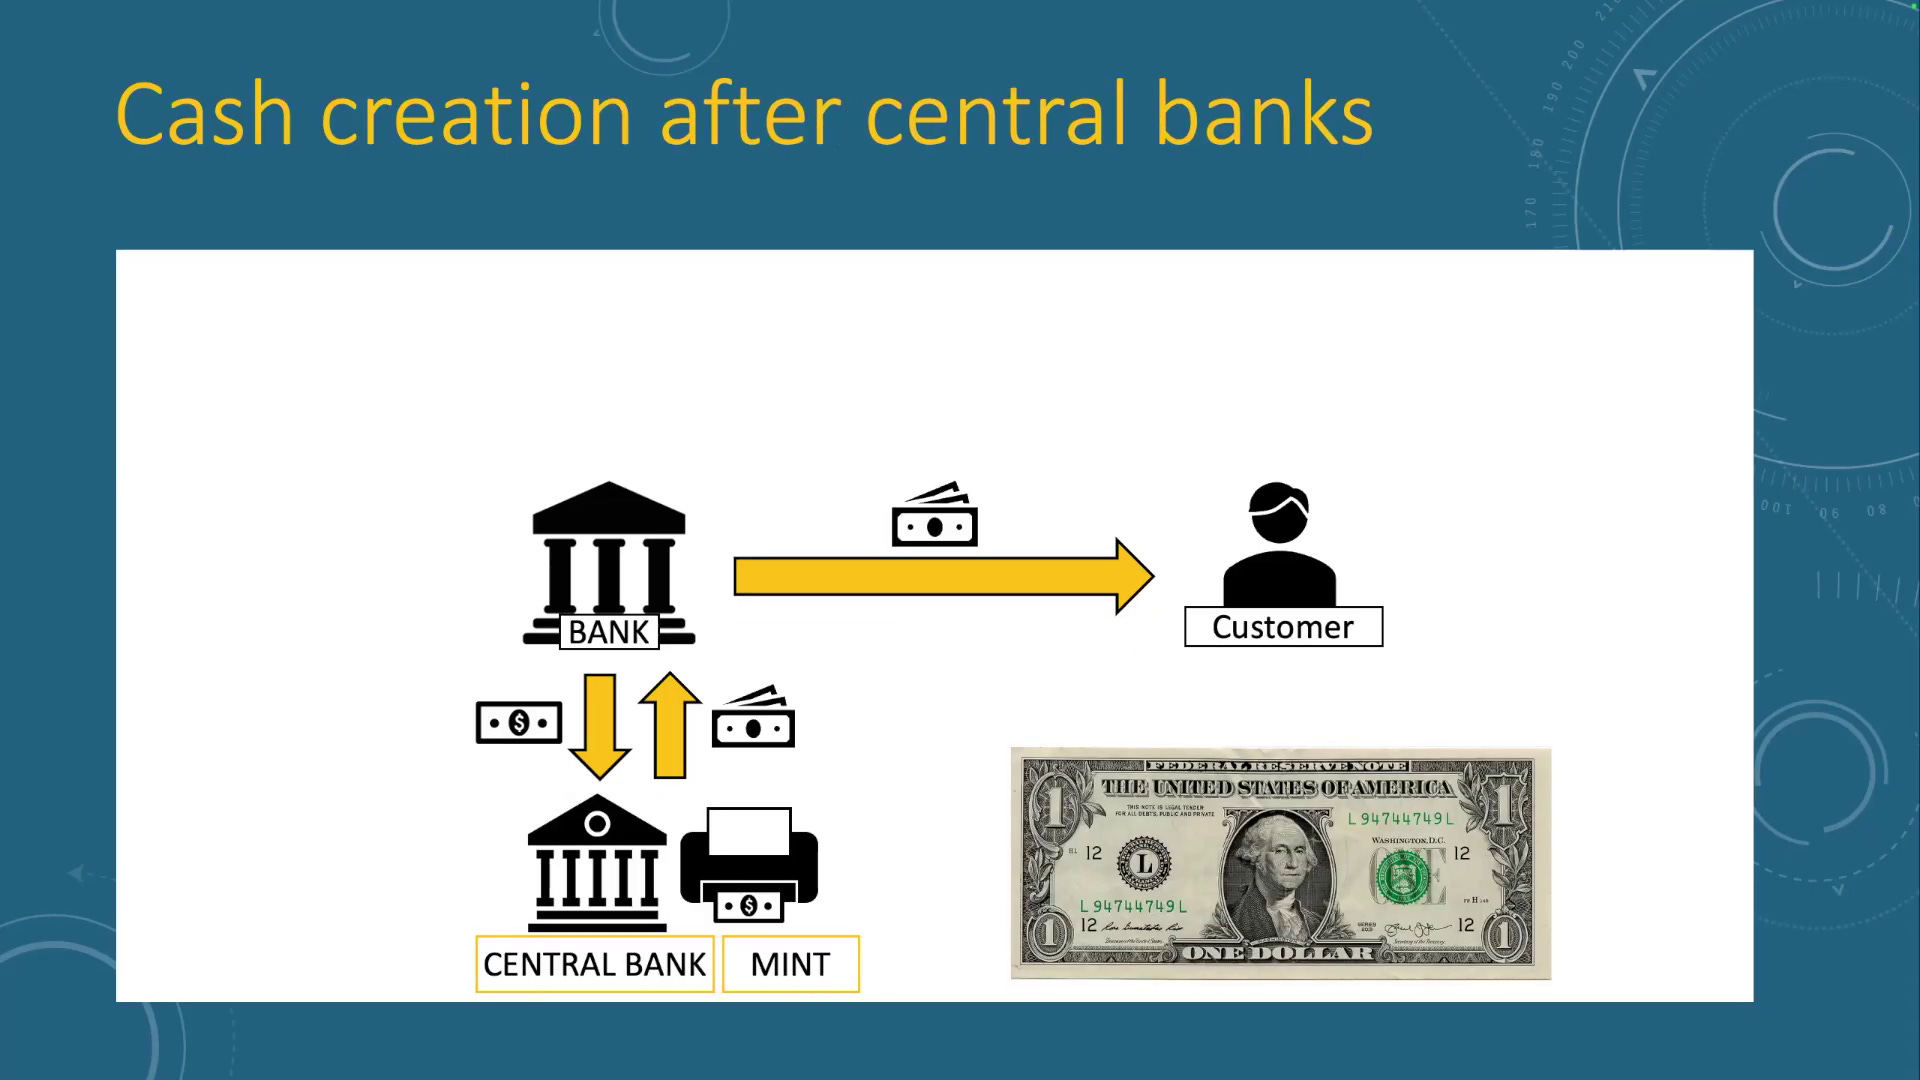
What changed when we got central banks was that the central banks began to provide the printing and engraving service, usually through a national treasury or mint, that would do the printing and engraving. And they provided the banks with a service, which is that they made all these banknotes look uniform.
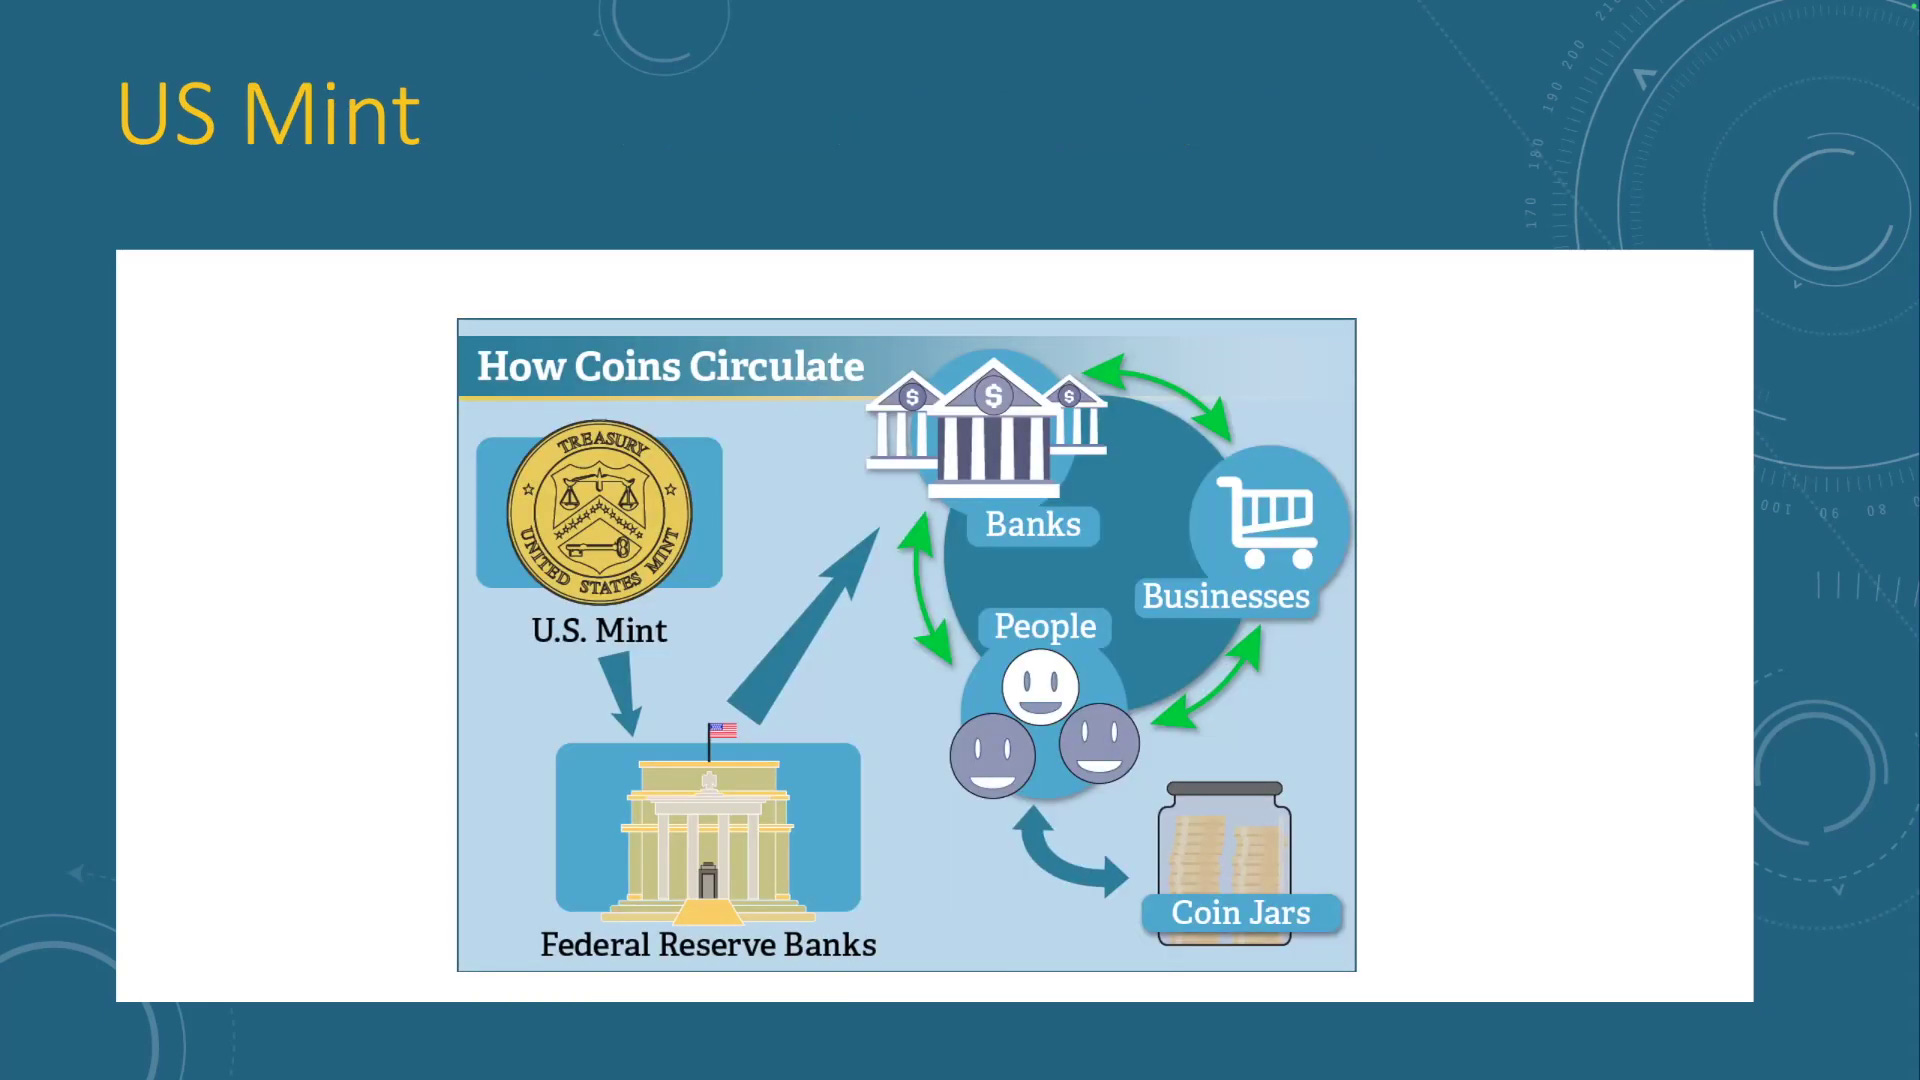
And you can see this if you go to the United States Mint’s own website, you can see on the upper left that the Mint is producing the physical money. It goes to the Federal Reserve Banks. The Federal Reserve Banks arrow goes to the commercial banks, and then it gets into the circulation of the people and businesses. It isn’t the case that our government spends the coins and bills into circulation directly to the people or to businesses.
Okay, so just to recap, banks lend by creating new deposits in their accounting records. When the principal is repaid, the deposits disappear, deleting money from the economy. And cash only enters the economy as a physical representation for deposit record entries in a bank accounting system. So, I think you can see now that this is quite different than the story that money is a physical thing, and that banks are just managing this physical thing for us. It’s quite, quite different from that.
Now, I think it’s really important and I’ve learned from speaking to people that it’s very important for people to hear this directly from the folks that are involved. So, I’m going to play for you now some videos, just very brief clips, from a central banker, banker and banking scholar. And I’ve attended hundreds of presentations, dozens of conferences, watched thousands of hours of video about this. So, this is really a curation for you of just a few of the things that I’ve seen. And so, I’m hoping I’m going to save you some time with this.
So the first video is Ryland Thomas. He’s an economist at the Bank of England, and he’s one of the authors of that paper, that seminal paper, “Money Creation in the Modern Economy.”
And the Bank of England actually recorded a video when they released that bulletin. So, let’s hear what they have to say.
Interviewer: “Ryland, your article is about how money gets created. We’re surrounded here by gold in the vaults of the Bank of England, and historically, in the gold standard, the amount of gold would have been related to the stock of money in the economy. Things are very different now. In the modern economy, where does money come from?
Ryland Thomas: “Well, let’s start off with narrow or central bank money. As the name suggests, central bank money is determined by the Bank of England and consists of notes and reserves. And in normal times at least, notes and reserves are determined by the amount of notes that people want to hold or need for their transit actions, and the amount of notes and reserves that banks want to hold given the level of interest rates in the economy. It is not chosen or fixed by the central bank as is sometimes described in some economics textbooks.”
Interviewer: “Your article focuses on broad money. What determines how much of that there is?”
Ryland Thomas: “Well, broad money, which in many ways is a better measure of the amount of money circulating in the economy, includes all the bank deposits of households and companies. And one of the key points of the article is that banks create additional broad money whenever they make a loan. Now, while this is nothing new, it is sometimes overlooked as the main way in which money is created. And it runs contrary to the view sometimes put forward that banks can only lend out deposits that they already have. In fact, loans create deposits, not the other way around.”
So even if you didn’t understand all the details, hopefully you got the gist that what we commonly understand is not the case and the central bank isn’t directly controlling the amount of money that’s being created by banks.
So secondly, let’s hear from a banker now. This is Michael Kumhof. He’s a former Barclays banker. He’s actually now an economist at the Bank of England, but when he was at the International Monetary Fund, he published a famous paper or two about banks. One of his papers is titled “Banks are not Intermediaries of Loanable Funds,” and another one titled “The Truth About Banks.” So, let’s hear from Michael.
Michael Kumhof: “Basically, the banks sit there. They wait for deposits to arrive, and if they have enough deposits, they lend them out to somebody else. And that is completely wrong. This is the wrong model of banks, because what happens in reality is exactly the opposite. And I’ve done this. I’m a banker. I know that that’s how it works. And you can read it on many central bank websites, that’s how it works. It’s that banks, when they decide the economy is good, we are optimistic, we are now making loans. They don’t need to wait for any deposits because when they make a loan, they create the deposit right there. Banks create money.”
All right, so the last person we’re going to hear from is Richard Werner. He’s the Oxford-trained banking scholar who went and examined the accounting software that I told you about earlier. And what’s nice about this clip is that he brings it back to the point that I started with, which is that this is an issue that has relevance for many of concerns.
Richard Werner: “Now, banking actually has not been very well understood. There’ve been ‘Three Theories of Banking.’ And they’ve existed and coexisted for at least the past century. The most dominant one currently is still ‘The Financial Intermediation Theory of Banking.’ And nobody had ever done an empirical test. So, I thought, well, since these theories are mutually contradicting, when it comes to the crucial question of ‘Where does the money come from when you get a loan from the bank?’
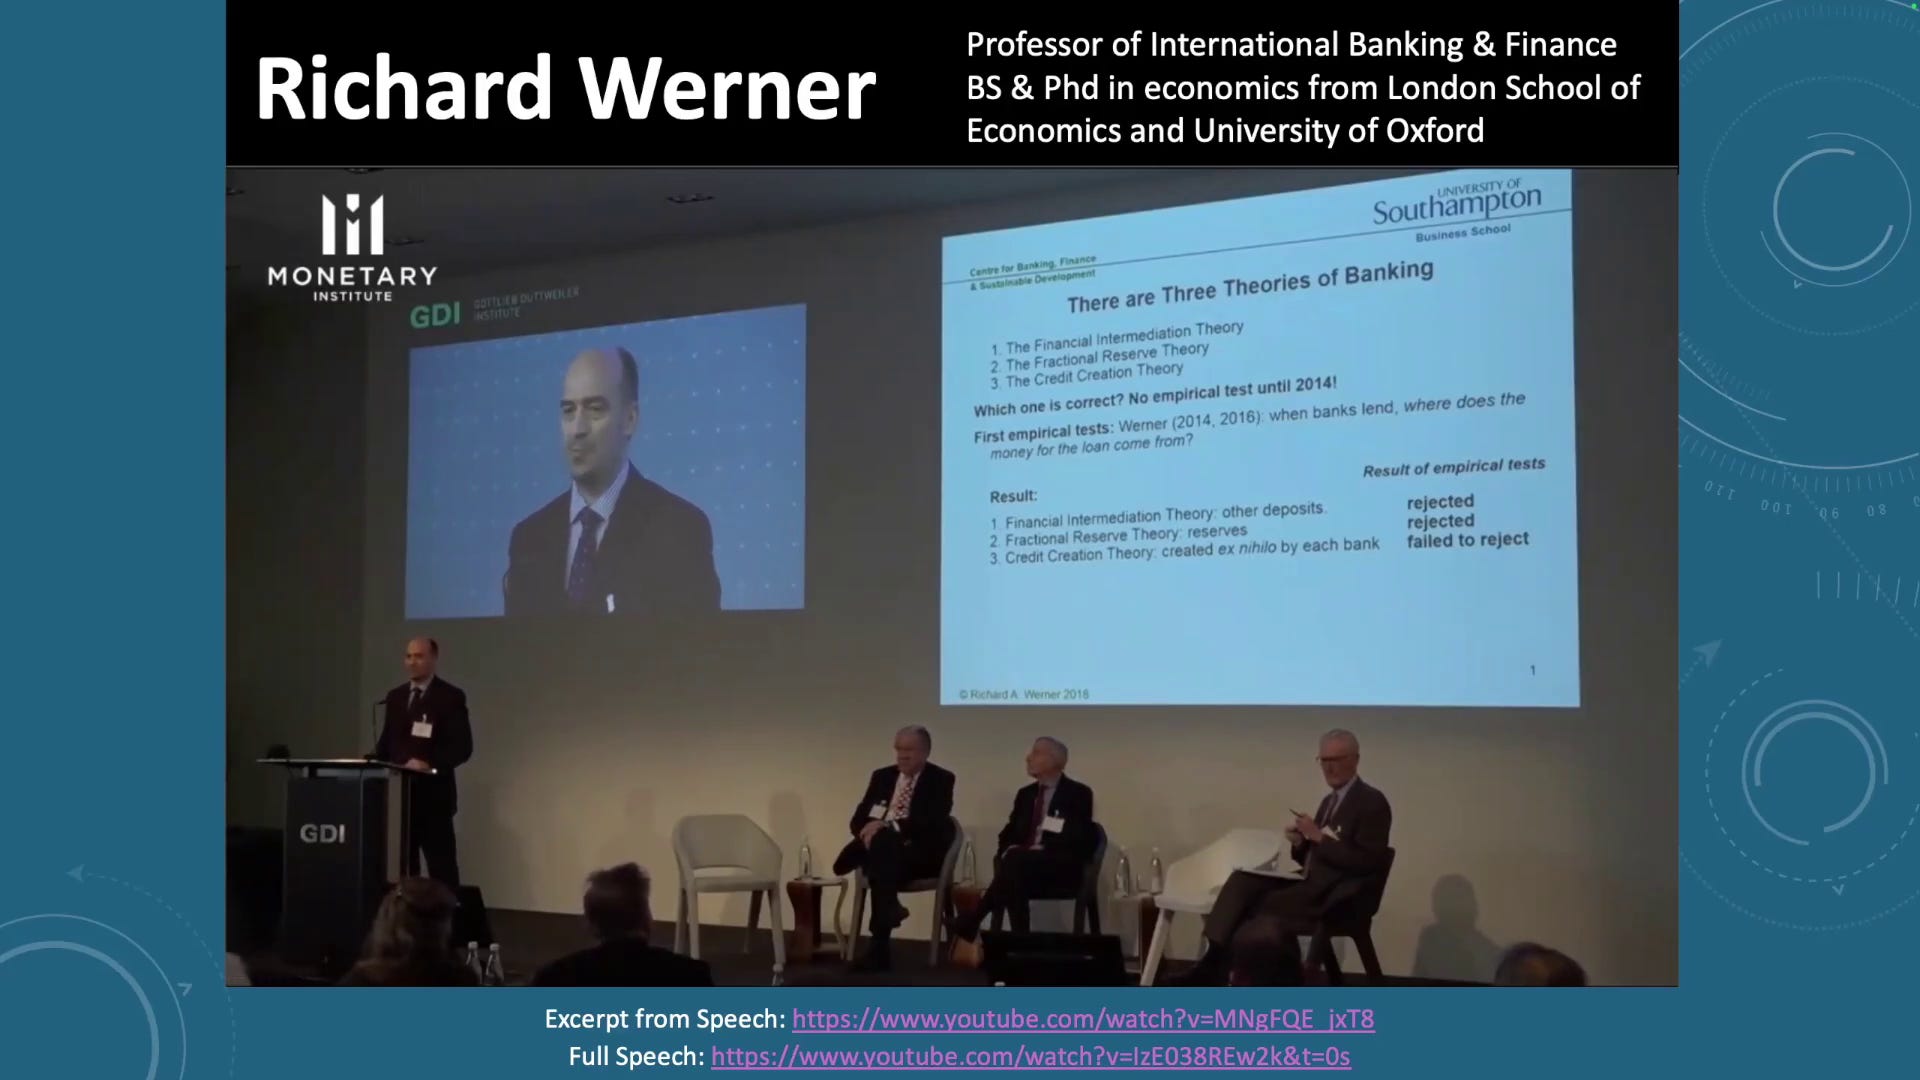
Well, let’s figure it out. Let’s do an empirical test. So I did this and published – 2014 and 2016 – two papers. The conclusion is the financial intermediation theory was rejected. Banks are not financial intermediaries. You may have heard of the fractional reserve theory, slightly older. That one was also rejected. It says that, you know, banks lend money out of reserves, and they don’t.
Financial intermediation theory says they lend out of other people’s deposits, and they don’t. So the oldest theory – that was the one that was found to be correct – and that’s the credit creation theory, which was known 100 years ago, which is why one of the papers is called ‘Lost Century in Economics.’ Banks create money out of nothing through the process of credit creation.
So banks are special. They create the money supply – 97% in most countries of the money supply – out of nothing, through the process of what’s called credit creation. Now, the recognition of bank credit creation is a game changer to solve many of the world’s problems, such as: the recurring banking crisis can be prevented, unemployment can be solved, business cycles, underdevelopment, depletion of finite resources – all these problems can be solved by utilizing the power of bank credit creation.”
So that just wraps up our section on the accounting of where are banks getting the money that they’re lending. And I hope that that was, if you just check in with yourself real quick, it’s something that you found empowering to at least be exposed to and have some sense of where you could get more information about that.
So this last section for today is much quicker. It’s answering the question of, “Well, if banks can create money, what limits them from being able to just expand their balance sheets infinitely?”
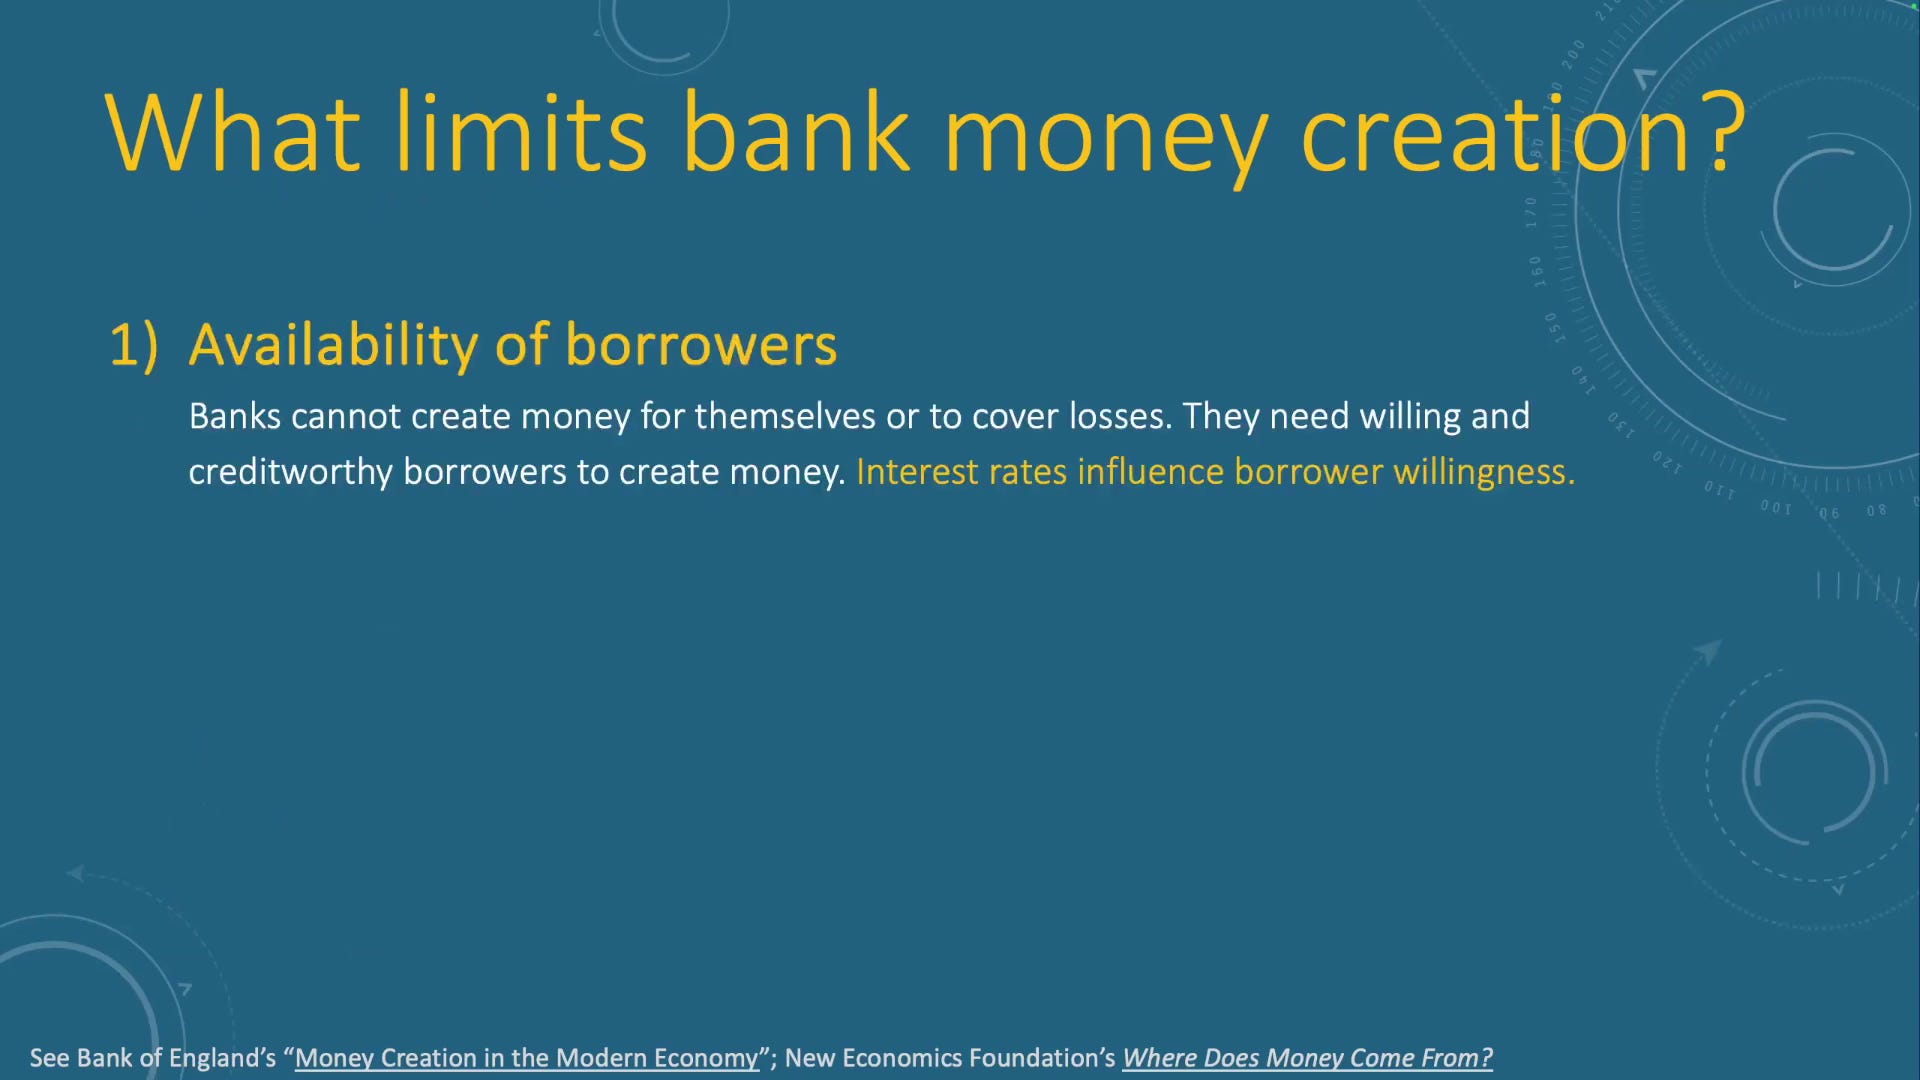
So, there are some limits on bank money creation. The first and most important one is the availability of borrowers.
Banks cannot just create money for themselves or to cover losses. They need willing and credit-worthy borrowers to create money. And if you hear in the monetary policy conversations about “What is the central bank going to do in terms of setting interest rates?” What they’re trying to do there is influence the amount of available borrowers to banks by lowering or raising the interest rate.
So the idea is that if they raise the interest rate a bunch, then many people will decide, “You know, this isn’t a good time to borrow. I don’t want to borrow right now because the interest rates are so high.” And that reduces the availability of borrowers for the banks, and thereby it reduces the amount of money that they can create. This is what they’re talking about when they say, “We’re going to raise interest rates in order to slow the economy down.” This is what they’re talking about.
So, this is the primary way that monetary policy actually influences the money supply. It is not through the fractional reserve or money-multiplier story, that the central bank is controlling the money supply directly through the amount of reserves that it has provided to the banking sector. And so, yeah, this is the most important limit.
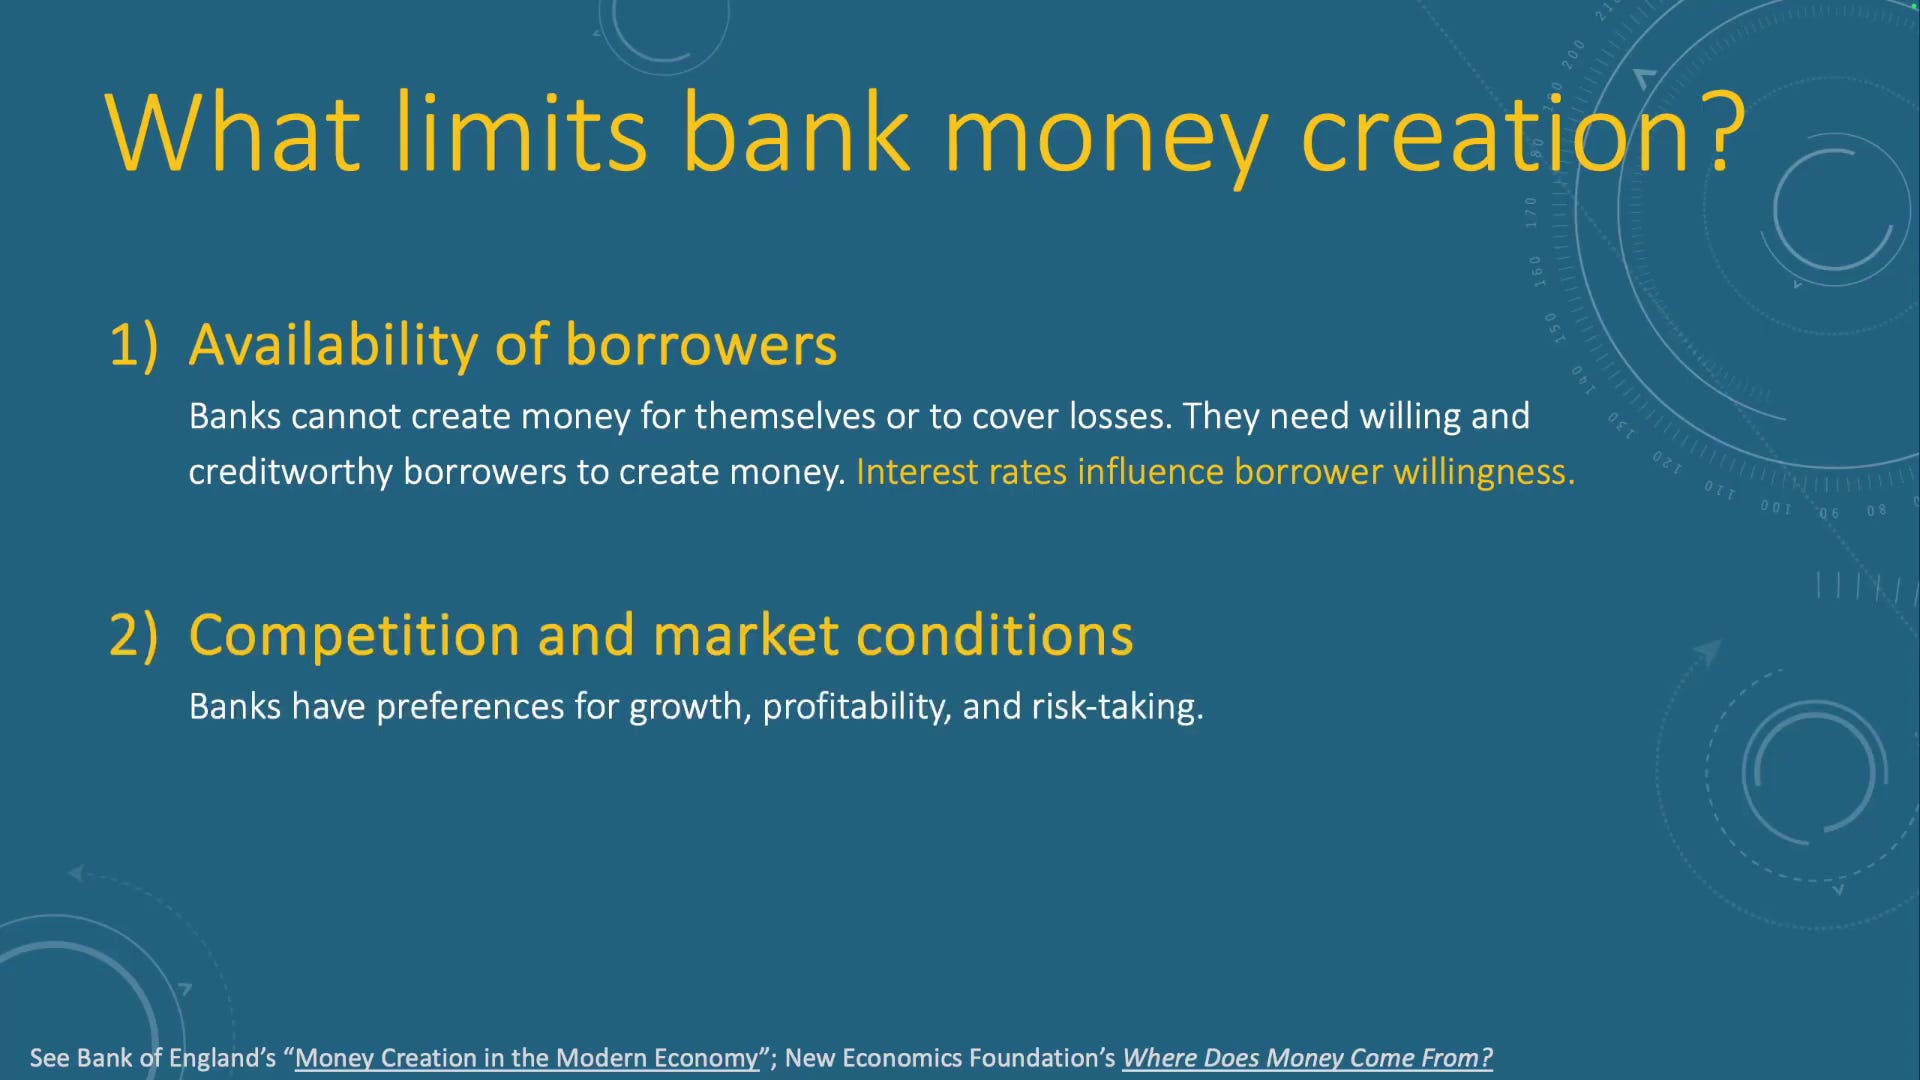
The second one is bank competition and market conditions. So, if banks are feeling like, “Gosh, the market’s really risky right now. There’s tariffs and other things that we don’t know how they’re going to play out,” they might decide to play it conservative and stop lending even to businesses that are very bankable and that have been profitable in the past and will likely be profitable in the future. Or they may have other decisions about profitability where they’re not going to lend to low-income communities or to rural communities because they can make a lot more money lending to hedge funds on Wall Street.
So these are the types of things that can direct money creation in ways that are limited for different communities and markets.
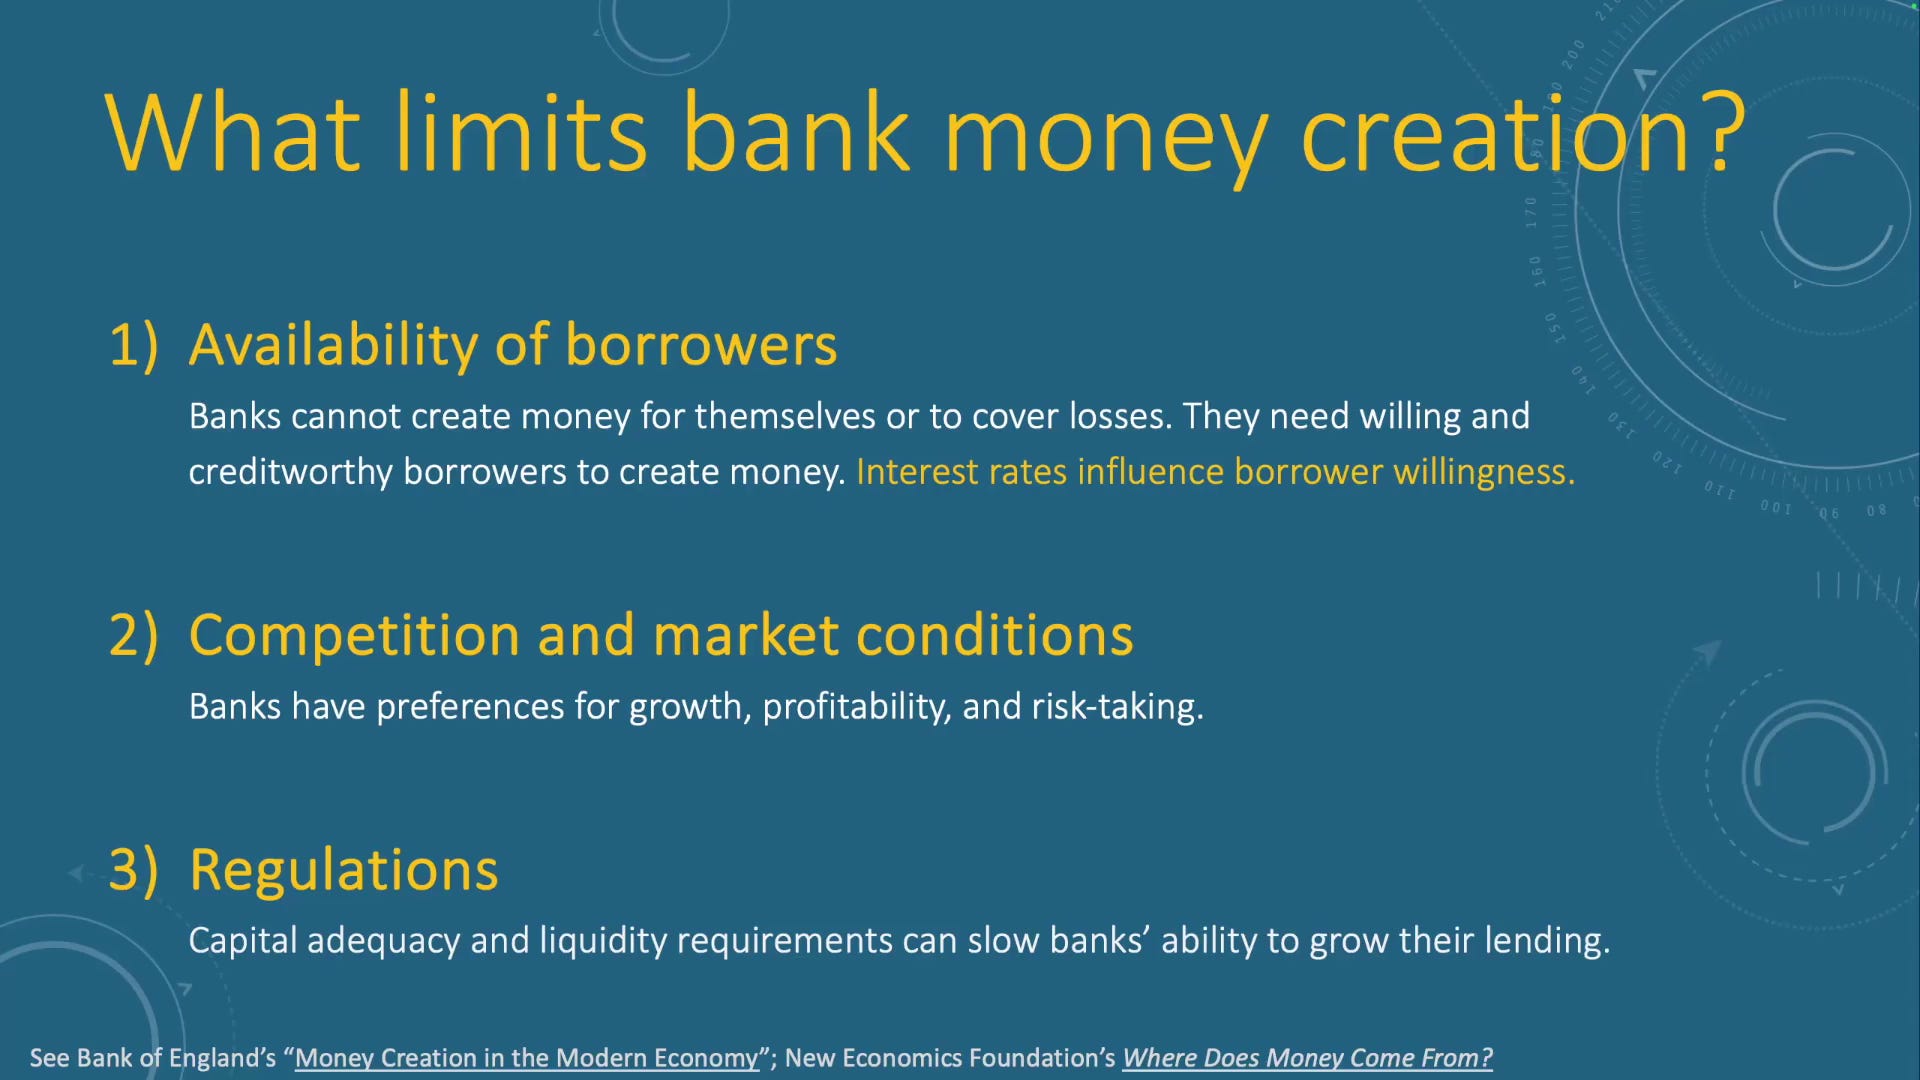
Another thing is regulations. So there are some rules established by our governments and enforced by central banks, such as the capital adequacy and liquidity requirements. And I’m not going to go into what those are right now, but the important thing to know about them is that functionally what they do is they slow individual banks’ ability to grow their lending but don’t actually stop the banking sector as a whole from being able to grow its lending.
Though the prior two considerations are really the brake on the banking sector as a whole. And really what those regulations, kind of the biggest function that they serve or one of the most important impacts of them, is that they have the effect of keeping small banks small and big banks big. So they’re regulations that I think need to be looked at from a different angle.
Importantly, there are two things that are taught in the textbooks about what limits bank money creation that are not actually limits on bank money creation. So, the first one is this idea that banks are limited by how much deposits they can attract. And here’s a paper by the Federal Reserve saying, “Private money creation by banks enables lending to not be constrained by the supply of cash deposits.”
And by the way, this is a major fault of modern macroeconomic modeling and is one of the reasons why economists didn’t predict the 2008 crisis. They assumed that the amount of lending is equal to the amount of deposits or is controlled by the amount of deposits that are available to banks to lend. And the only economists that reliably predicted the 2008 crisis were using accounting models that actually understood correctly the source or the ability of banks to lend via their accounting.
The other thing that does not limit banks’ ability to lend is the quantity of central bank reserves. As it says here in that Bank of England paper, “In no way does the aggregate quantity of reserves directly constrain the amount of bank lending or deposit creation.” In fact, central banks supply the banking sector with as much reserves as the banking sector wants to settle transaction between themselves.
It’s a little bit like the cash. Central banks provide to the banks as much cash as the banks want in order for their customers to be able to settle payments between themselves. The central bank does the same thing for banks so that they can settle payments with each other, but those payments are called reserves rather than cash. And they exist only as electronic records at the central bank.
So in the next session, we will look at the law of like, “How does this work in law? What is it that makes banks IOUs money?” And then also we’ll talk about “Why would governments do this? Why would they choose to set it up this way?”
Thanks for the question, Brian. It's helpful to know that my explanation wasn't satisfactory. I thought I had done so in comparing the story of banks taking in deposits and setting them aside vs banks creating money purely as credit creation. The fractional reserve story says that banks lend out of deposits by setting aside a portion and lending out the rest. That is not how it works, and therefore the fractional reserve story is not an accurate description of how banks create money.
I'm guessing what I needed to further do is address the common confusion that comes into play with the capital adequacy rule. The capital adequacy rule says that a bank cannot hold assets (loans and bonds, primarily) greater than a percentage of their "capital" (the ratio is roughly between 8-13%, so is often shorthanded as 10%, but that's not correct). Capital is not deposits. It is the "net wealth" of the bank. It is a residual of the difference between a bank's assets and its liabilities. For big banks, it is best understood as a measure of the profits the bank has retained rather than paid out to its shareholders. The capital adequacy rules imposts no limits on bank lending in relation to deposits, at all.
In countries that still have reserve requirements (mainly in the Global South), the reserve requirement does not work the way that the fractional reserve story says, either. The reserve requirement says that a bank must hold central bank reserves equal to 10% of deposits. It doesn't say a bank must hold back 10% of its deposits from being lent out while it lends out the rest. So, banks can (and do) lend by creating fresh deposits and then look for reserves later, often by buying or borrowing them from the central bank or other banks. They don't use deposits to do that buying and borrowing, either. Deposits already on a bank's books are useless for getting central bank reserves. That is because deposits are a debt of the bank, not an asset. The central bank and other banks don't want to sell reserves to a bank in exchange for their debts! They want to get assets in exchange. So, banks buy/borrow reserves by trading away the loans and bonds (assets) on their books, not deposits.
Importantly, the reserve requirement never actually limited the banking sector's ability to lend, as a whole. The central bank always provides enough reserves to meet banks' need to settle transactions with each other. However, it can increase the cost banks incur when holding loans above a 10% ratio to deposits, since they will have to rent reserves from the central bank to stay in compliance with the reserve requirement. This can deter individual banks from making loans, but as I said, it doesn't limit the ability of the banking sector, as a whole, to grow lending.
Thanks for the question, Brian. Let me know if that helped!
Nice video! You say that the fractional reserve banking story isn't accurate, but don't really explain the reason. Can a bank with $10,000 in deposits make $10,000,000 in loans? Why or why not?