

This presentation is part of a multi-part Money Insights series. In this session, I answer the questions, “Why is it legal for banks to create money? What is the law that makes that possible?” In the following presentation, I explain the politics that led governments to outsource money creation to banks. In previous presentations, I’ve covered:
the history of today’s national money systems that are based on bank money creation
the accounting by which banks newly create 100% of the money they lend.
My presentations always build on scholarship produced by experts in law, banking, economics, history, and more. An annotated list of the scholarship upon which this video is based can be found below the video.
Jump to the…
Video recording
Transcript & Slides
In today’s session, we’re going to talk about how banks create money, part two. Last time, we talked about the accounting and the limits to bank money creation. Today, we’re going to talk about the laws and the politics that enable this way of money creation.
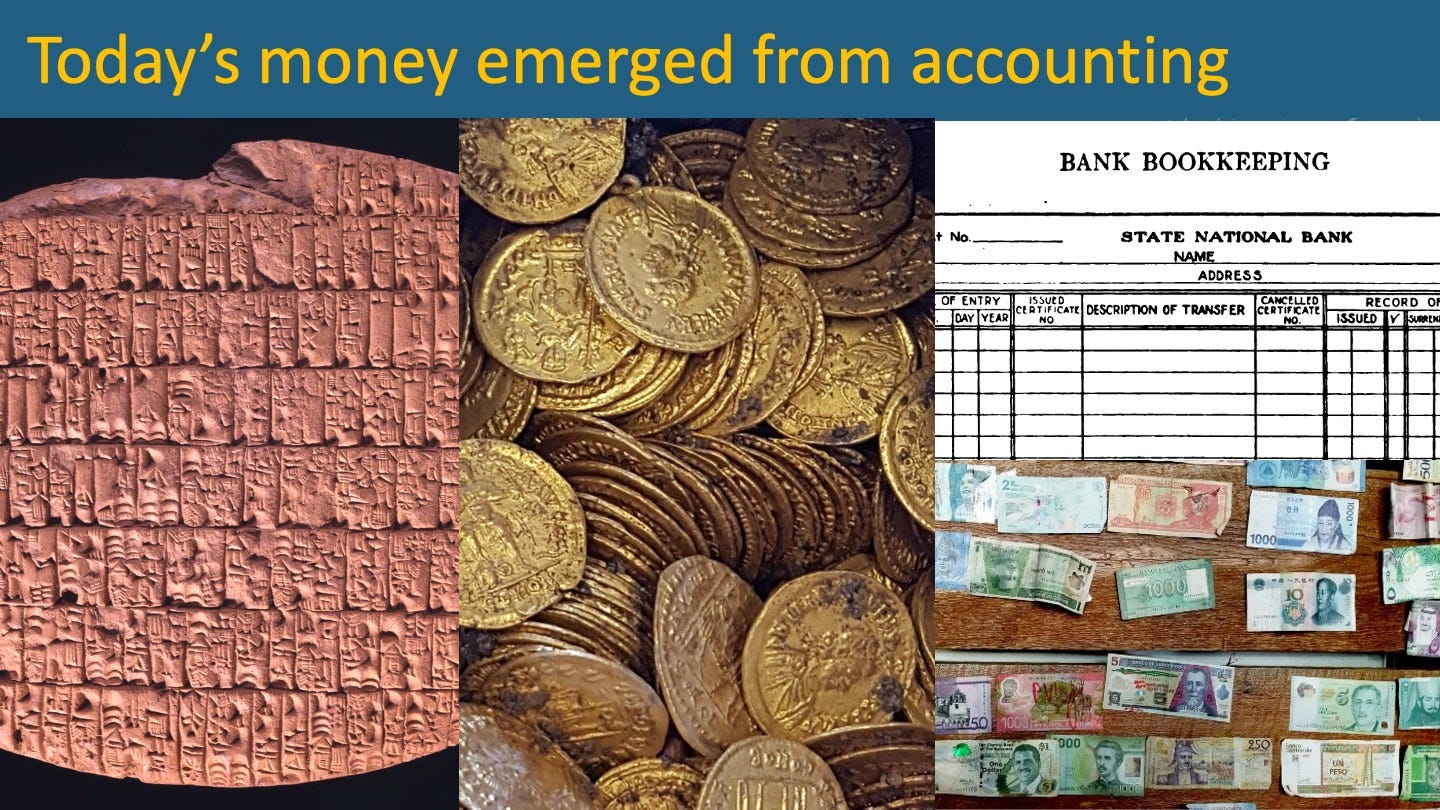
And just as a reminder, in our first session, we talked about how today’s money system emerged from accounting, and then it evolved into a physical format in the in the form of coins, and then it evolved from there into a hybrid of an accounting based system and a paper or physical based system, where banks are the accountants of the money system and also the creators of the money system through that accounting.
And what’s ahead is that we’re going to look at “how is it legal? How is this legal? Why did governments give banks the permission to create money, and what is the functional logic, or rather the politics of this system and how it came to be?”
So just as a reminder, we’re looking at all of this because there are a number of scholars today who are telling us that the way money is created, today, is intensifying economic hardships, social issues and environmental concerns.
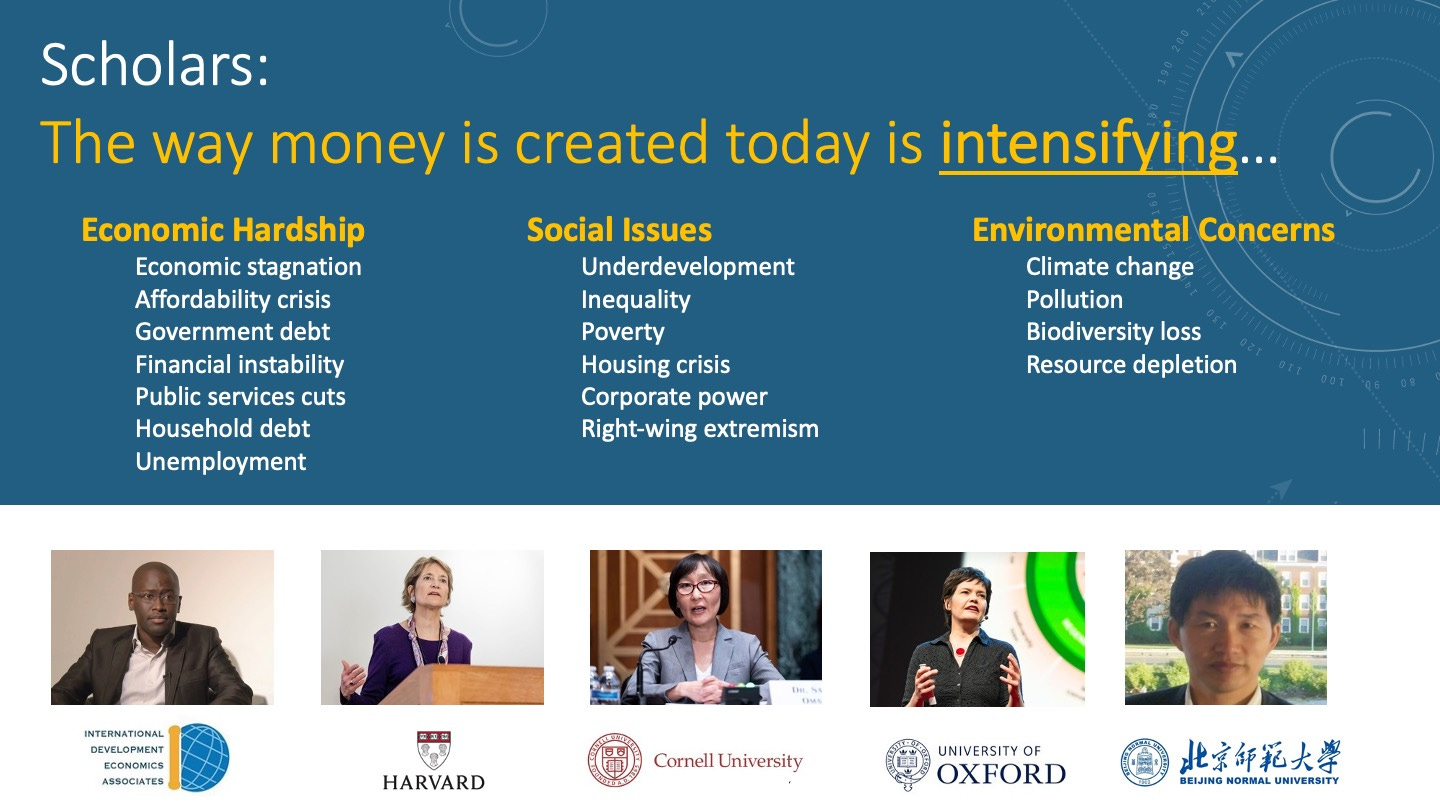
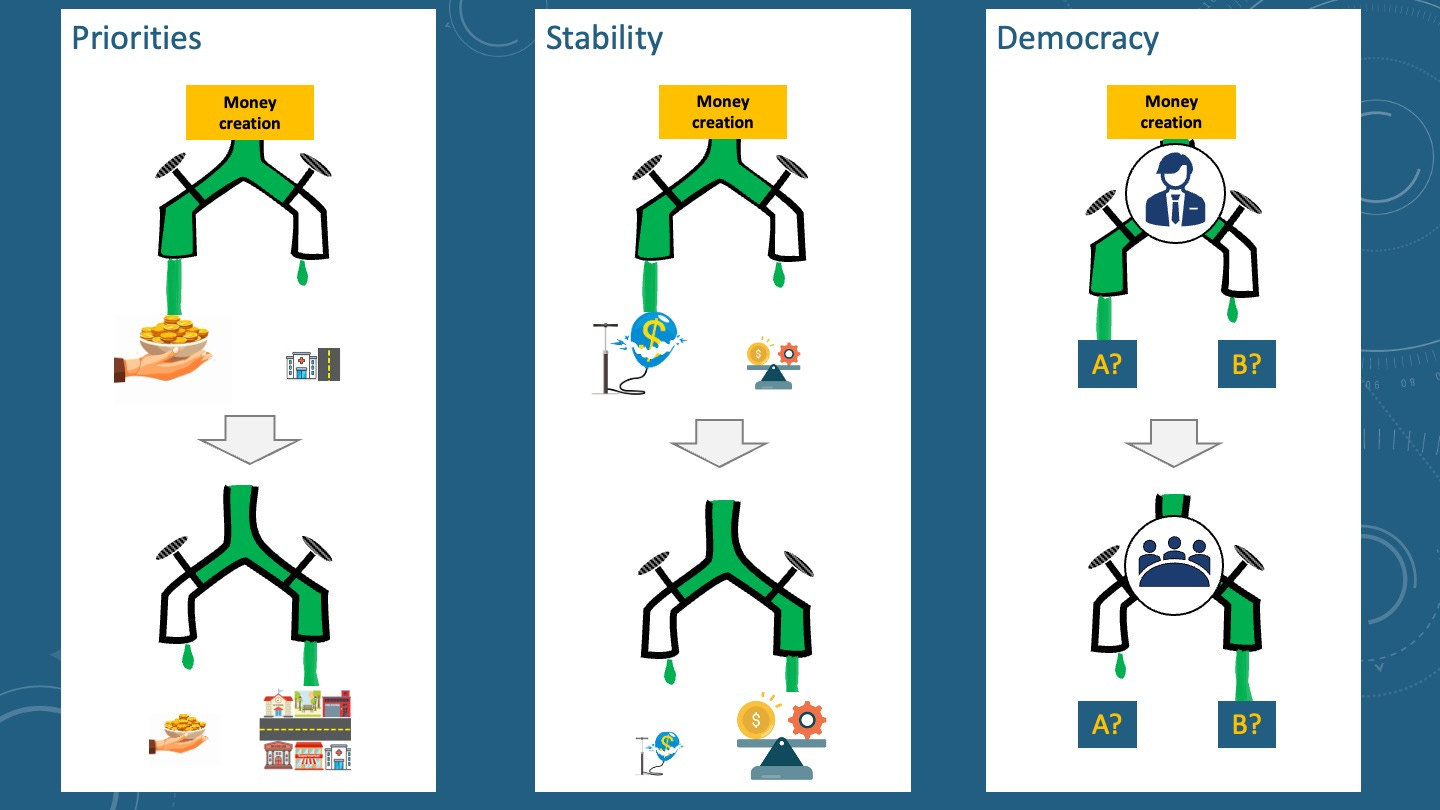
They’re pointing to things like the way that our current bank money creation system channels money into high net worth households and corporations and builds significant private wealth and inequality, whereas it could be and has been in the past, primarily been flowing into public investment, public infrastructure, schools and hospitals and so on, and building public wealth. Or they point to this system as creating booms and busts. Saying, “there are other ways that it could be done that would fund, more significantly, the real productive economy of farms and factories and so on, and produce a more stable economic situation.” Or pointing to democracy and saying, “Look, in the current bank money system, it’s the loan officers and managers of banks that are making decisions about what receives investment in the economy, and that there are other ways of doing it that are more democratic and transparent.”
So the goal of these videos is not to tell you what to think about it or how to think about it, but rather to help you understand how the system works and how it came to be this way so that you can judge for yourself.
And as always, see the video notes for descriptions of the large amount of scholarship that these presentations build on.
Again, last time we did the accounting and limits, today, we’re going to do the law and politics. [NOTE: the politics piece was separated into a second video here.]
So how is it legal for banks to create money?
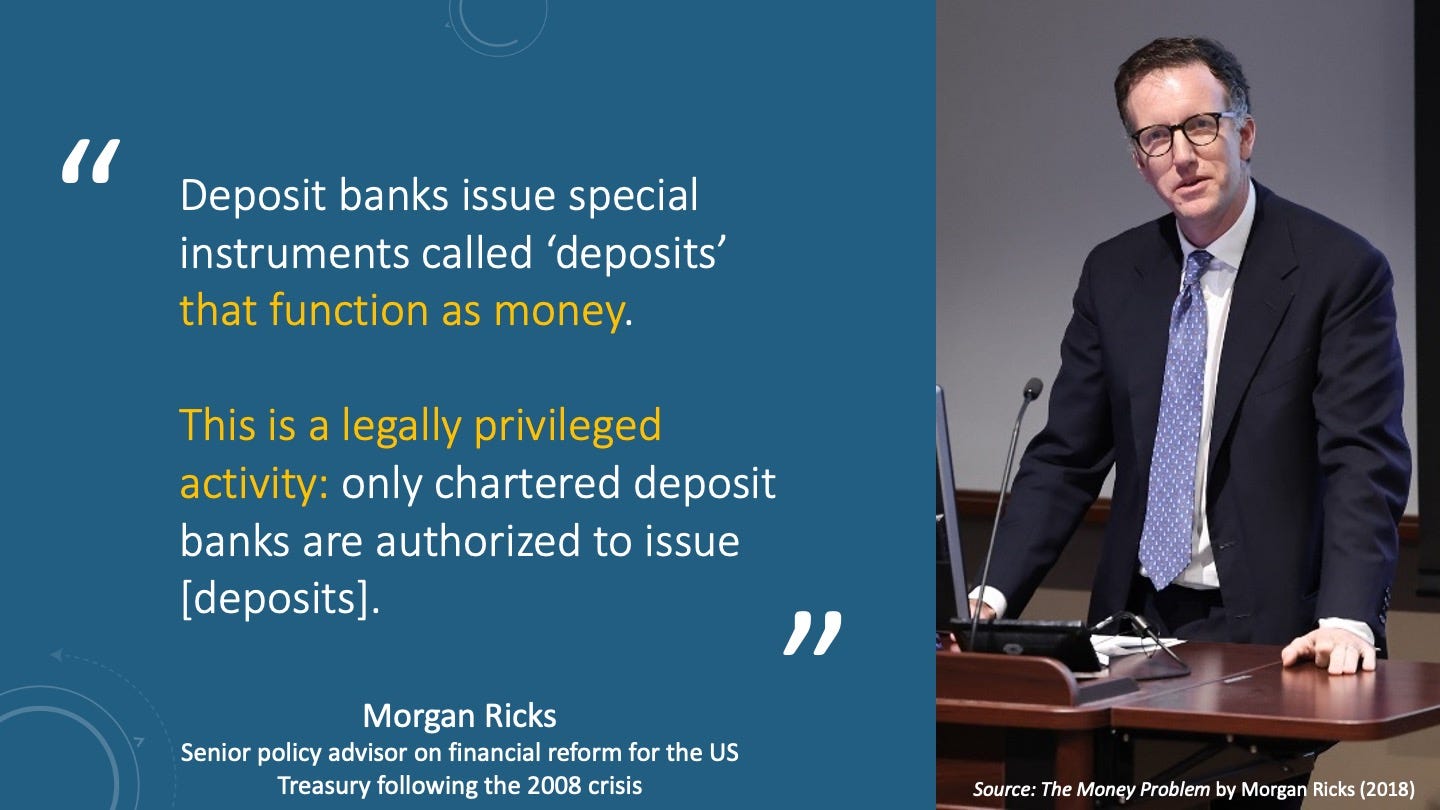
Morgan Ricks was the senior policy advisor for the US Treasury during the post-2008 crisis Dodd Frank banking regulation negotiations. He’s also, today, one of the leading banking law scholars in the country. And he puts it this way. He says, “deposit banks issue special instruments called deposits that function as money. This is a legally privileged activity. Only charter deposit banks are authorized to issue deposits.” I just want to hold up two parts to that, which is (1) deposits function as money and that (2) this is a legally privileged activity. Okay, so starting with the legally privileged activity part…
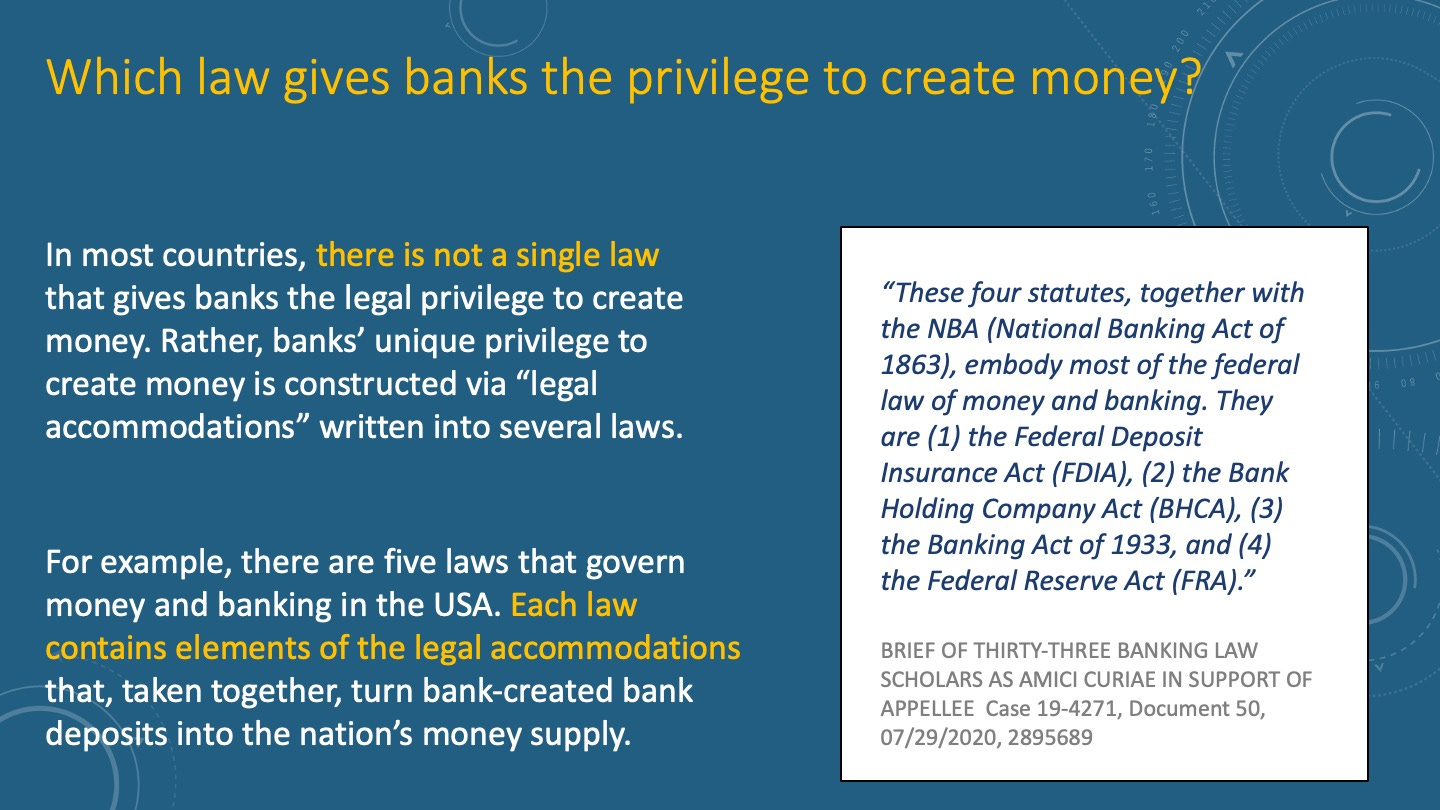
In most countries, there is not a single law that gives banks the legal privilege to create money. Rather, banks’ unique and exclusive privilege to create money is constructed via what some legal scholars call “accommodations” written into several laws. For example, there are five laws that govern money and banking in the United States. Each law contains elements of these legal accommodations that, taken together, turn bank created bank deposits into the nation’s money supply. So that’s what Morgan Ricks was talking about when he’s saying bank deposits function as money. These accommodations create a situation in which bank deposits function as the nation’s money supply. And this quote on the right is from a law a brief of 33 banking law scholars in a federal court. They were explaining to the courts how our banking law and money creation works.
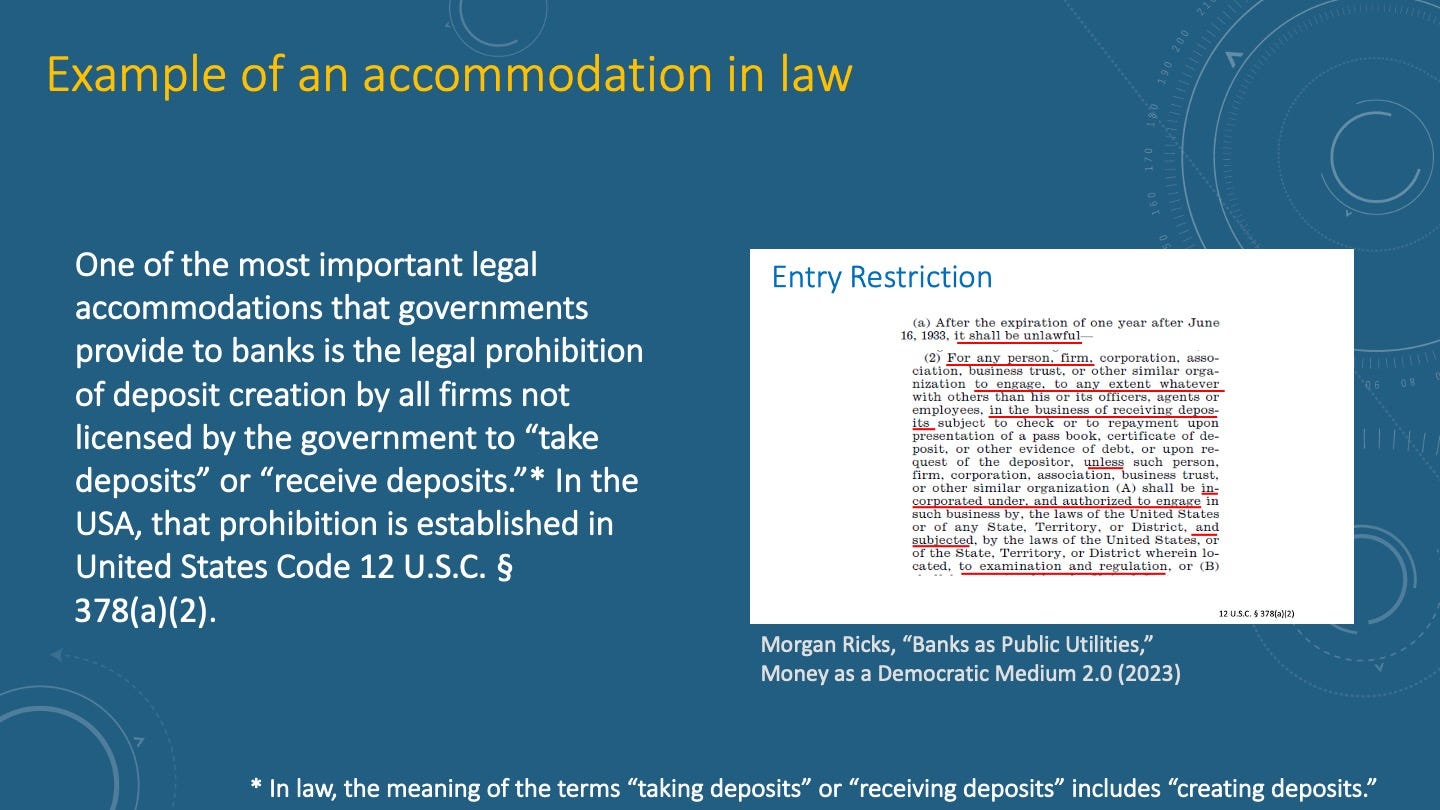
So here’s just an example of one of those accommodations. I’m going to make the picture on the right bigger to make it so that you can actually try and read. In just a second. But what it provides is one of the most important legal accommodations that governments provide to banks, and that is the legal prohibition of deposit creation by all firms [that are] not licensed by the government to “take deposits” or “receive deposits.” It’s important to note that in the law, “taking deposits,” “receiving deposits,” “creating deposits,” and “issuing deposits” are all included in the same “deposit taking” definition. So in the US, that prohibition, that exclusion against everyone else, taking, receiving, creating deposits, except for commercial banks and credit unions and savings banks is established in Title 12, United States Code, Section 378, Subsection a, Paragraph 2.
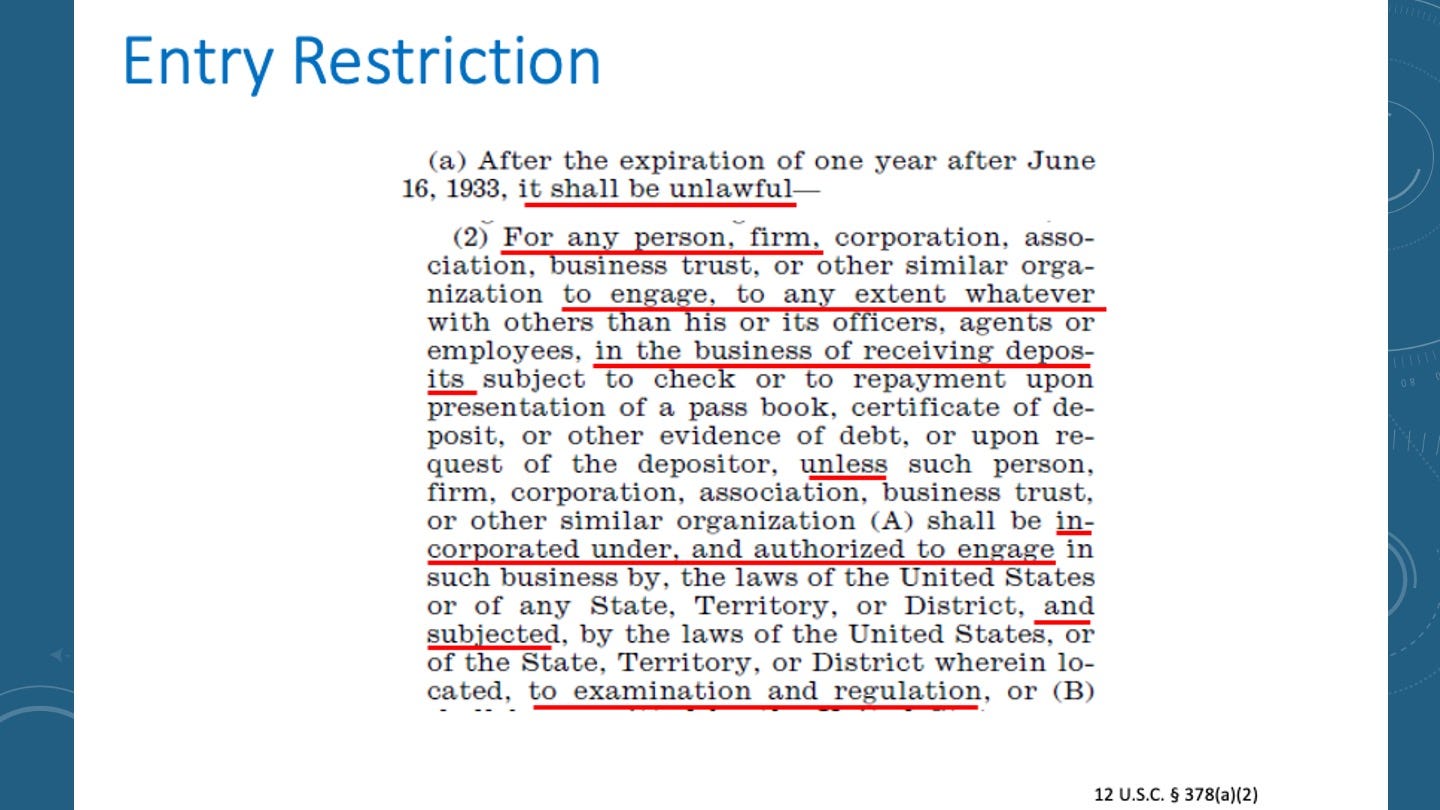
Let’s just take a look at that so you can see how [not] easy it is to even spot one of these legal accommodations. This is Morgan Rick’s underlining. He gives this slide in his presentations to just make this exact point. If you were to try and read this entire sentence, you would struggle. So he’s underlined in red the parts that make somewhat a clear logic out of it. “It shall be lawful for any person firm to engage to any extent whatever, in the business of receiving deposits, unless incorporated under and authorized to engage and subjected to examination and regulation.” In other words, it’s unlawful for anybody that is not regulated to take deposits to issue deposits, right? If you don’t have a banking license, you’re not allowed to create deposits. That’s what that very complex sentence is saying.
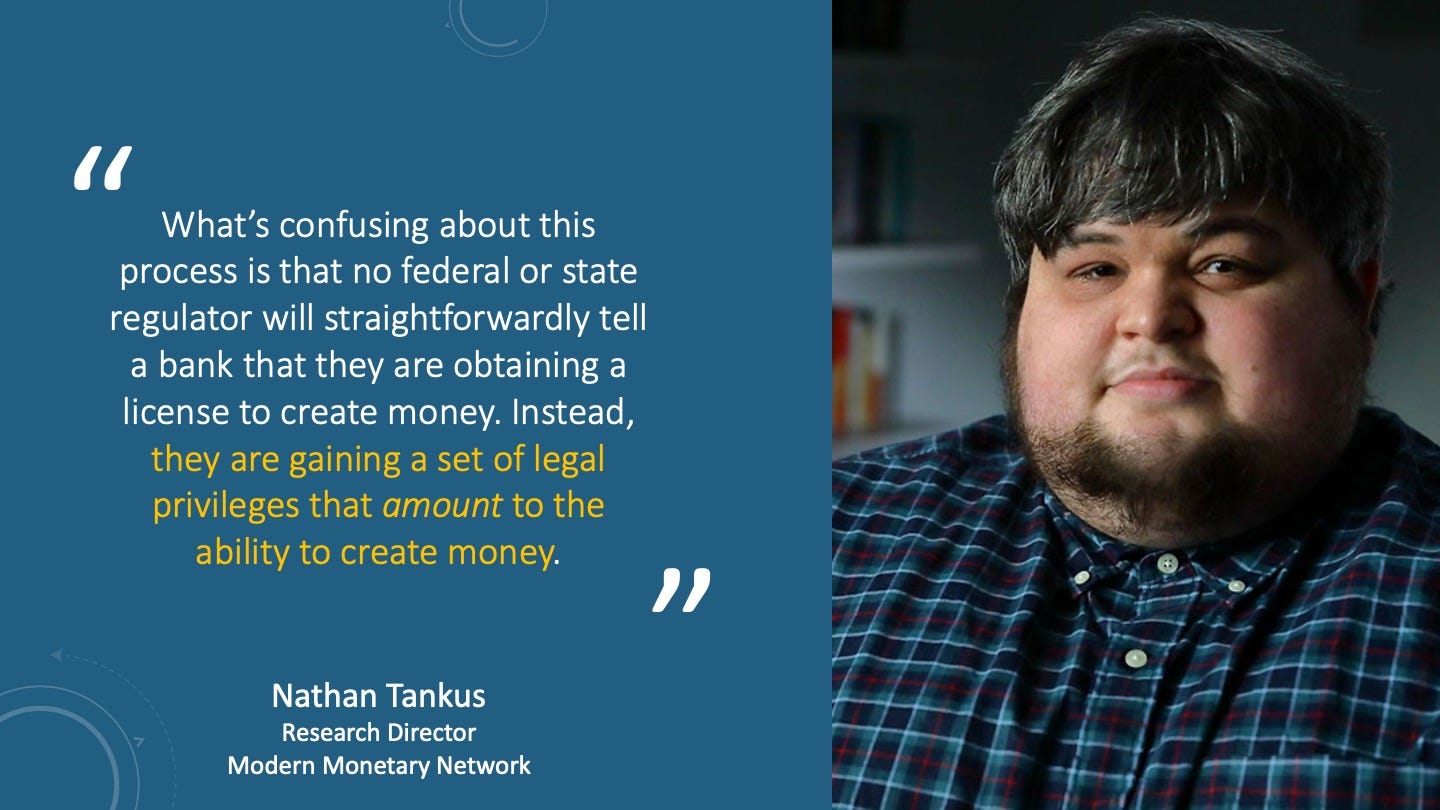
The research director at the modern monetary network, Nathan Tankus, explains it this way. Nathan says, “What’s confusing about this process is that no federal or state regulator will straightforwardly tell a bank that they are obtaining a license to create money. Instead, they are gaining a set of legal privileges that amount to the ability to create money.” So what is Nathan talking about?
These legal accommodations. These privileges that turn bank deposits in the money in most nations, the accommodations include several things that the government chooses to do, and I’m going to group these accommodations into two categories, those that precede the adoption of central banking and those that follow the adoption of central banking. And this is important because most people think that central banking and the bank money creation system, fiat money that’s created by banks, is a synonymous invention with central banking.
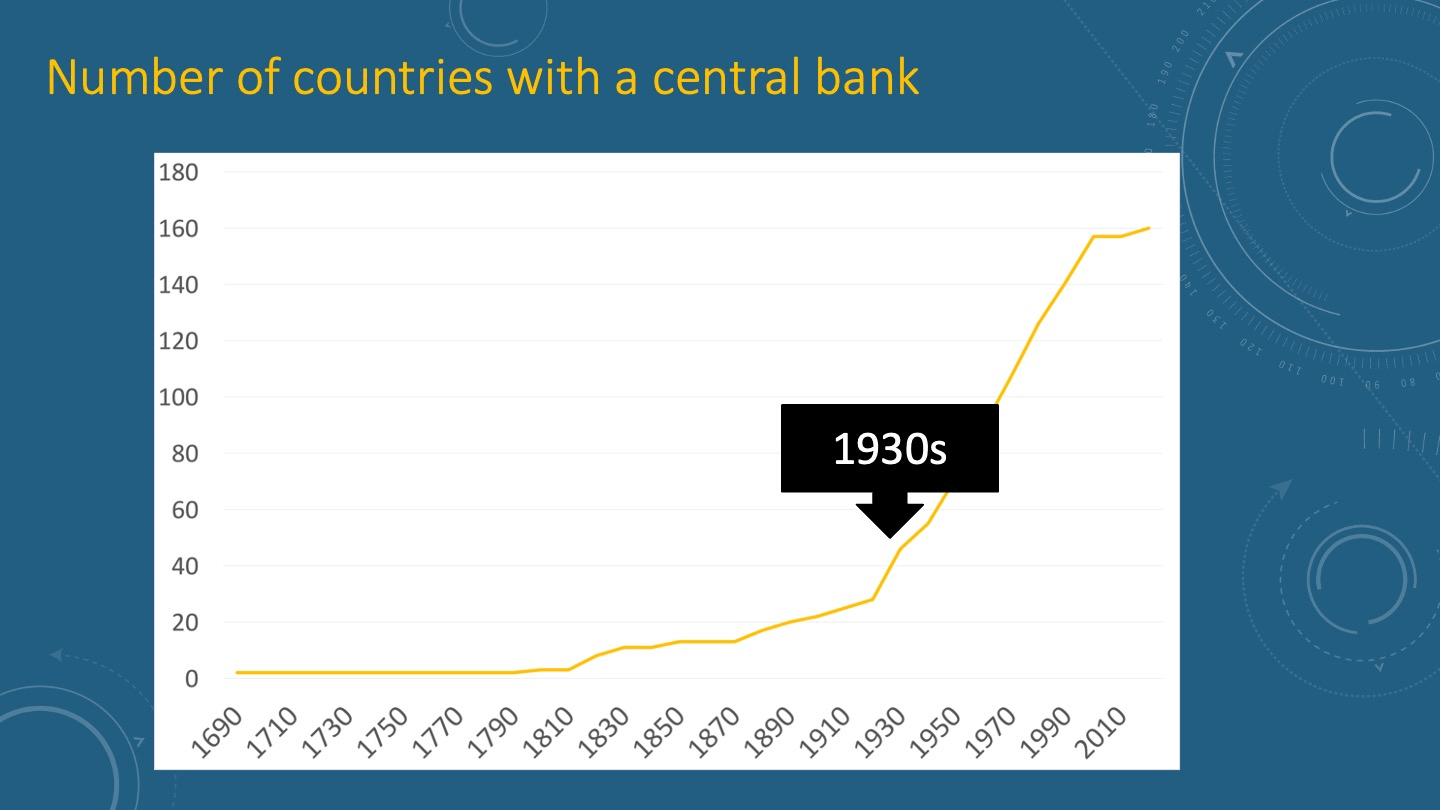
But in fact, until the 1930s only about two dozen countries in the world, had a central bank, while already most countries in the world were using this bank money creation system. Many started to implement them in the 1930s in response to the Great Depression, when they realized that it might be a good thing to have an institution that can strongly regulate the banking sector. It really wasn’t until the 1940s and 1950s that most of the world ended up with a central bank. This wave of central bank formations occurred as countries gained their independence from colonial powers and sought to assert their sovereignty by regulating banking within their territories.
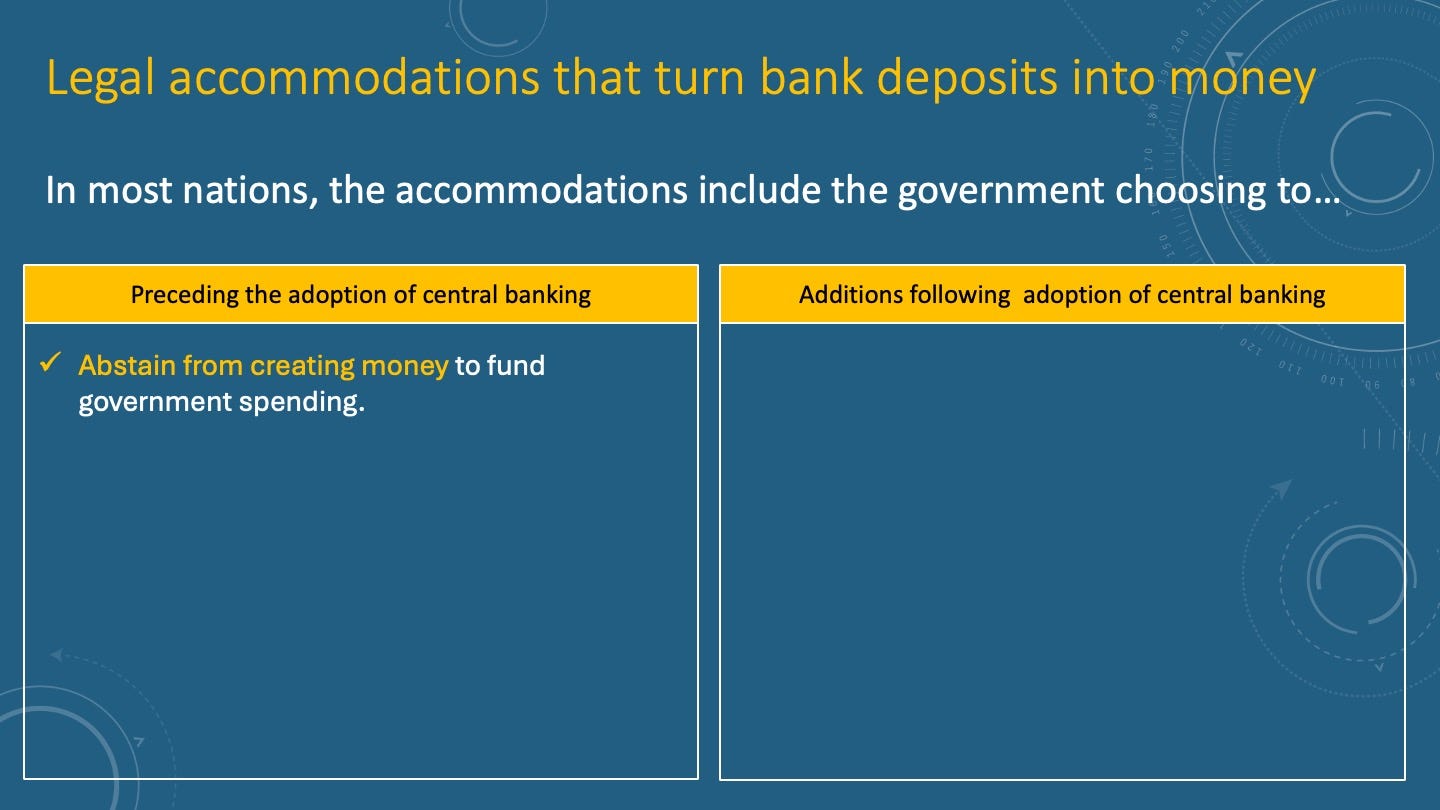
But let’s start with the ones that preceded the adoption of central banking. So the first one is that governments choose to abstain from creating money to fund their government spending. And here’s what I mean by that, using the Constitution of the United States, just to take one country as an example. But this is quite similar in many other countries.
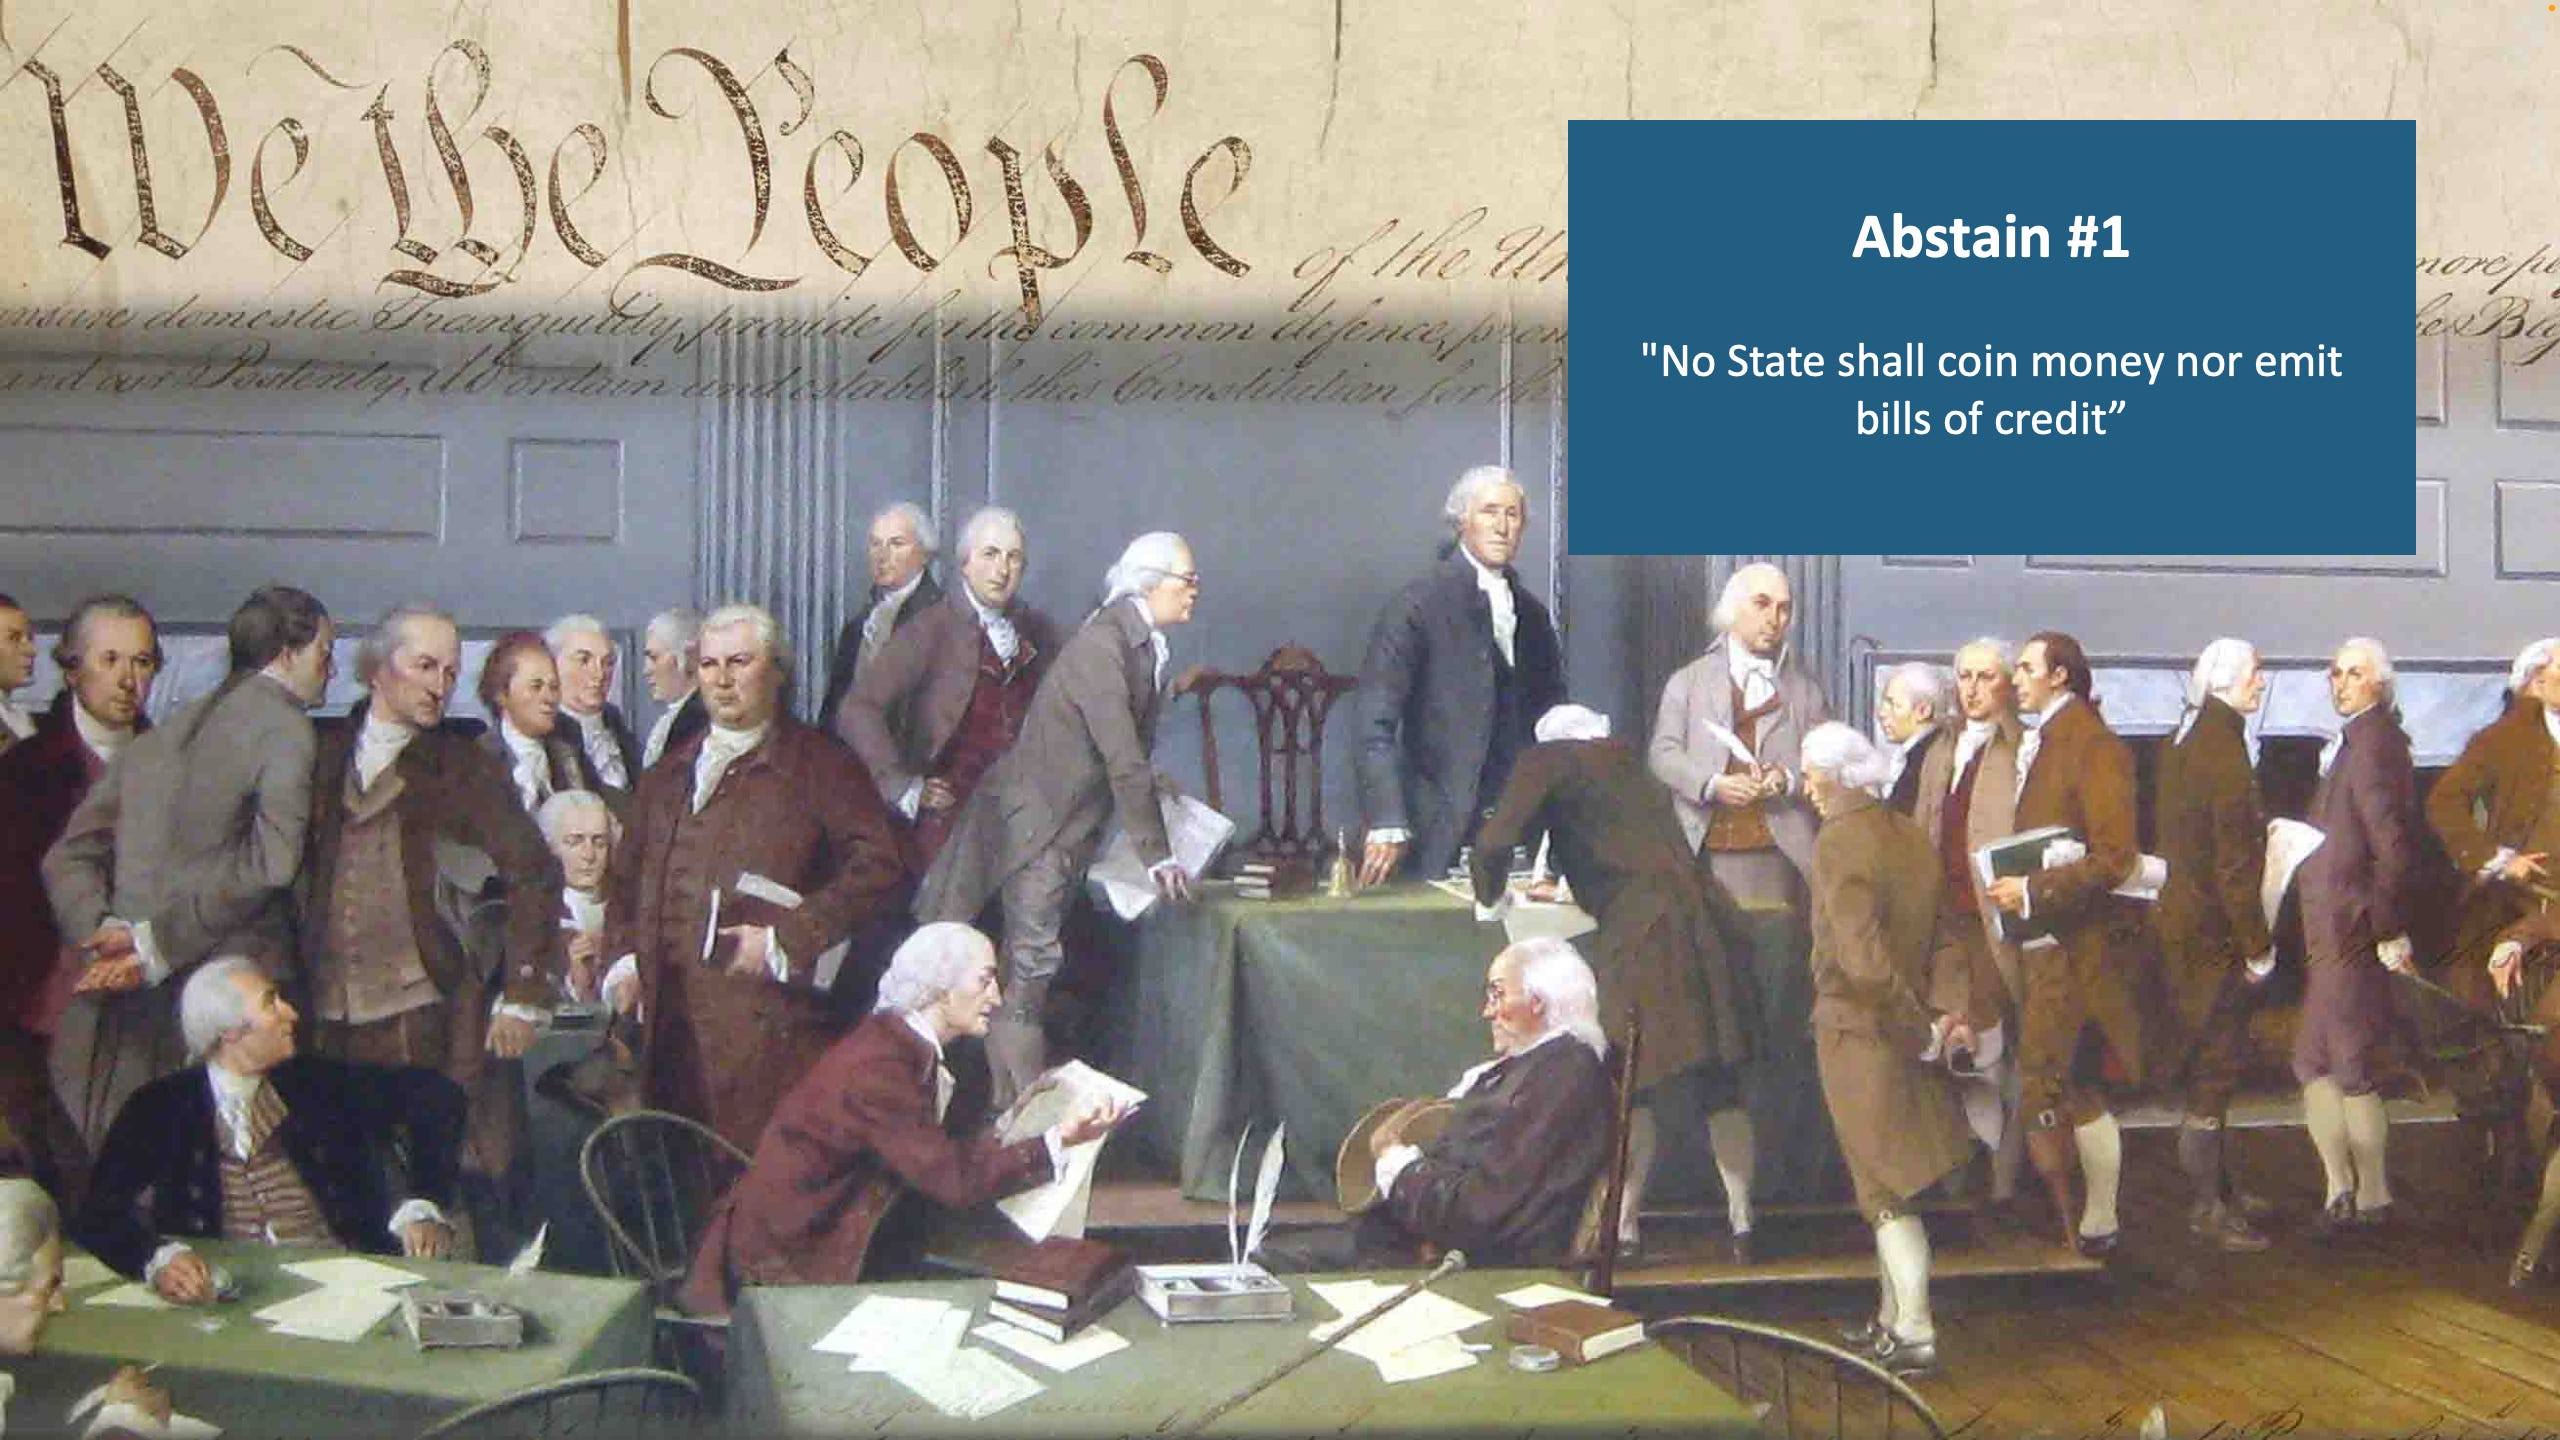
Abstentions like this in the Constitution says, “No State shall coin money nor emit bills of credit.” Now, what’s happening here is that the federal government, the Constitution, the United States Congress, is forbidding states governments from issuing and spending money into circulation. That’s something that had been possible under the Articles of Confederation. The previous federal government charter. and it was something that actually was not wanted by the billionaire class of their day because states, in particular Rhode Island, were using the privilege to create money to to to pay off their debt with debt-free money. And the bondholders didn’t like this, because that meant that their bonds would be paid off and governments wouldn’t need to create new bonds with for them to hold and earn 6% interest on without doing any work.
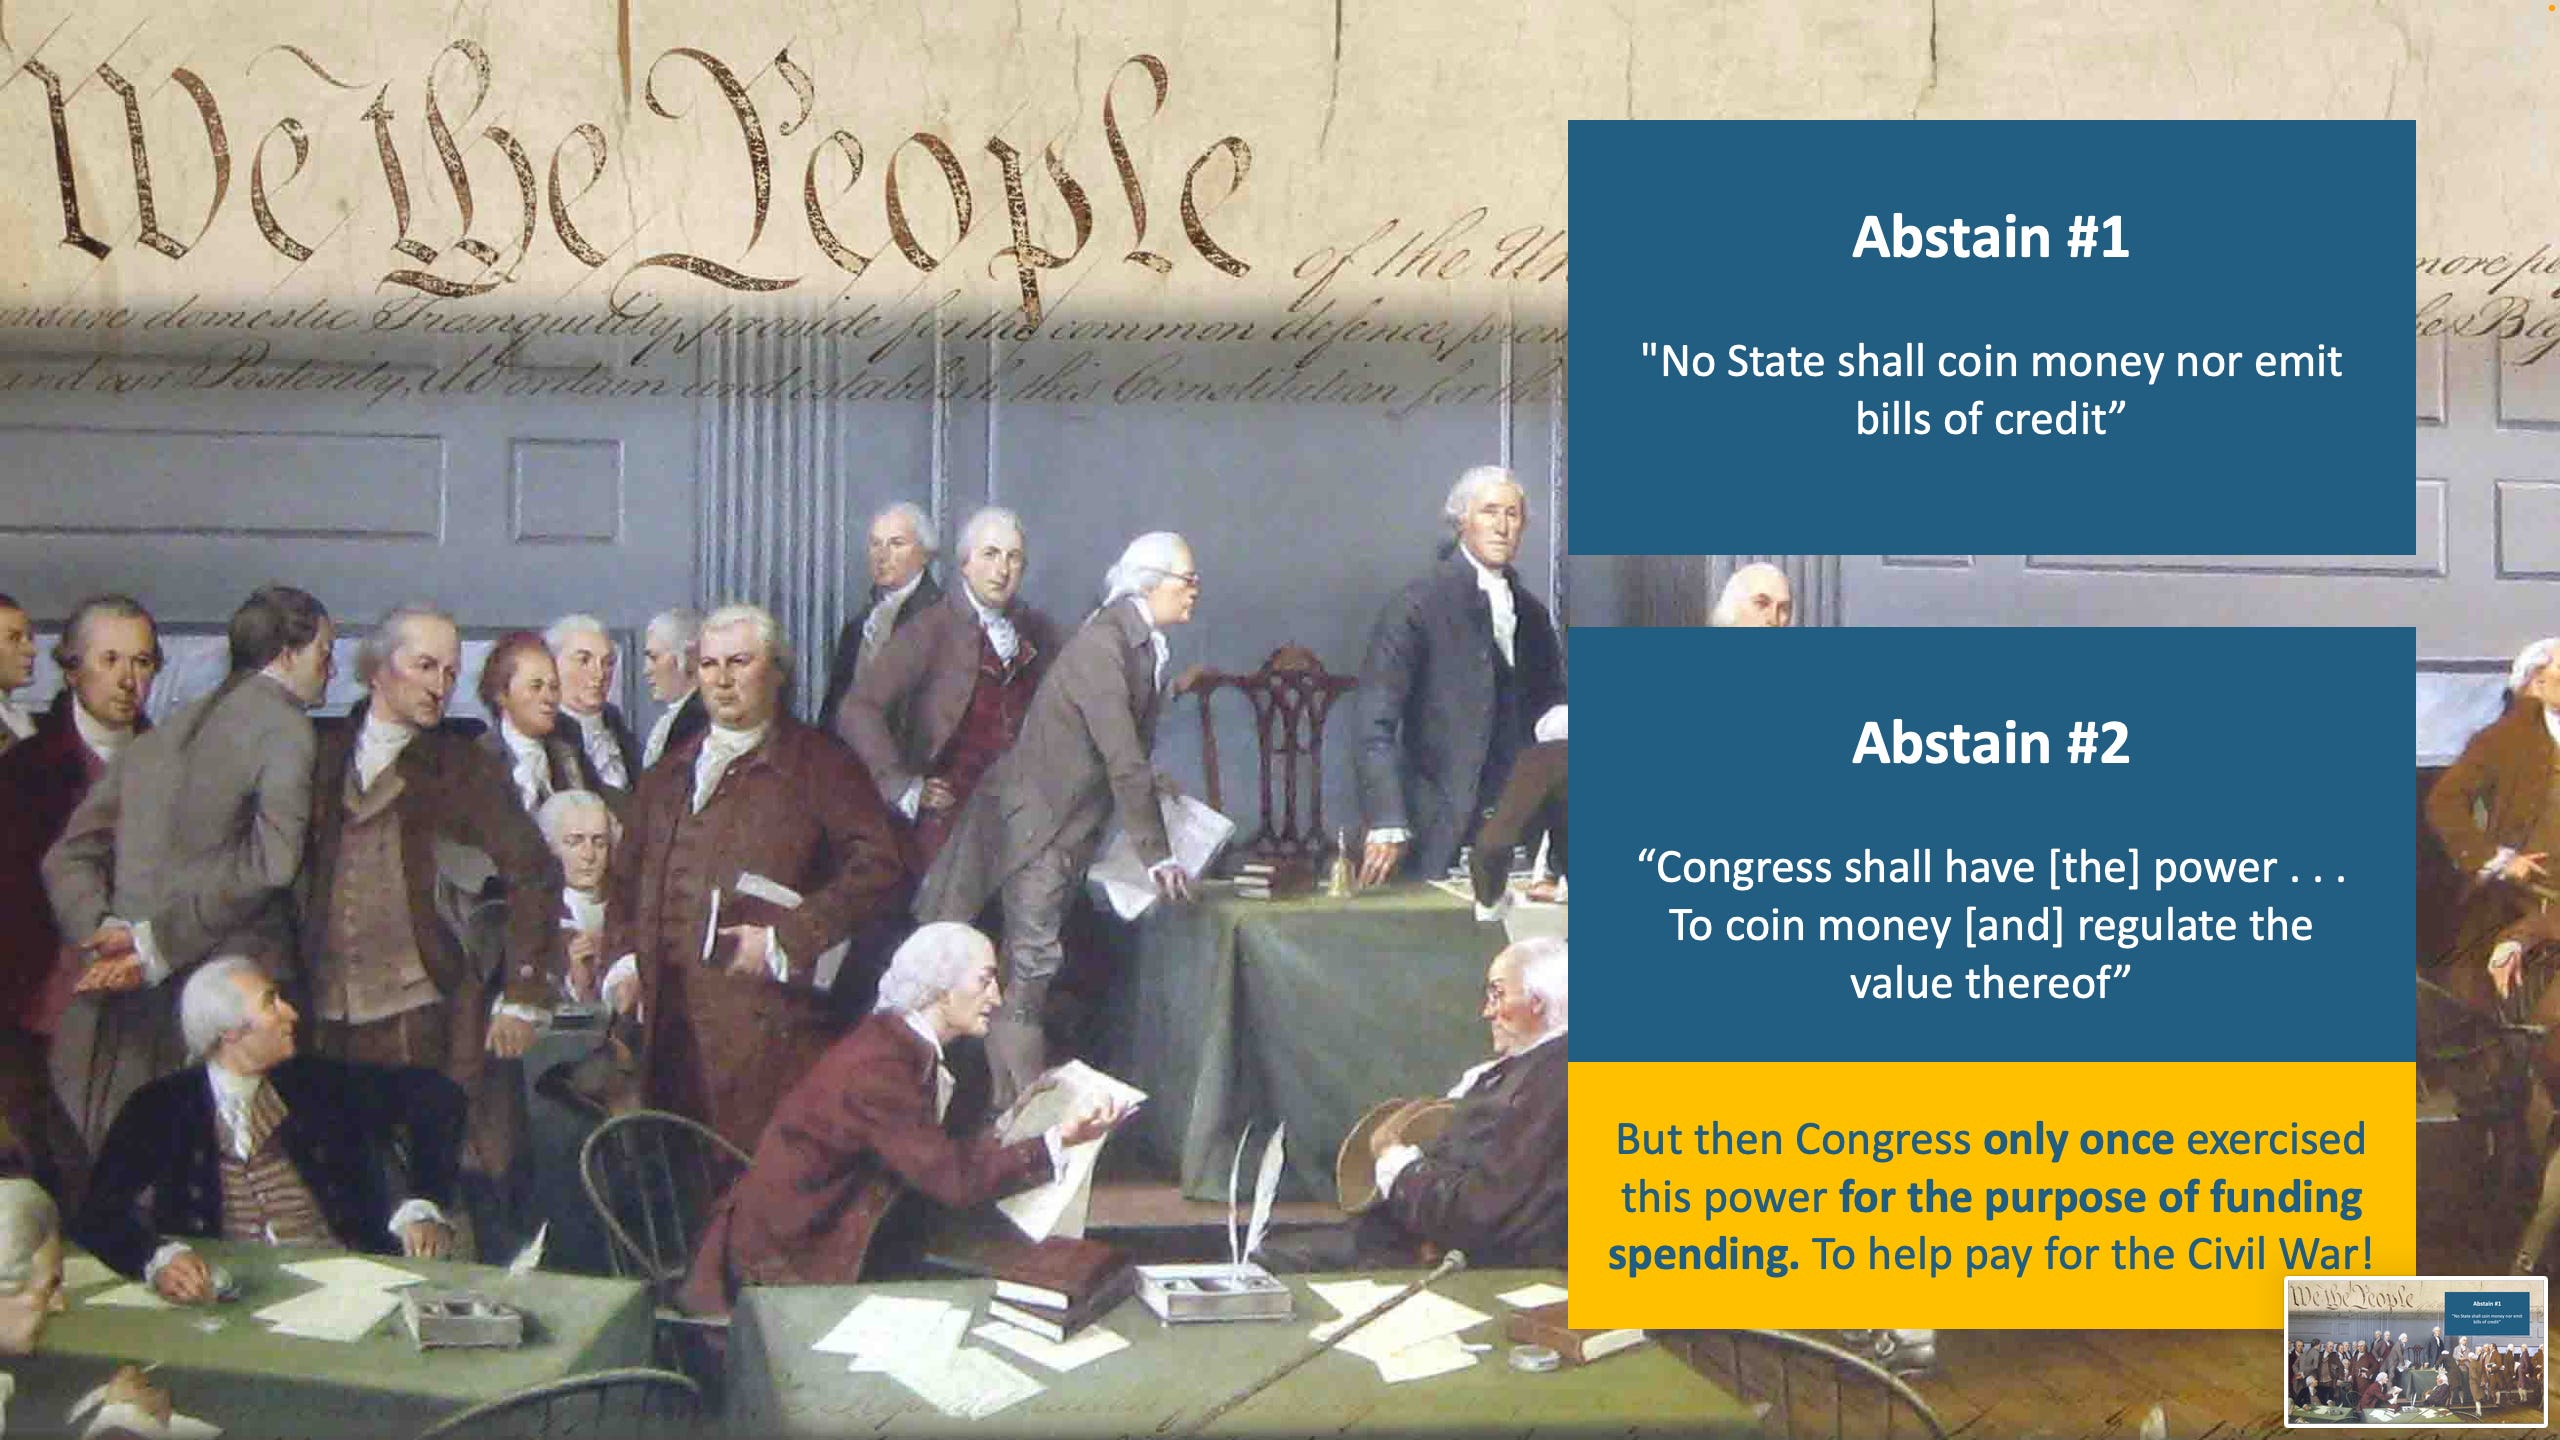
The second abstention is actually a bit more surprising. In the Constitution, it says “Congress shall have the power to coin money and regulate the value thereof.” But while that is in the Constitution, Congress has only used that power once for the purpose of funding spending by the government, and that was to help pay for the Civil War. You might think, “Well, wait, how can that be? The United States government has been minting coins since day one.”
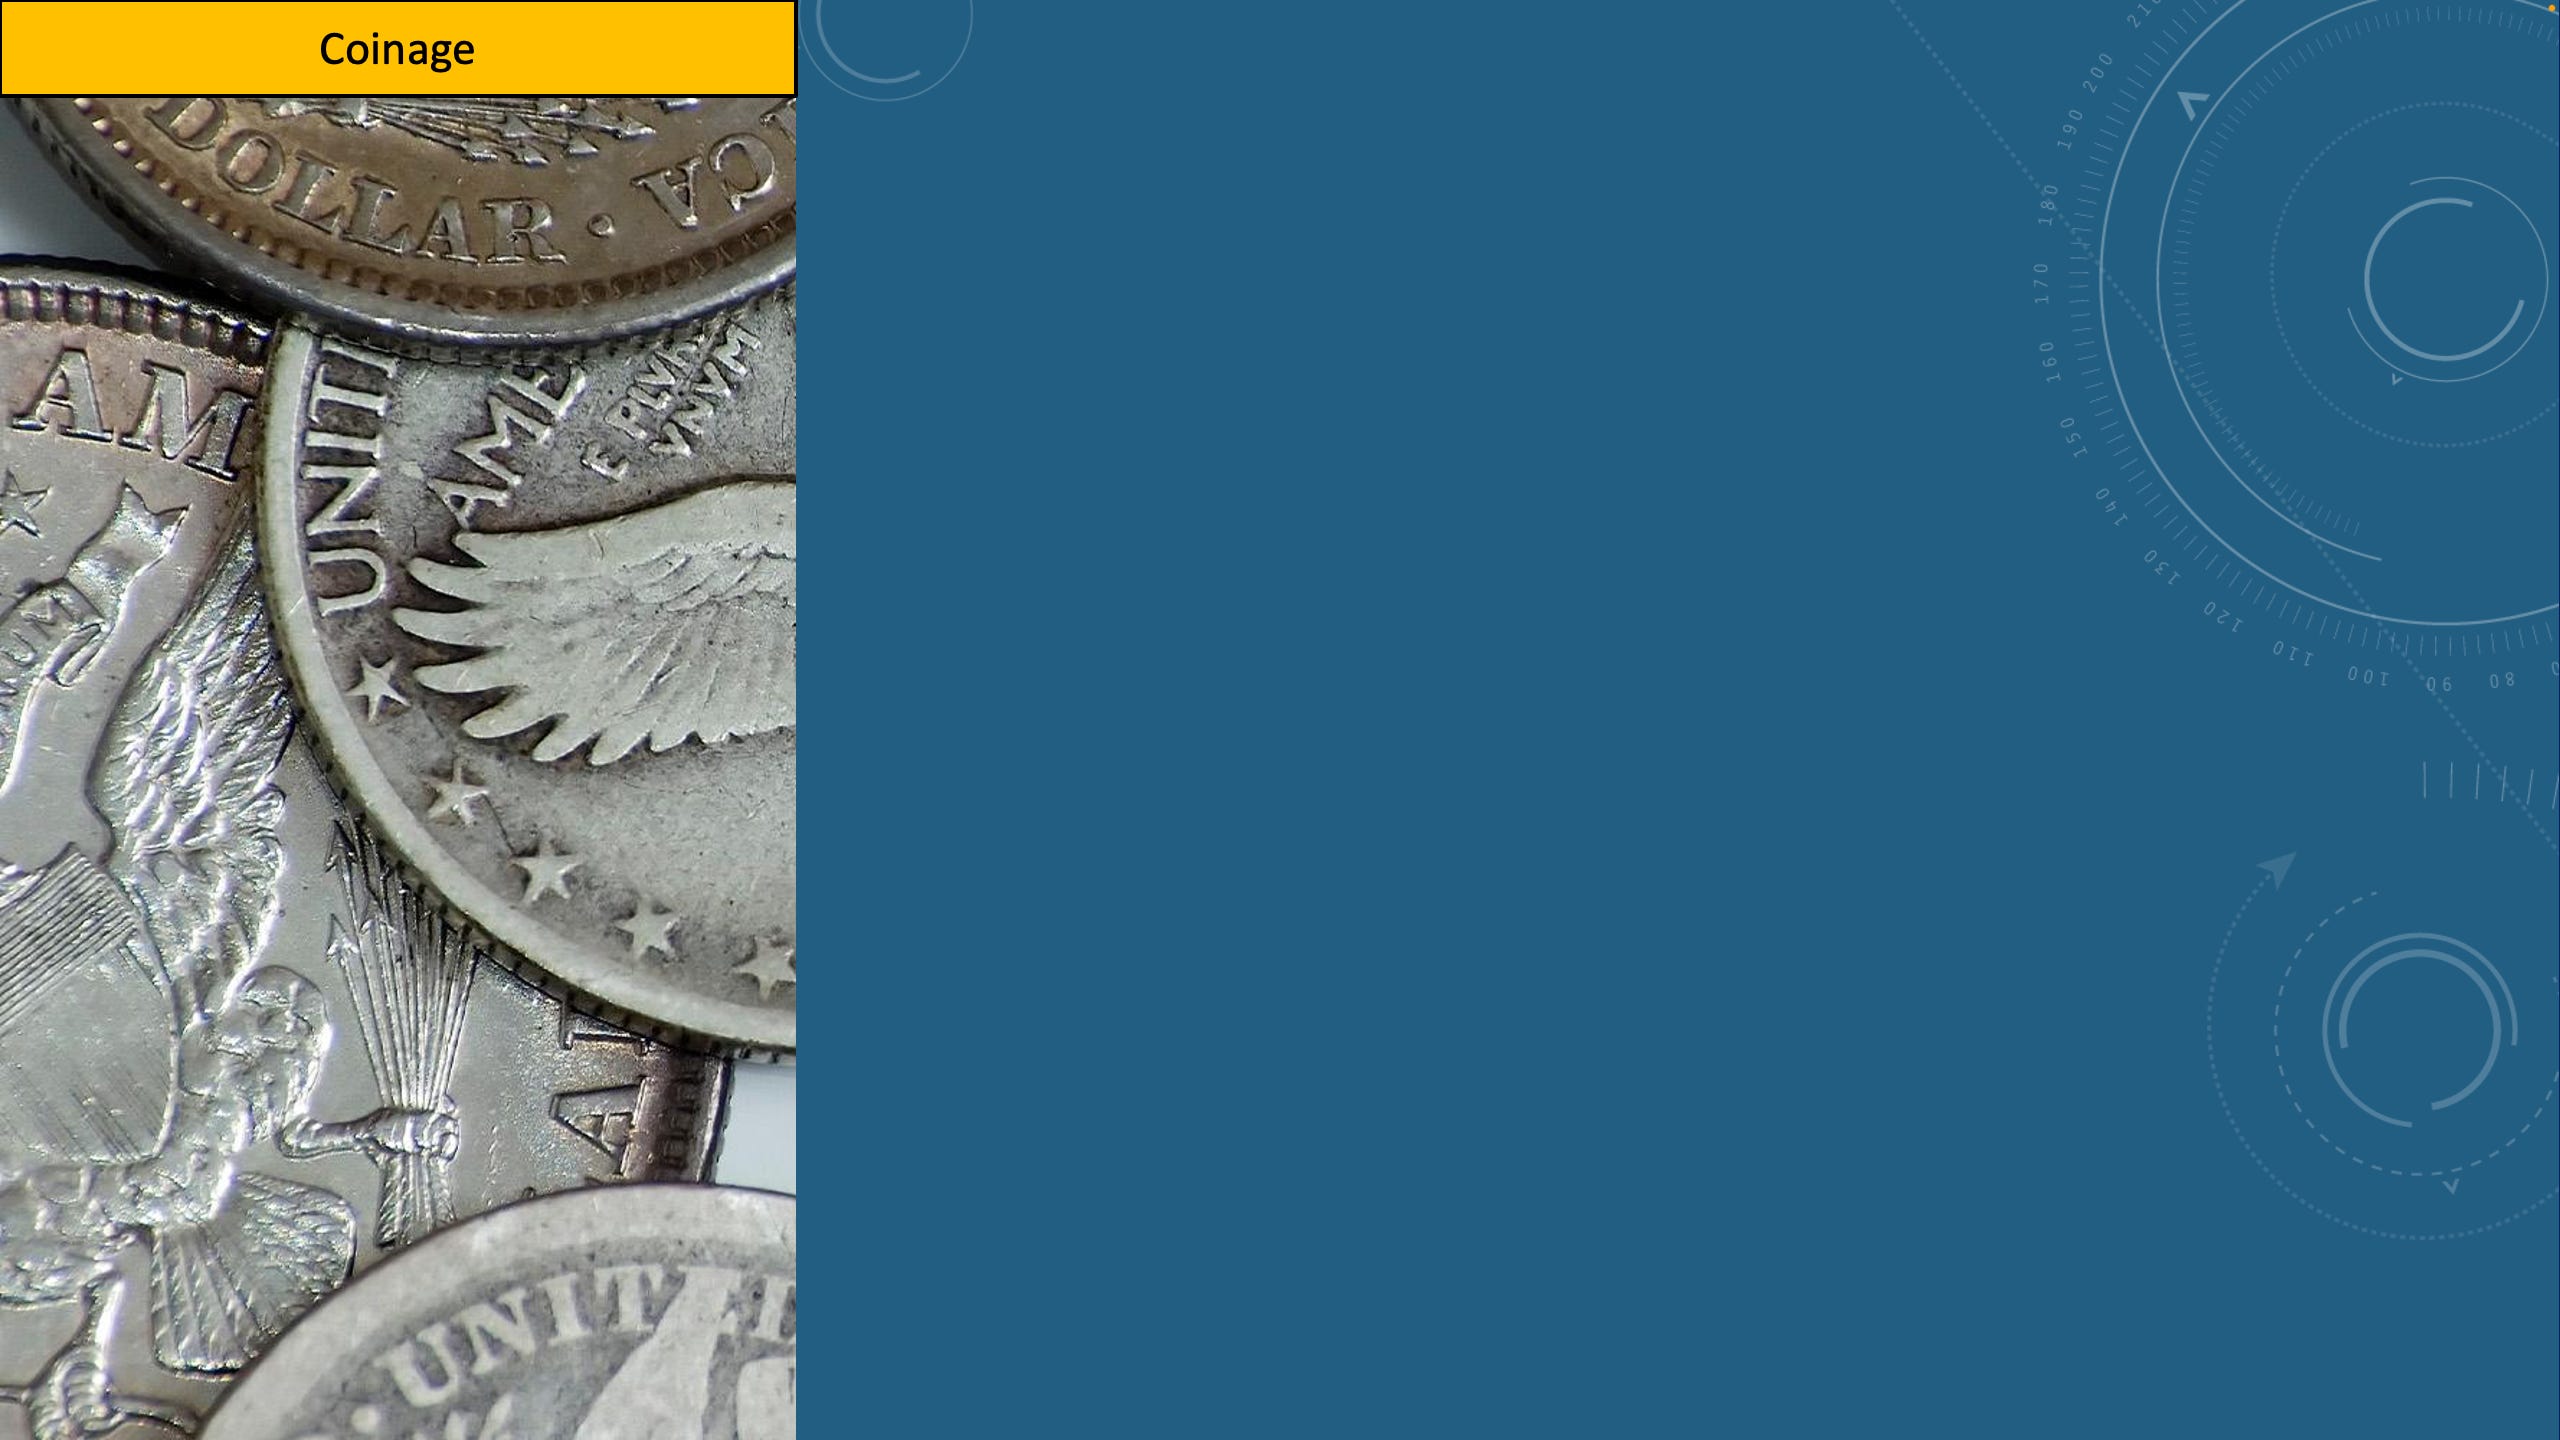
And the answer is that actually, the way that coin came into existence before the Federal Reserve Act, is that the US Mint operated as a public service to the citizenry. Citizens and businesses could bring silver to the mint and the mint would convert it into coins for a fee. So that’s how coinage entered circulation before the Federal Reserve Act.
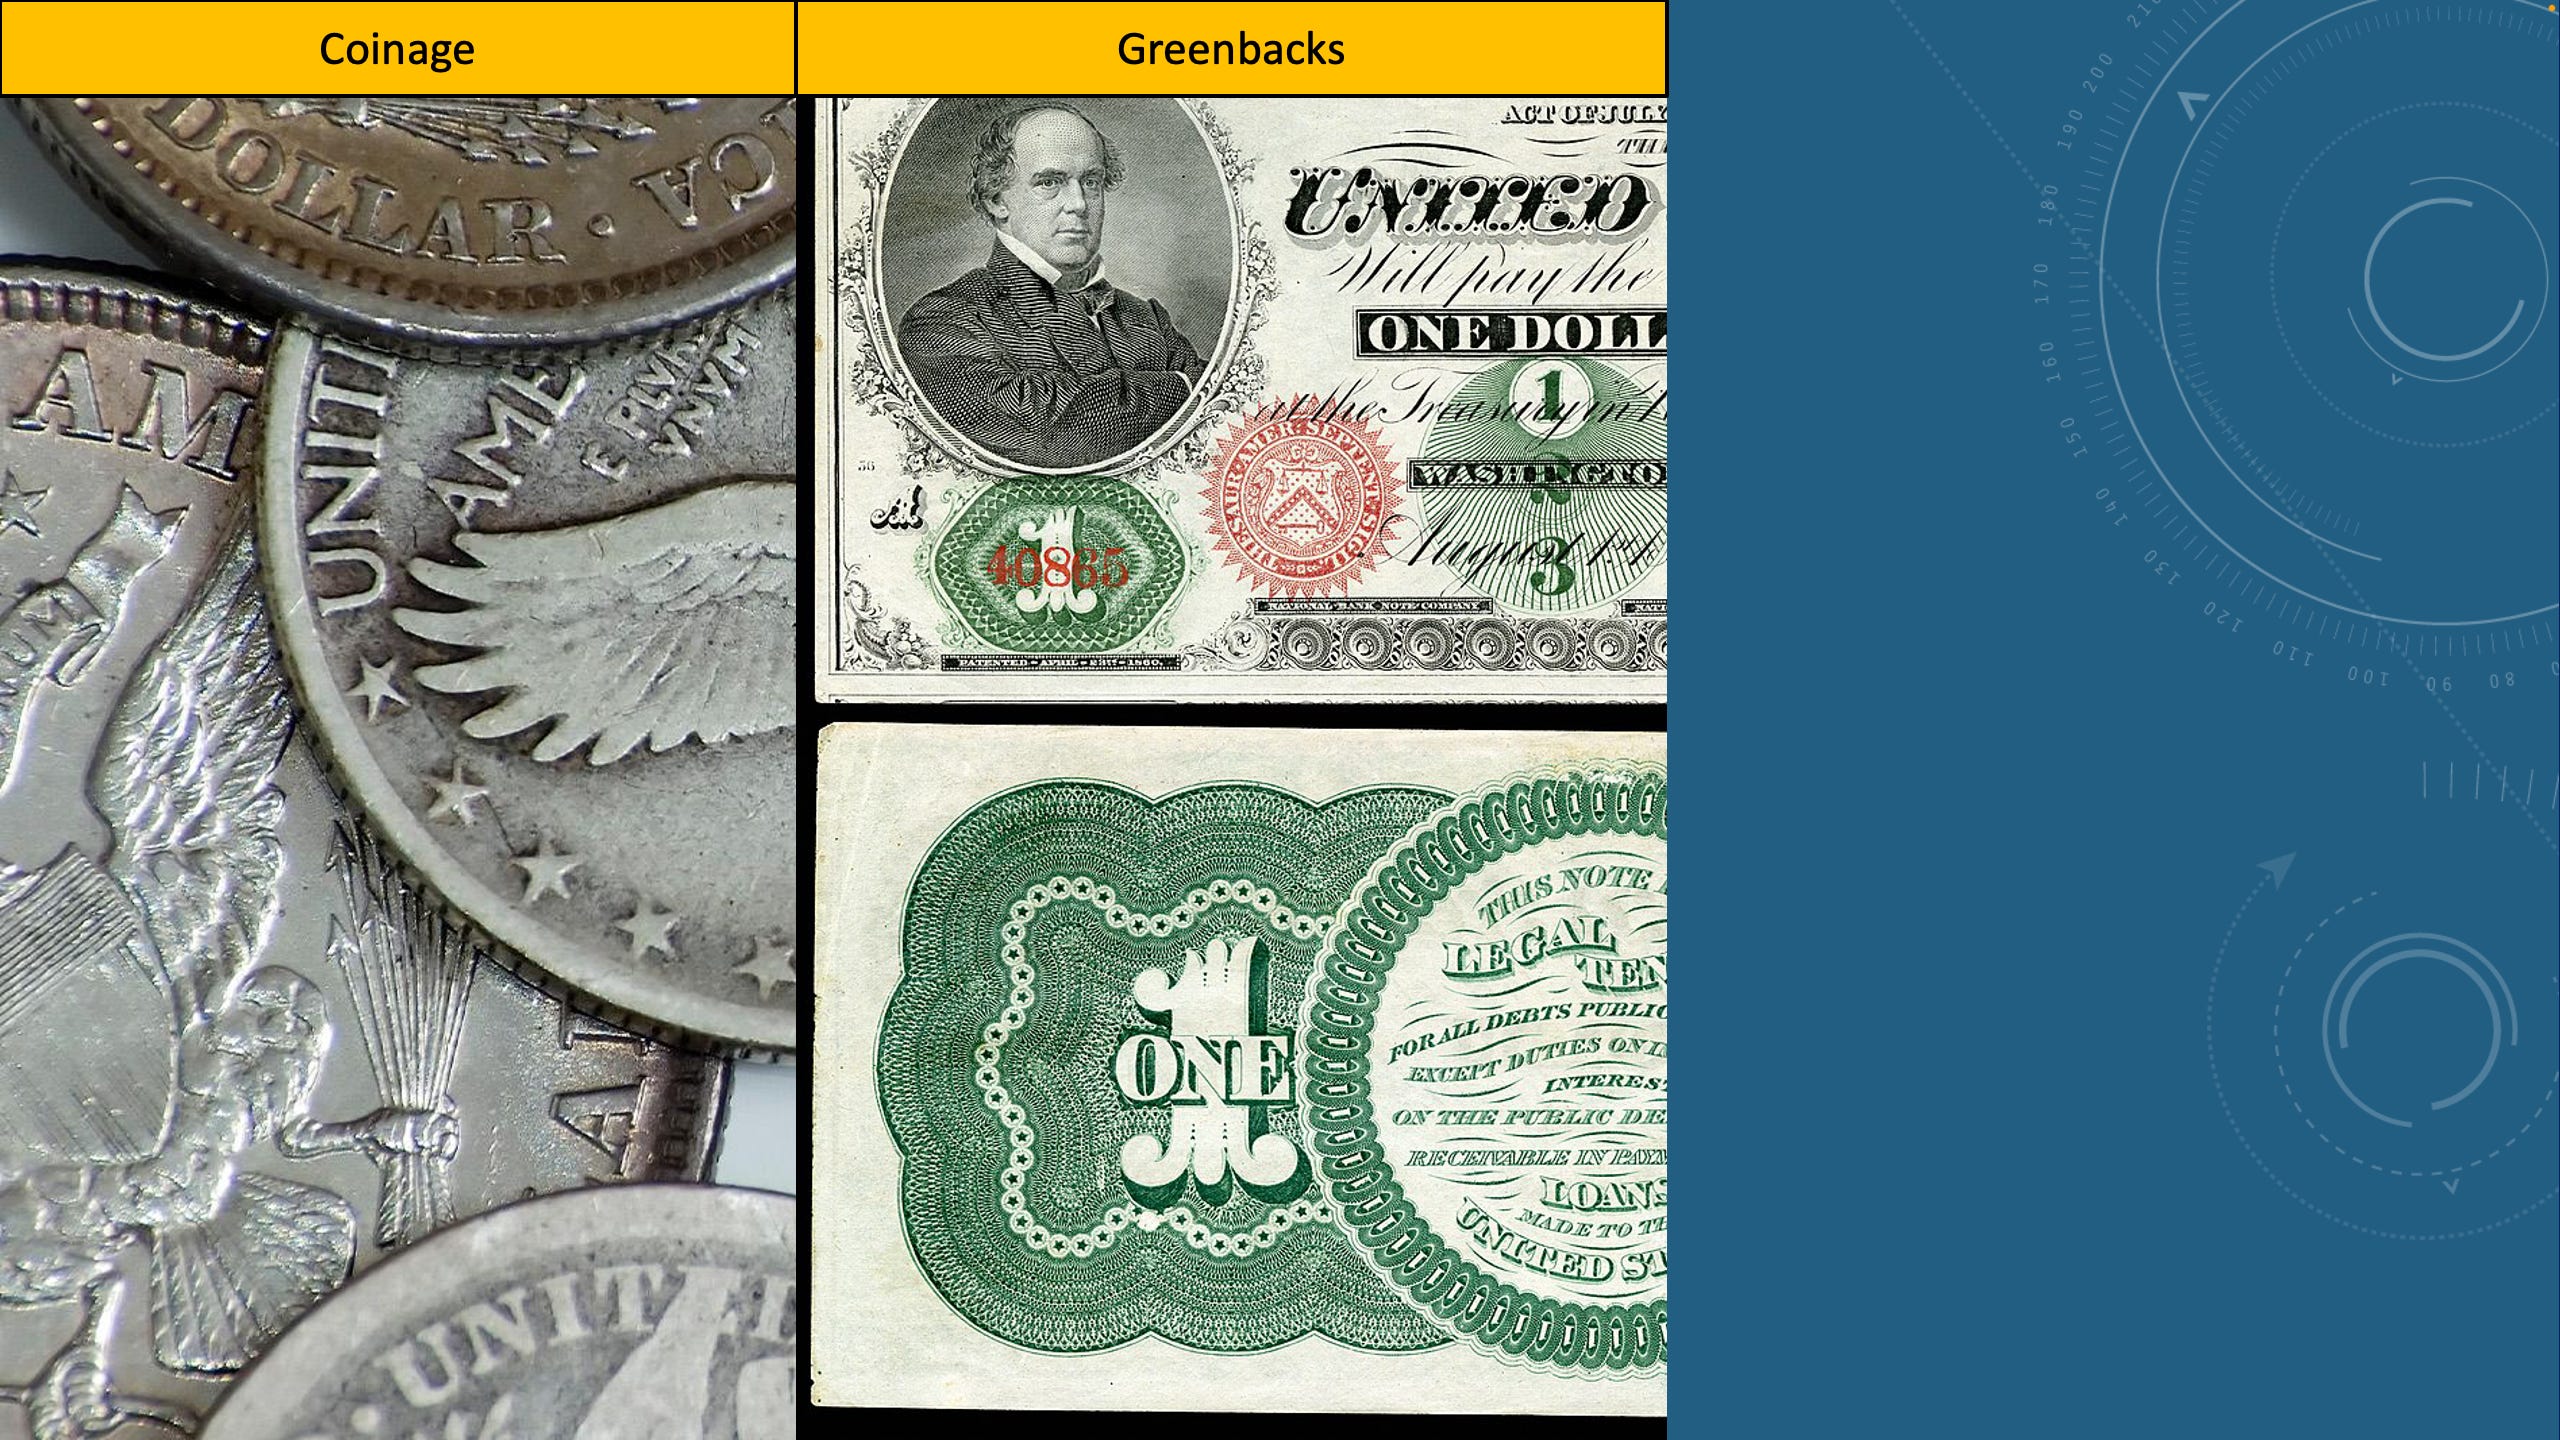
Now, that one instance where the government created money and put it in circulation for spending was the during the Civil War, the government issued what were known as Greenbacks. These were bills that were actually spent into the circulation to pay for the war materials and soldiers and so on. And this was incredibly popular. Many people wanted the government to do this because at that time, as you may remember from the last video, most of the bills that people were working with were issued by privately owned state banks. People understood that that was money that was created as debt by banks, not by the government for the purpose of spending on government services or defense.
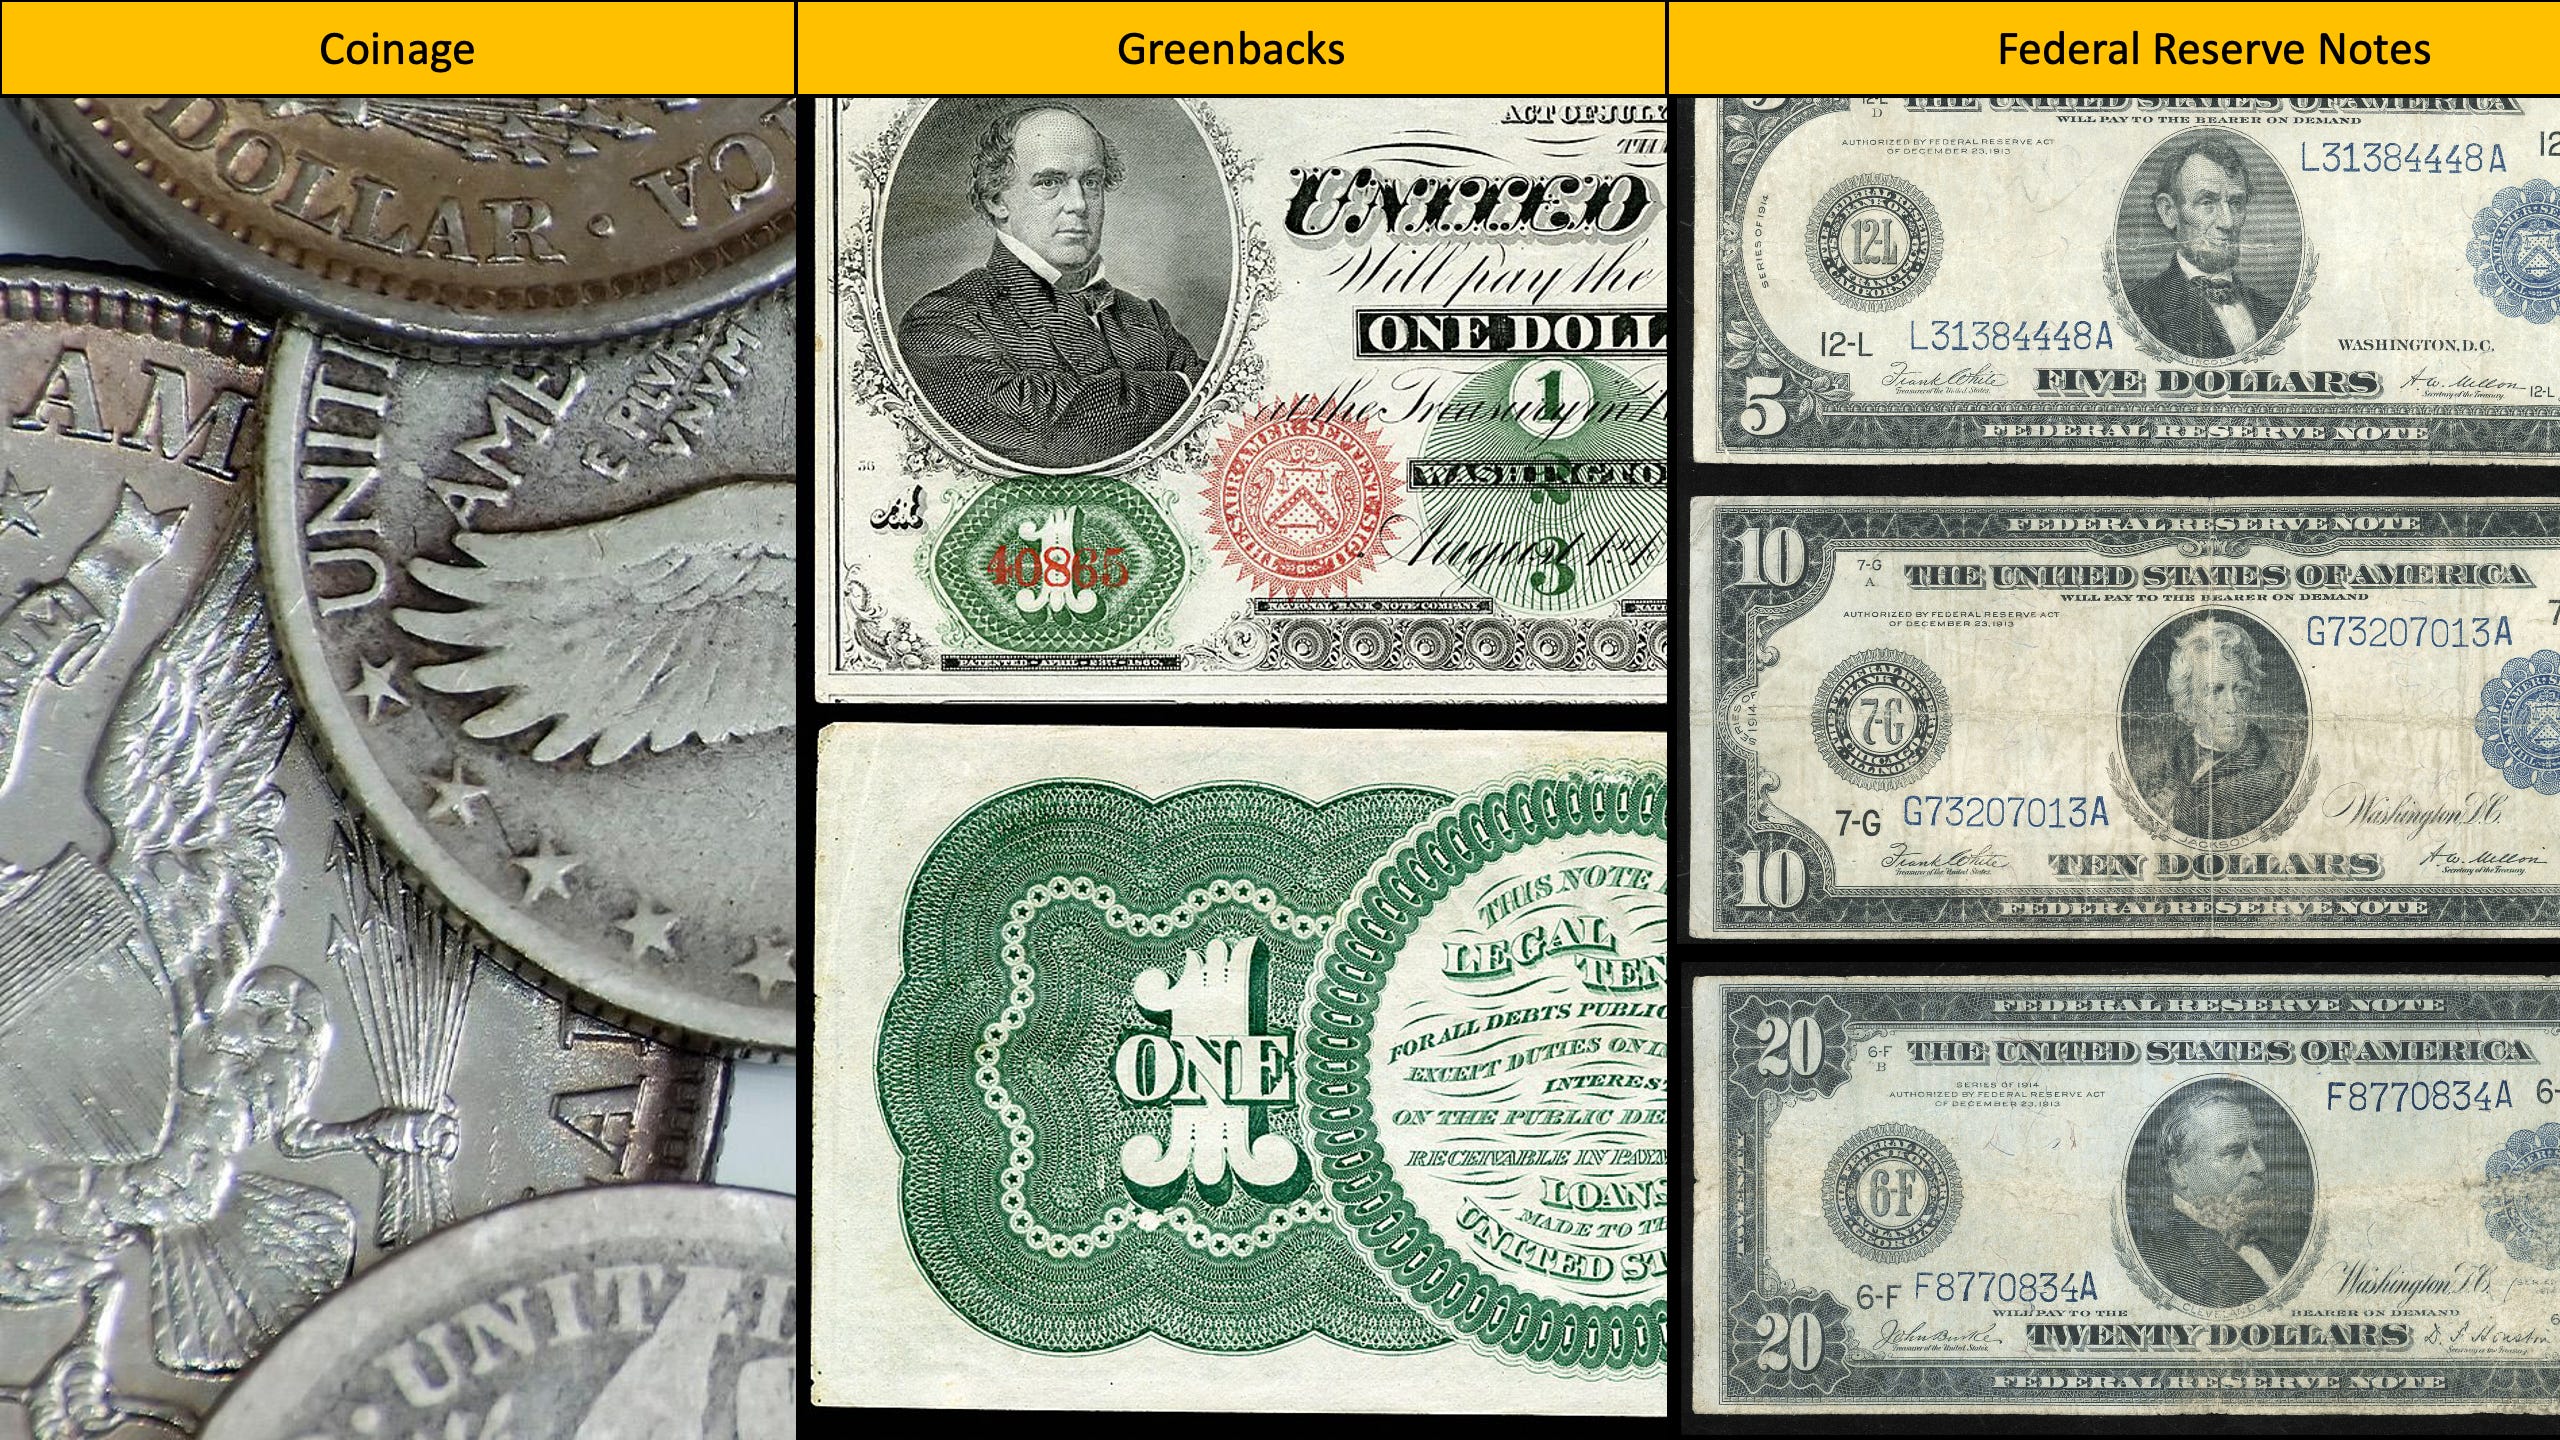
Aside from that one issue [of Greenbacks], the government didn’t start issuing bills again until after the Federal Reserve Act, when it began printing notes that were provided, again, as a service, much like the earlier [minting of coins. Bills were printed and provided] to banks that wanted to provide their customers with a physical representation of their [non-physical] bank deposits. That was discussed more in our previous video.
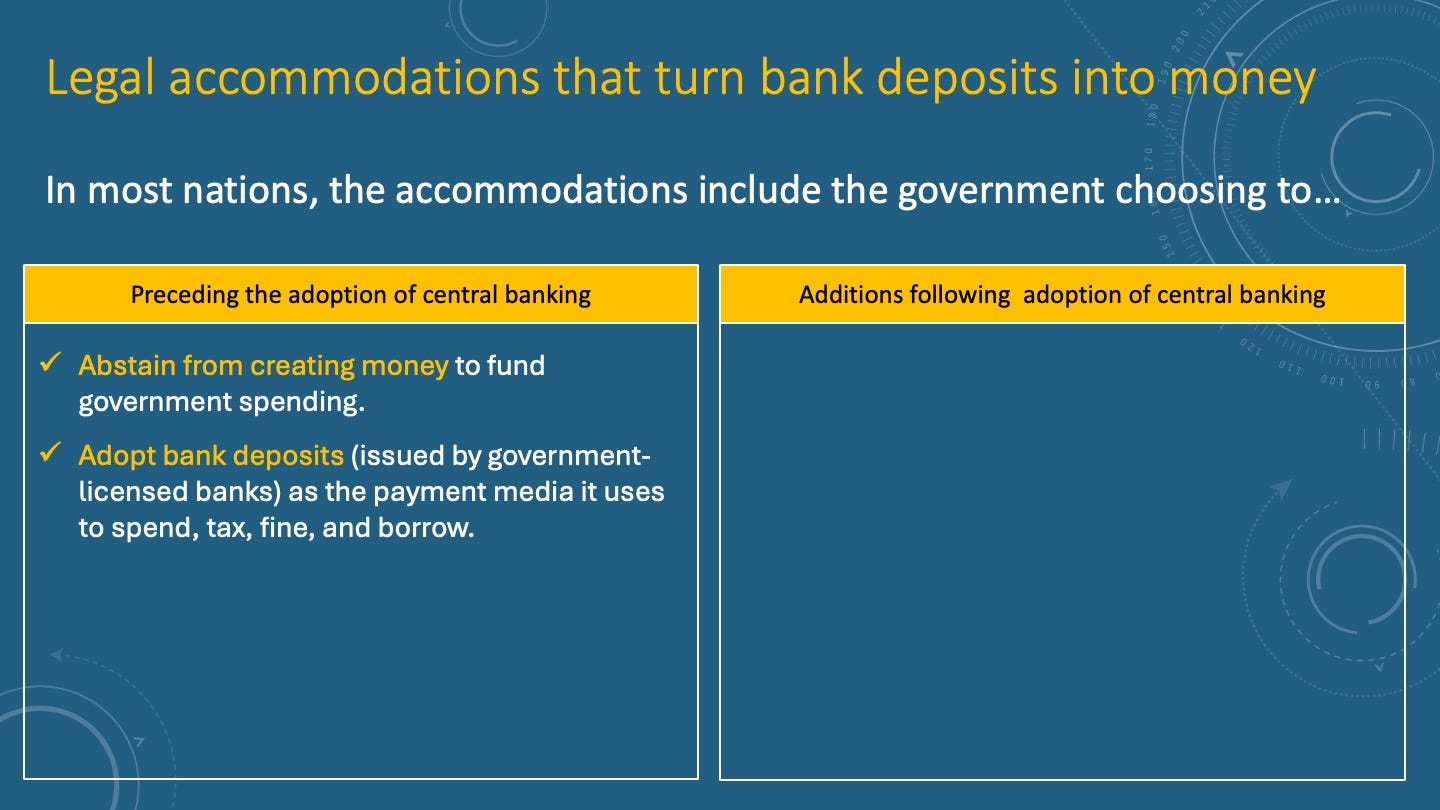
So the second thing that governments will choose to do is, after choosing not to create money for government spending, is adopt bank deposits as the payment media that it uses to spend tax, fine and borrow. So if a government is not going to create its own money and spend it into circulation, what is it going to use to pay tax, spend, fine and so on? And the answer is that it turns to the government licensed banks, and it borrows money from them. The banks create the money for them in their accounting records and then the government spends that into circulation and pays it back as bond with interest.
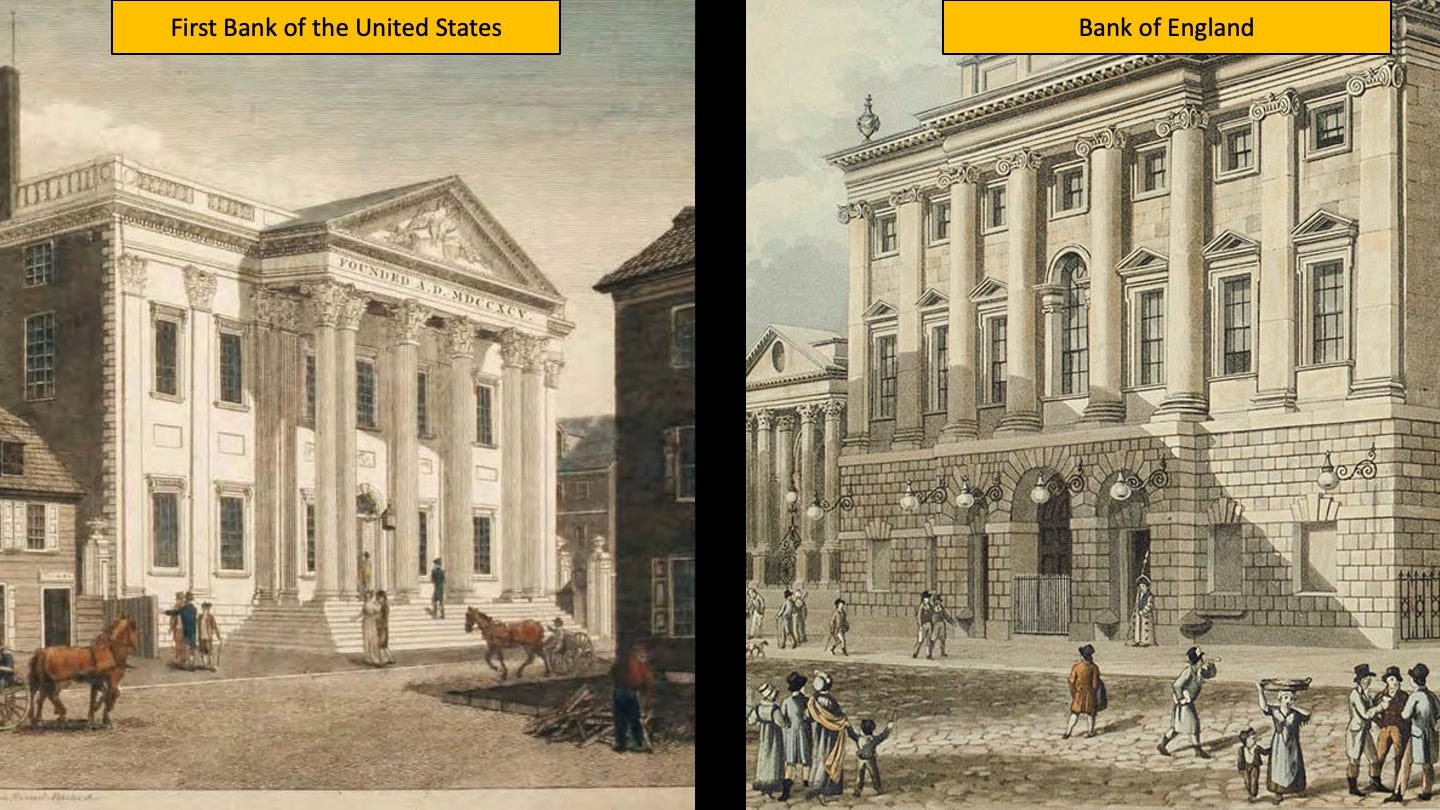
Now this is how Congress decided to answer the question of how it would spend and tax. From day one, they established the First Bank of the United States. This was a private for-profit corporation, modeled on the Bank of England, which was also a private for-profit corporation. Congress borrowed money, bank deposits, from the First Bank of the United States and spent that money and taxed in that money, just as the government of England borrowed money into existence and spent it from the Bank of England and taxed in payments through the Bank of England.
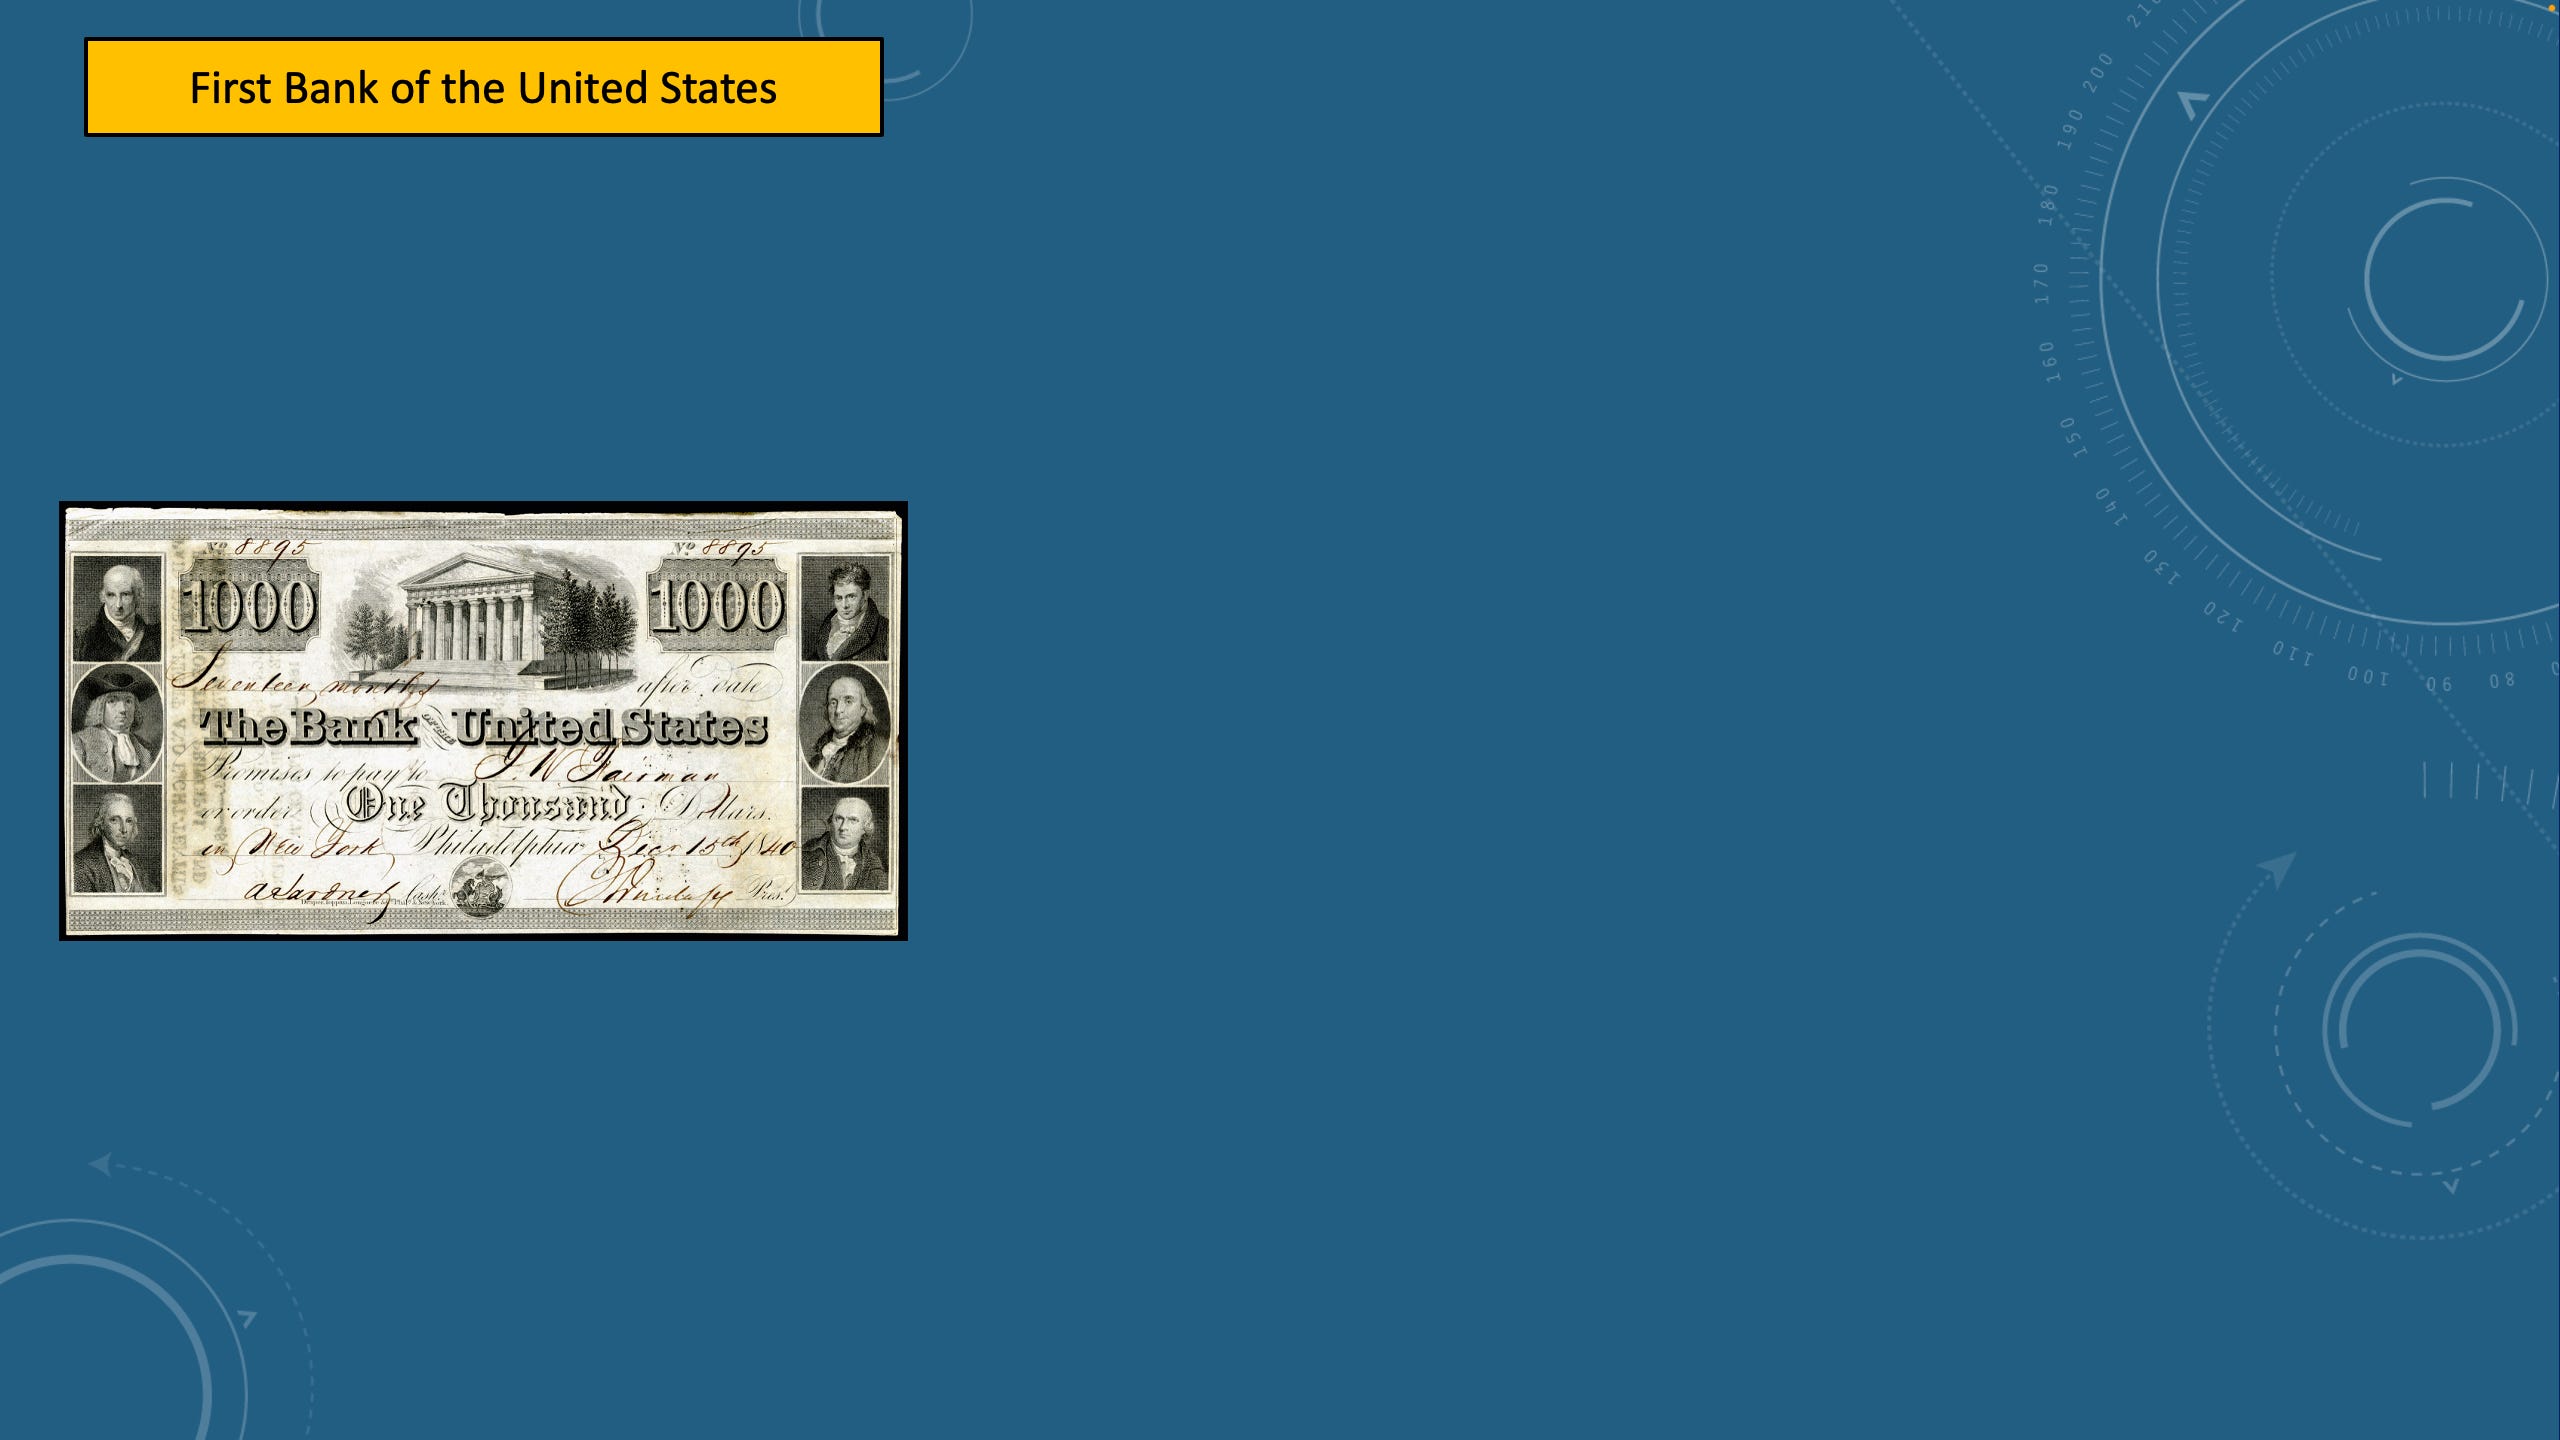
Again, as far as where did the bank notes come from, it was the First Bank of the United States that was printing bank notes. They were printing them just the same way that state banks printed the bank notes that they wanted or needed [in order] to provide a physical representation of their accounting money to their depositors, their customers that wanted to make withdrawals.
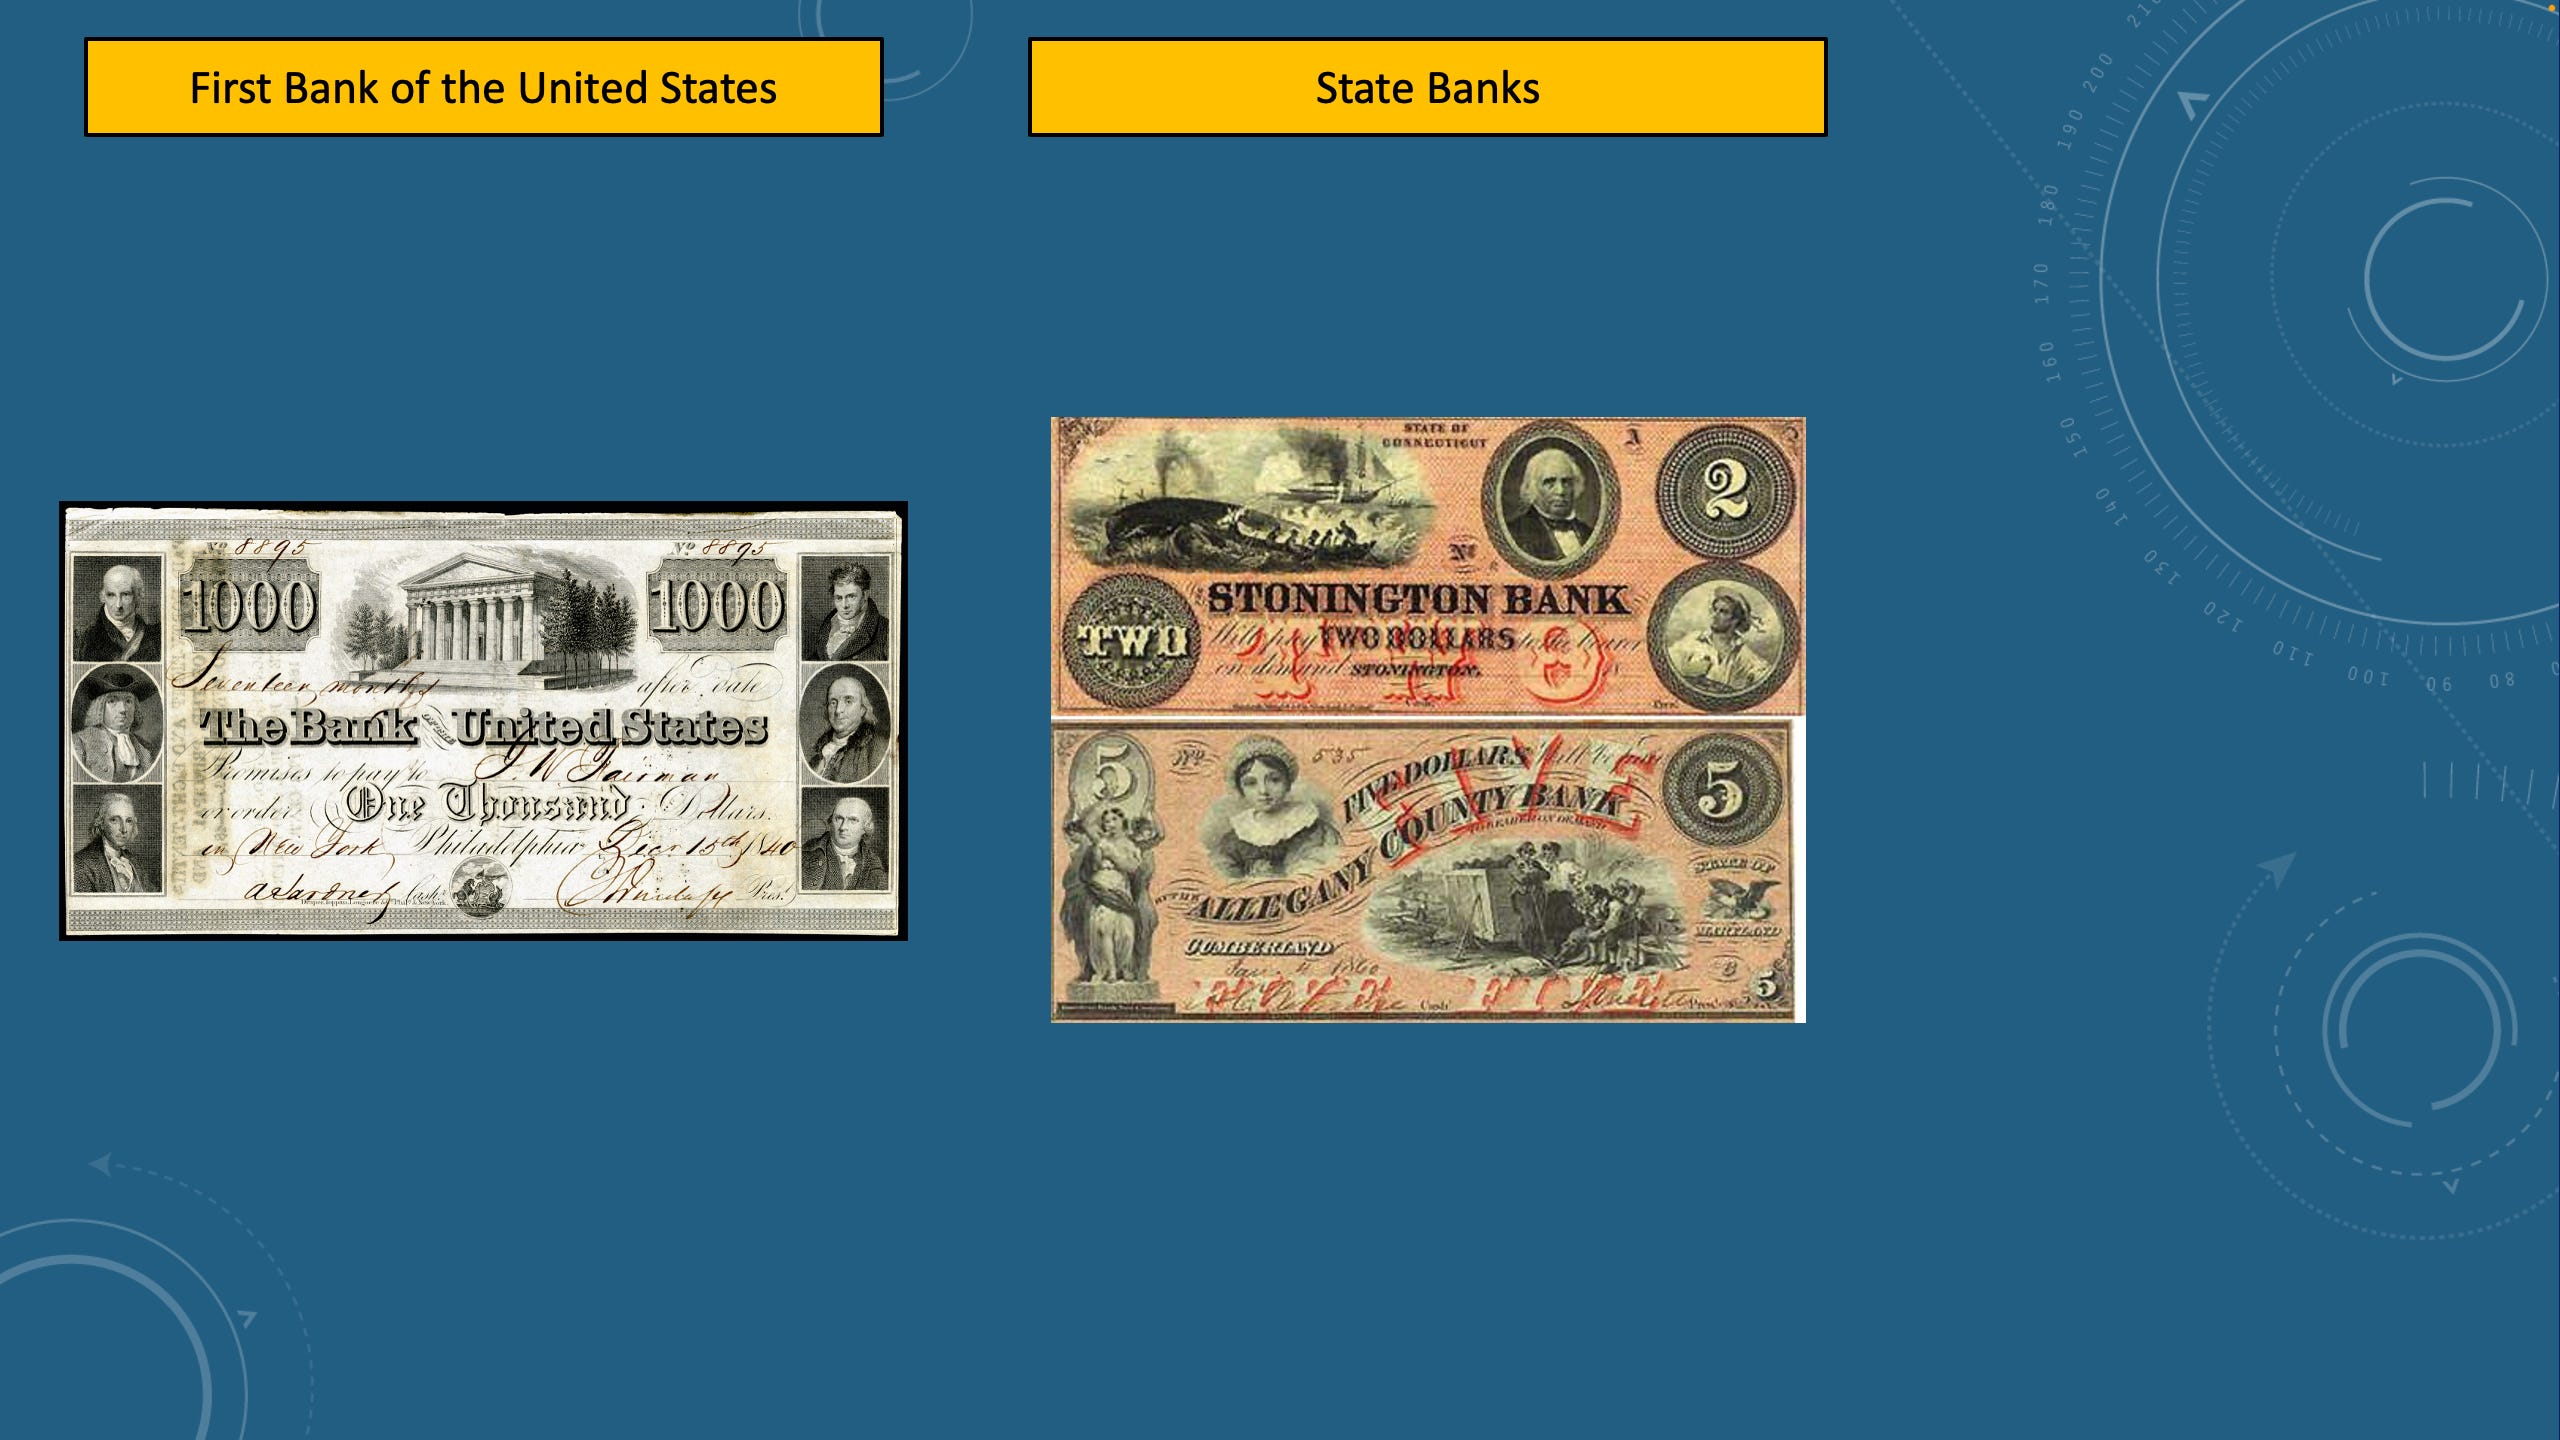
After the First Bank of the United States and the second bank in the United States, you may know that the federal government in the United States got rid of having a central bank, a preferred bank, and it switched to banking at many different banks, such as state banks, like you can see here. As I said, most of the notes circulating in the economy until the Federal Reserve Act were issued by individual banks. So here, how did the United States Government operate? Since it had abstained from creating its own money, it was borrowing money and transacting through the accounting records of state banks.
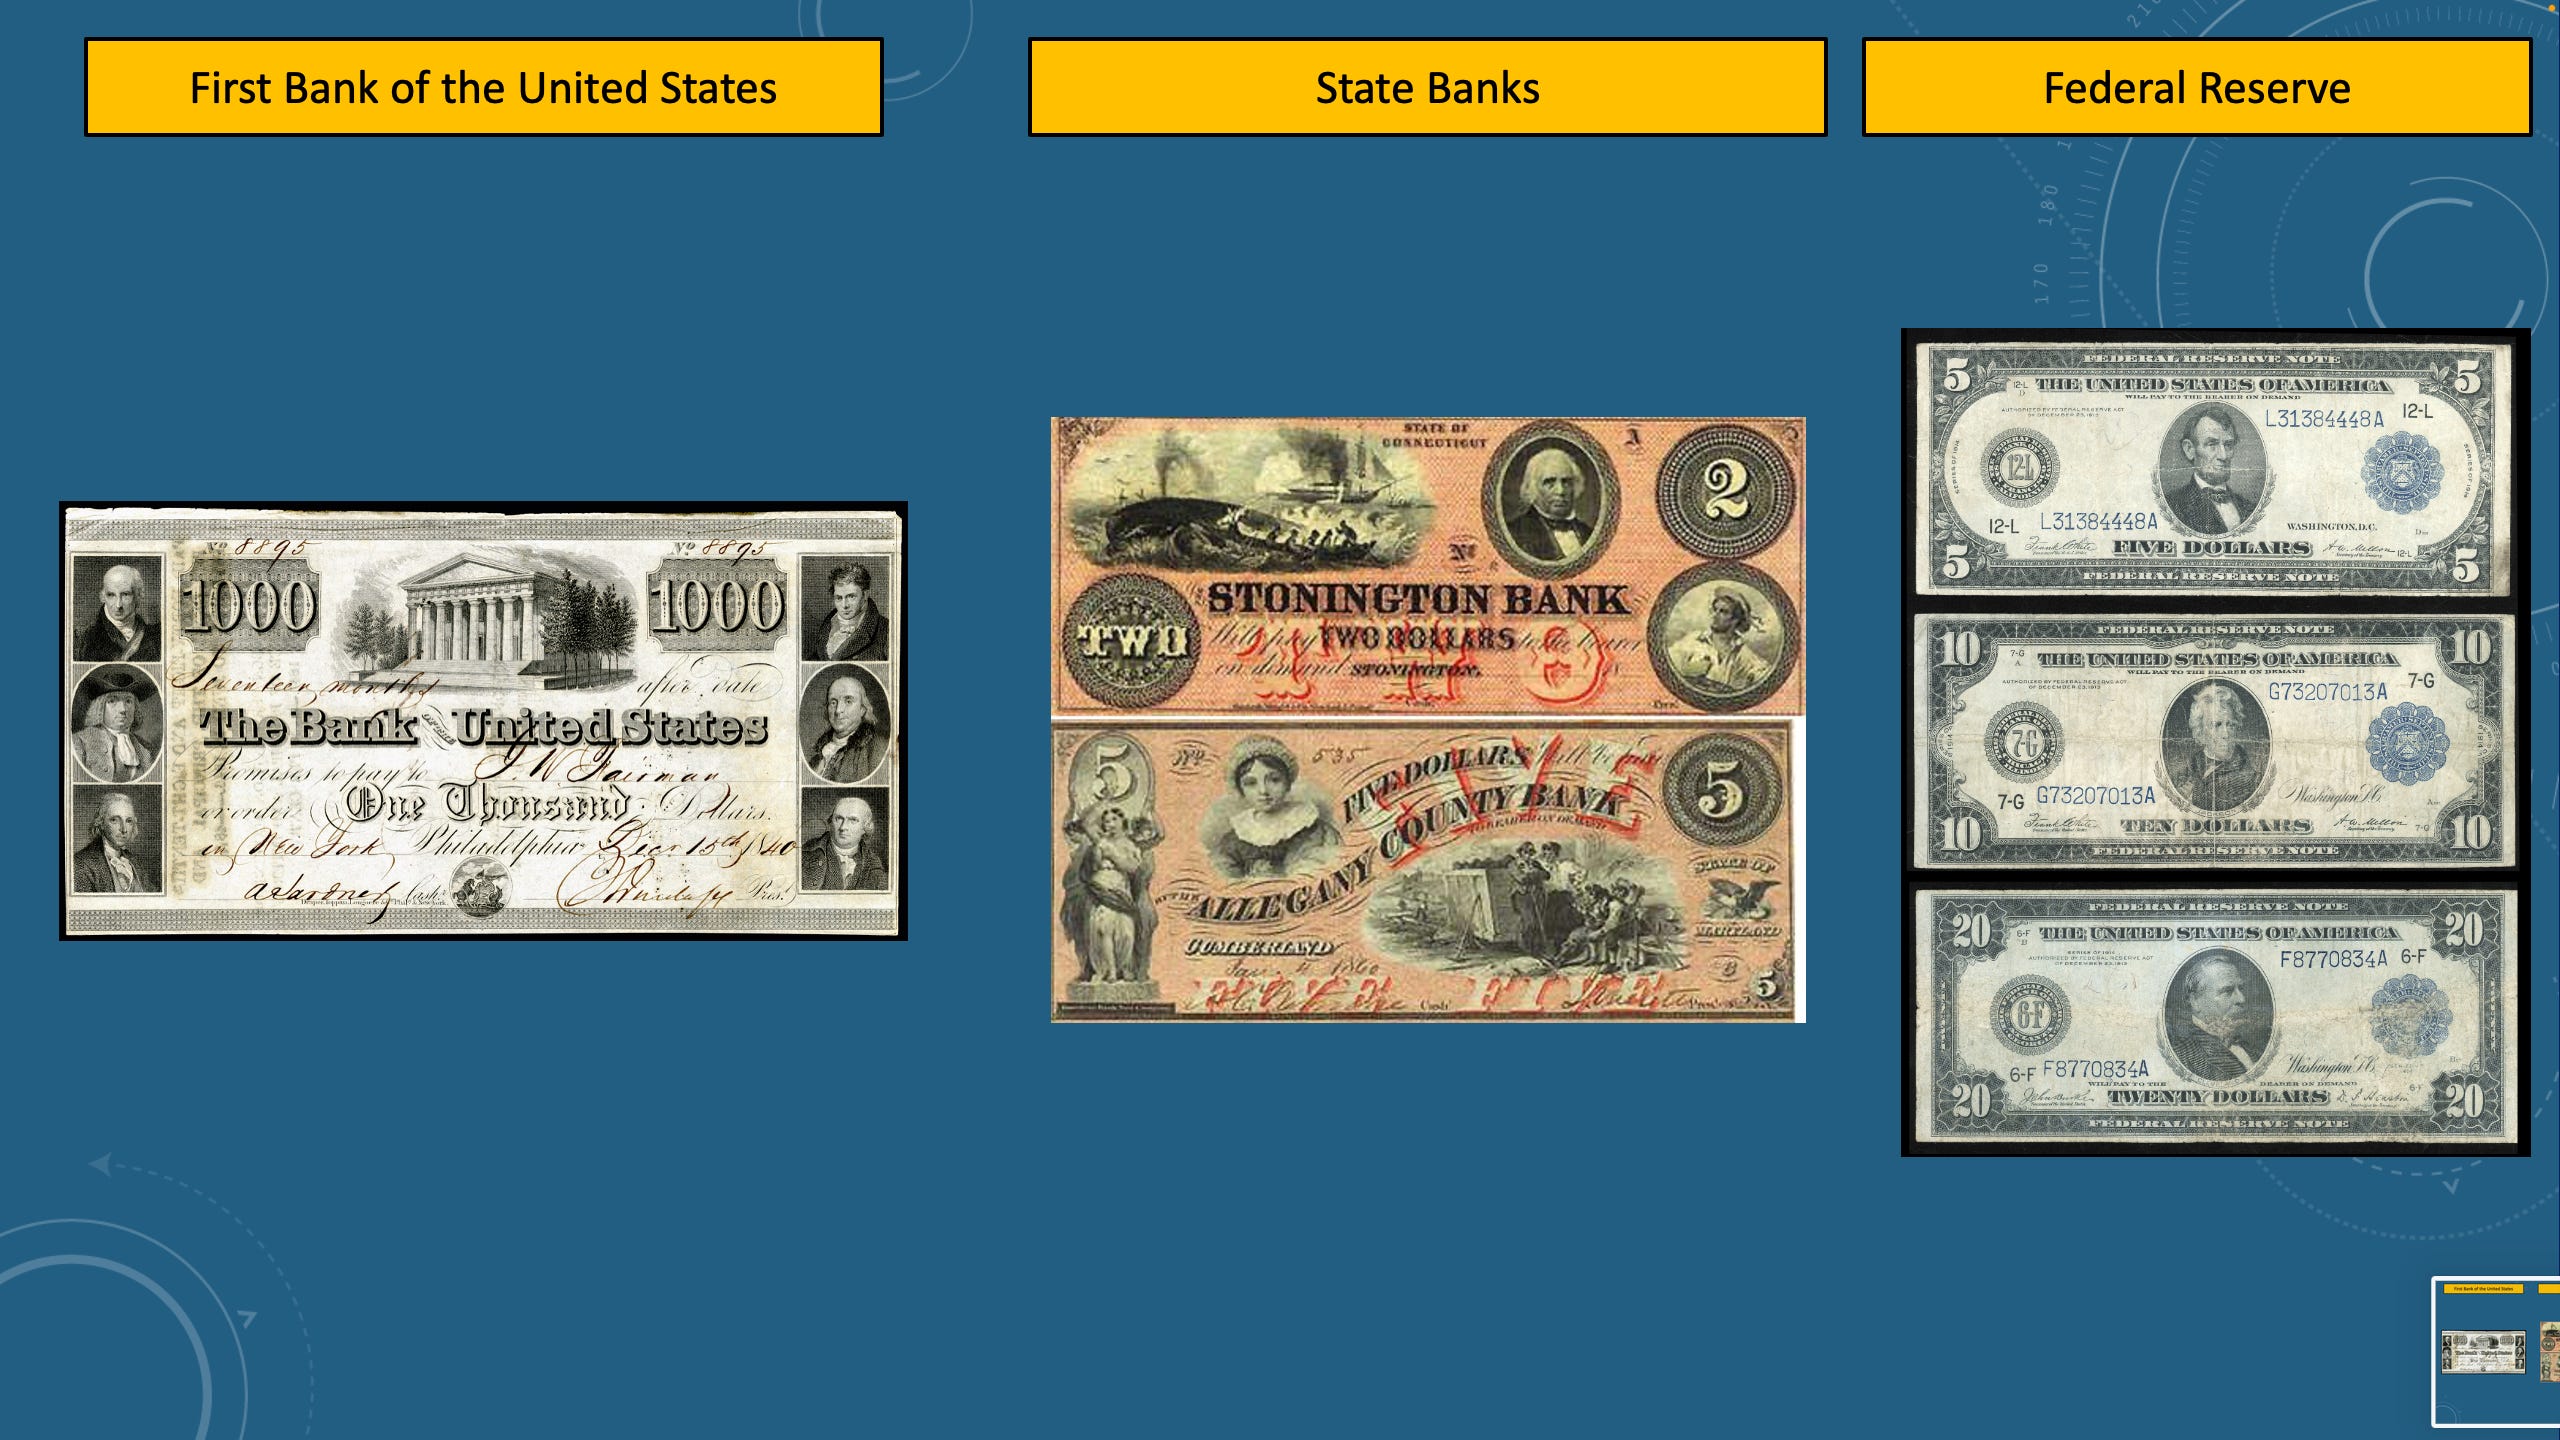
It was only when the Federal Reserve Act was signed in 1913 that the Federal Reserve provided banks with the service of printing consistently formatted bank notes. All of these diverse bank notes created by different banks disappeared and we ended up with a consistent currency, physical currency. But that doesn’t mean that the government was creating the money and spending the money in circulation. It’s the same as it was all along, which is that the banks are creating the money to provide a physical representation of their bank deposits. And you know now, much as the mint earlier, the government provides that service to the banks through the central bank, Federal Reserve, at a fee.
[Note that the Federal Reserve bills look somewhat similar to the Civil War Greenbacks, which were still circulating when the Federal Reserve began issuing bills. The similarity of design was intentional. The Federal Reserve Act was politically unpopular due to the fact that it was going to continue the government’s practice of borrowing money into existence from private for-profit banks. When the Federal Reserve bills were introduced, they were made to look like Greenbacks in order to piggyback on the popularity of Greenbacks. As President Woodrow Wilson said at the time of the signing of the Federal Reserve Act: “If we can hold to the substance of the thing and give the other fellow the shadow, why not do it?” (quoted in Lowenstein 2016)]
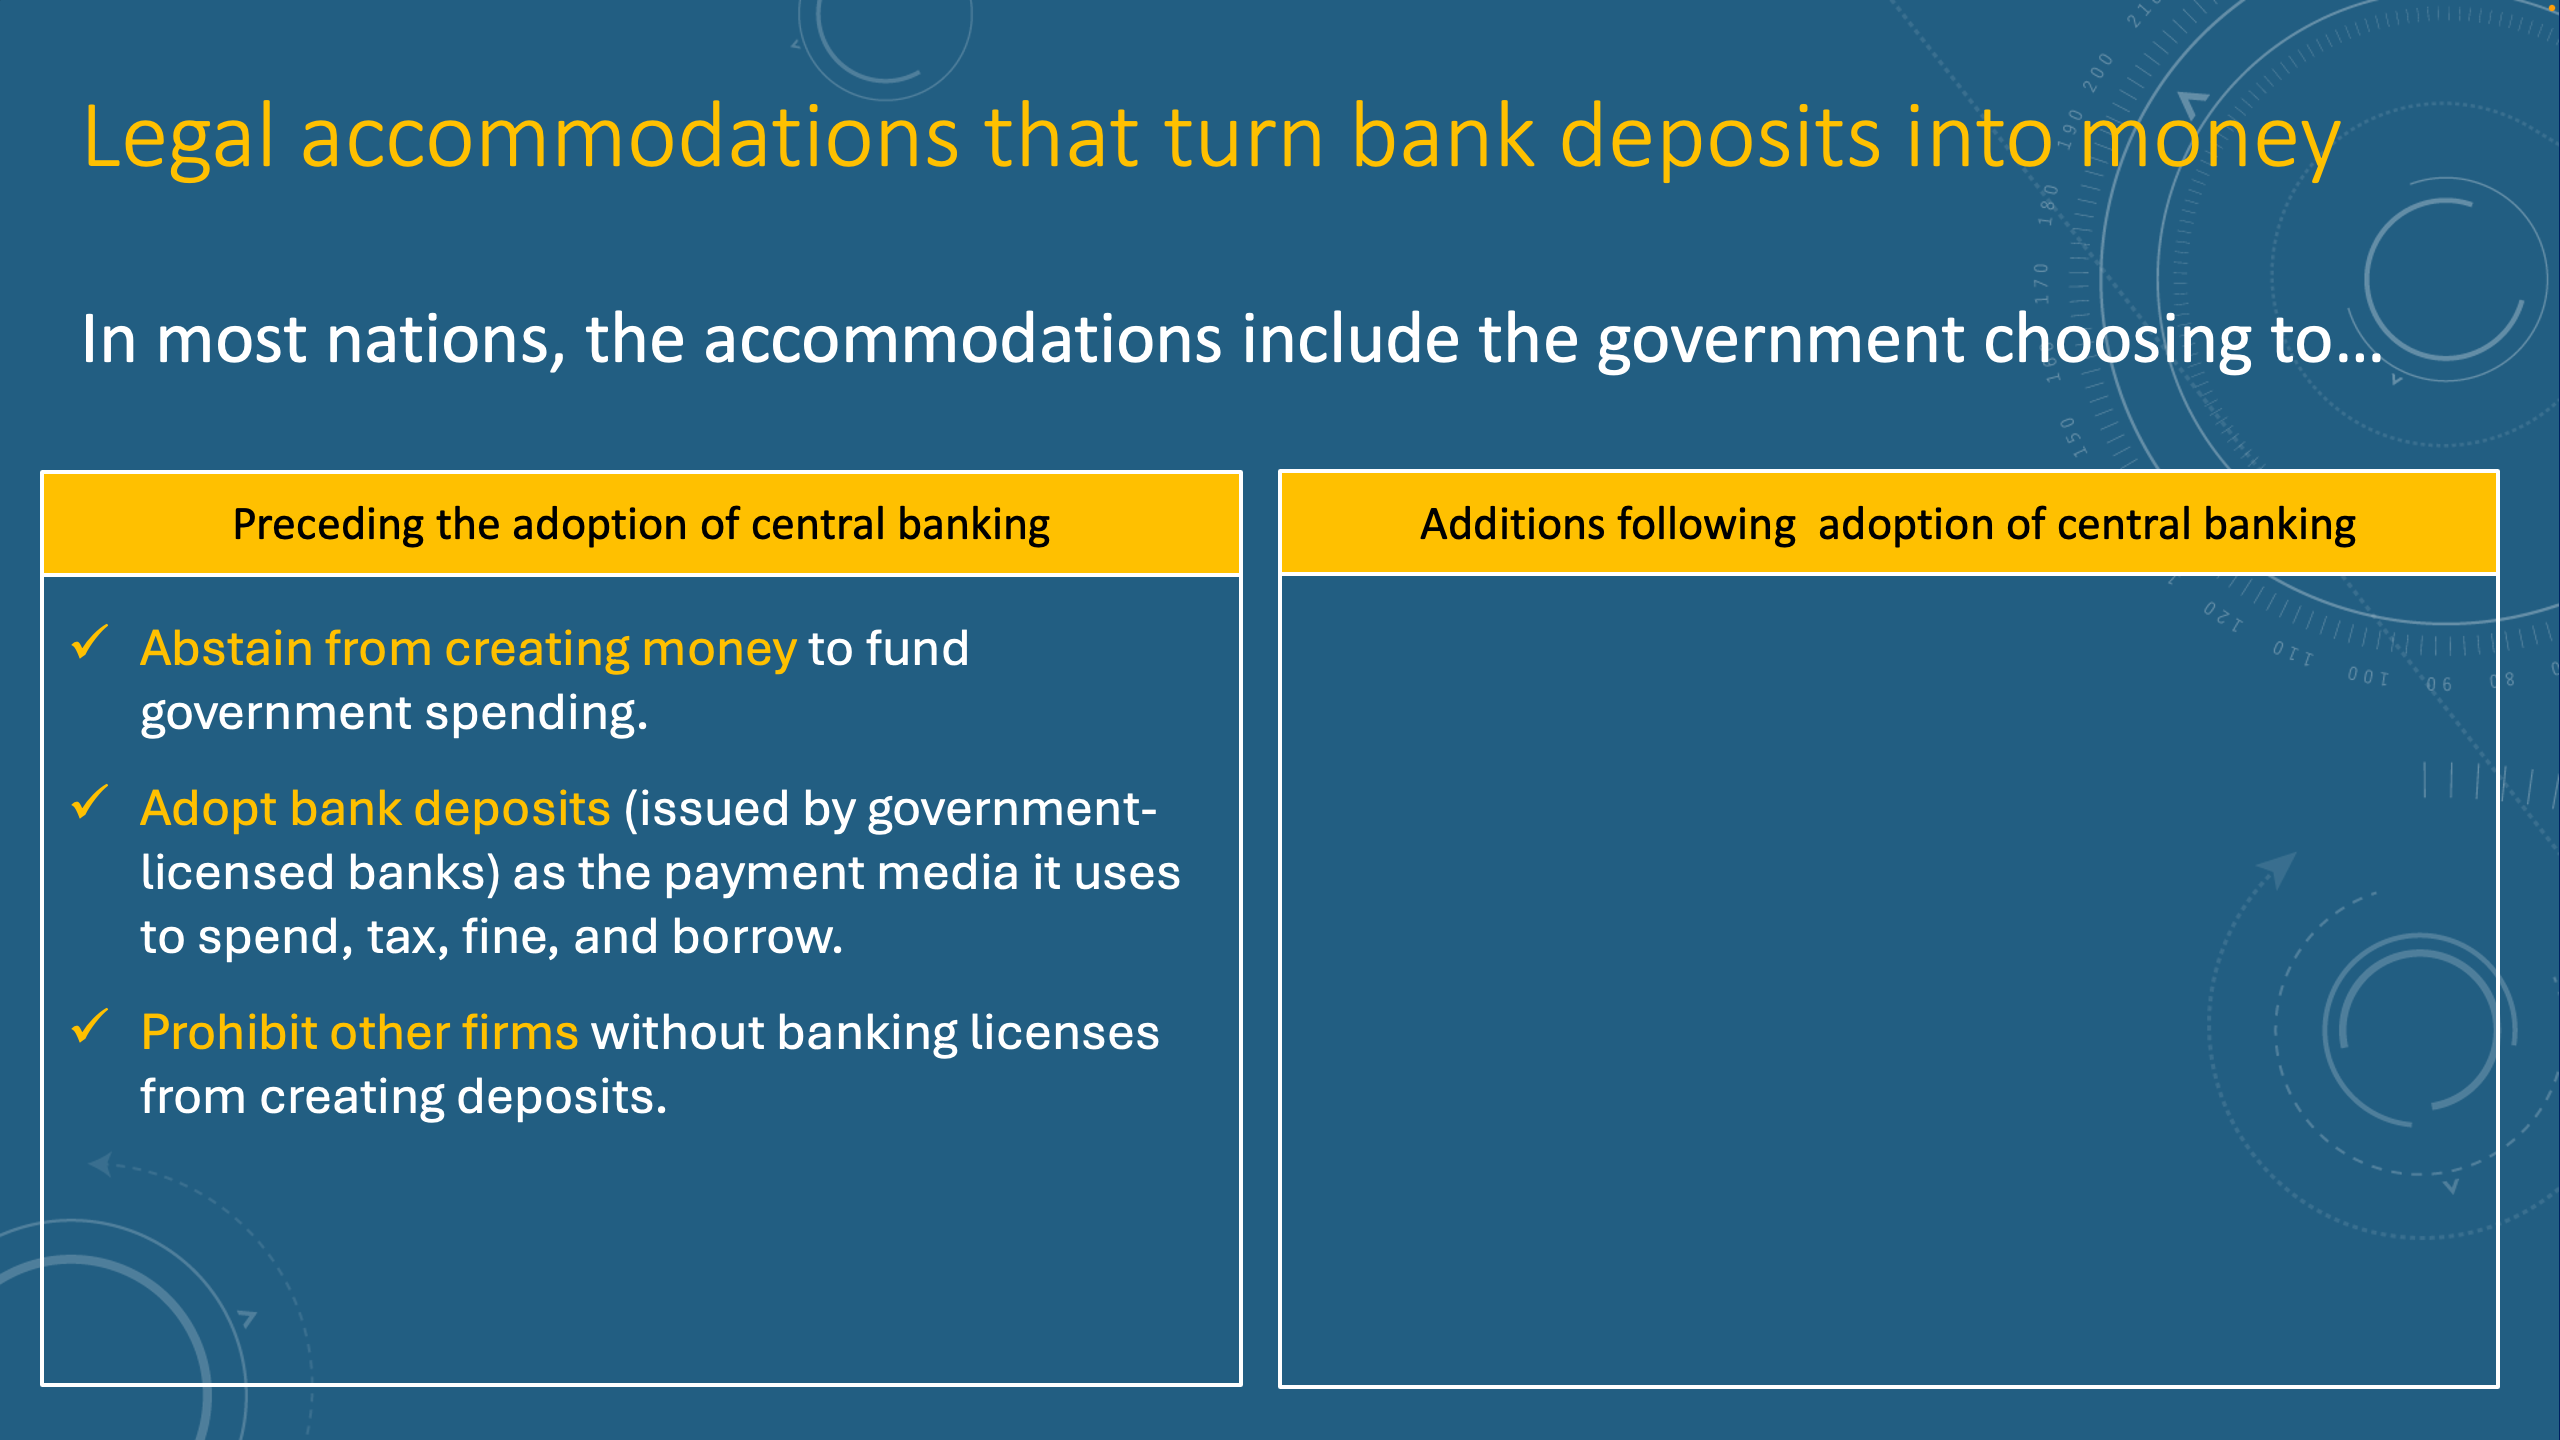
So going back to our legal accommodations, the third one is that the government then chooses to prohibit other firms that don’t have banking licenses from creating deposits, and this is what makes banks special, is that no other firms are allowed to do what they do, which is create deposits.
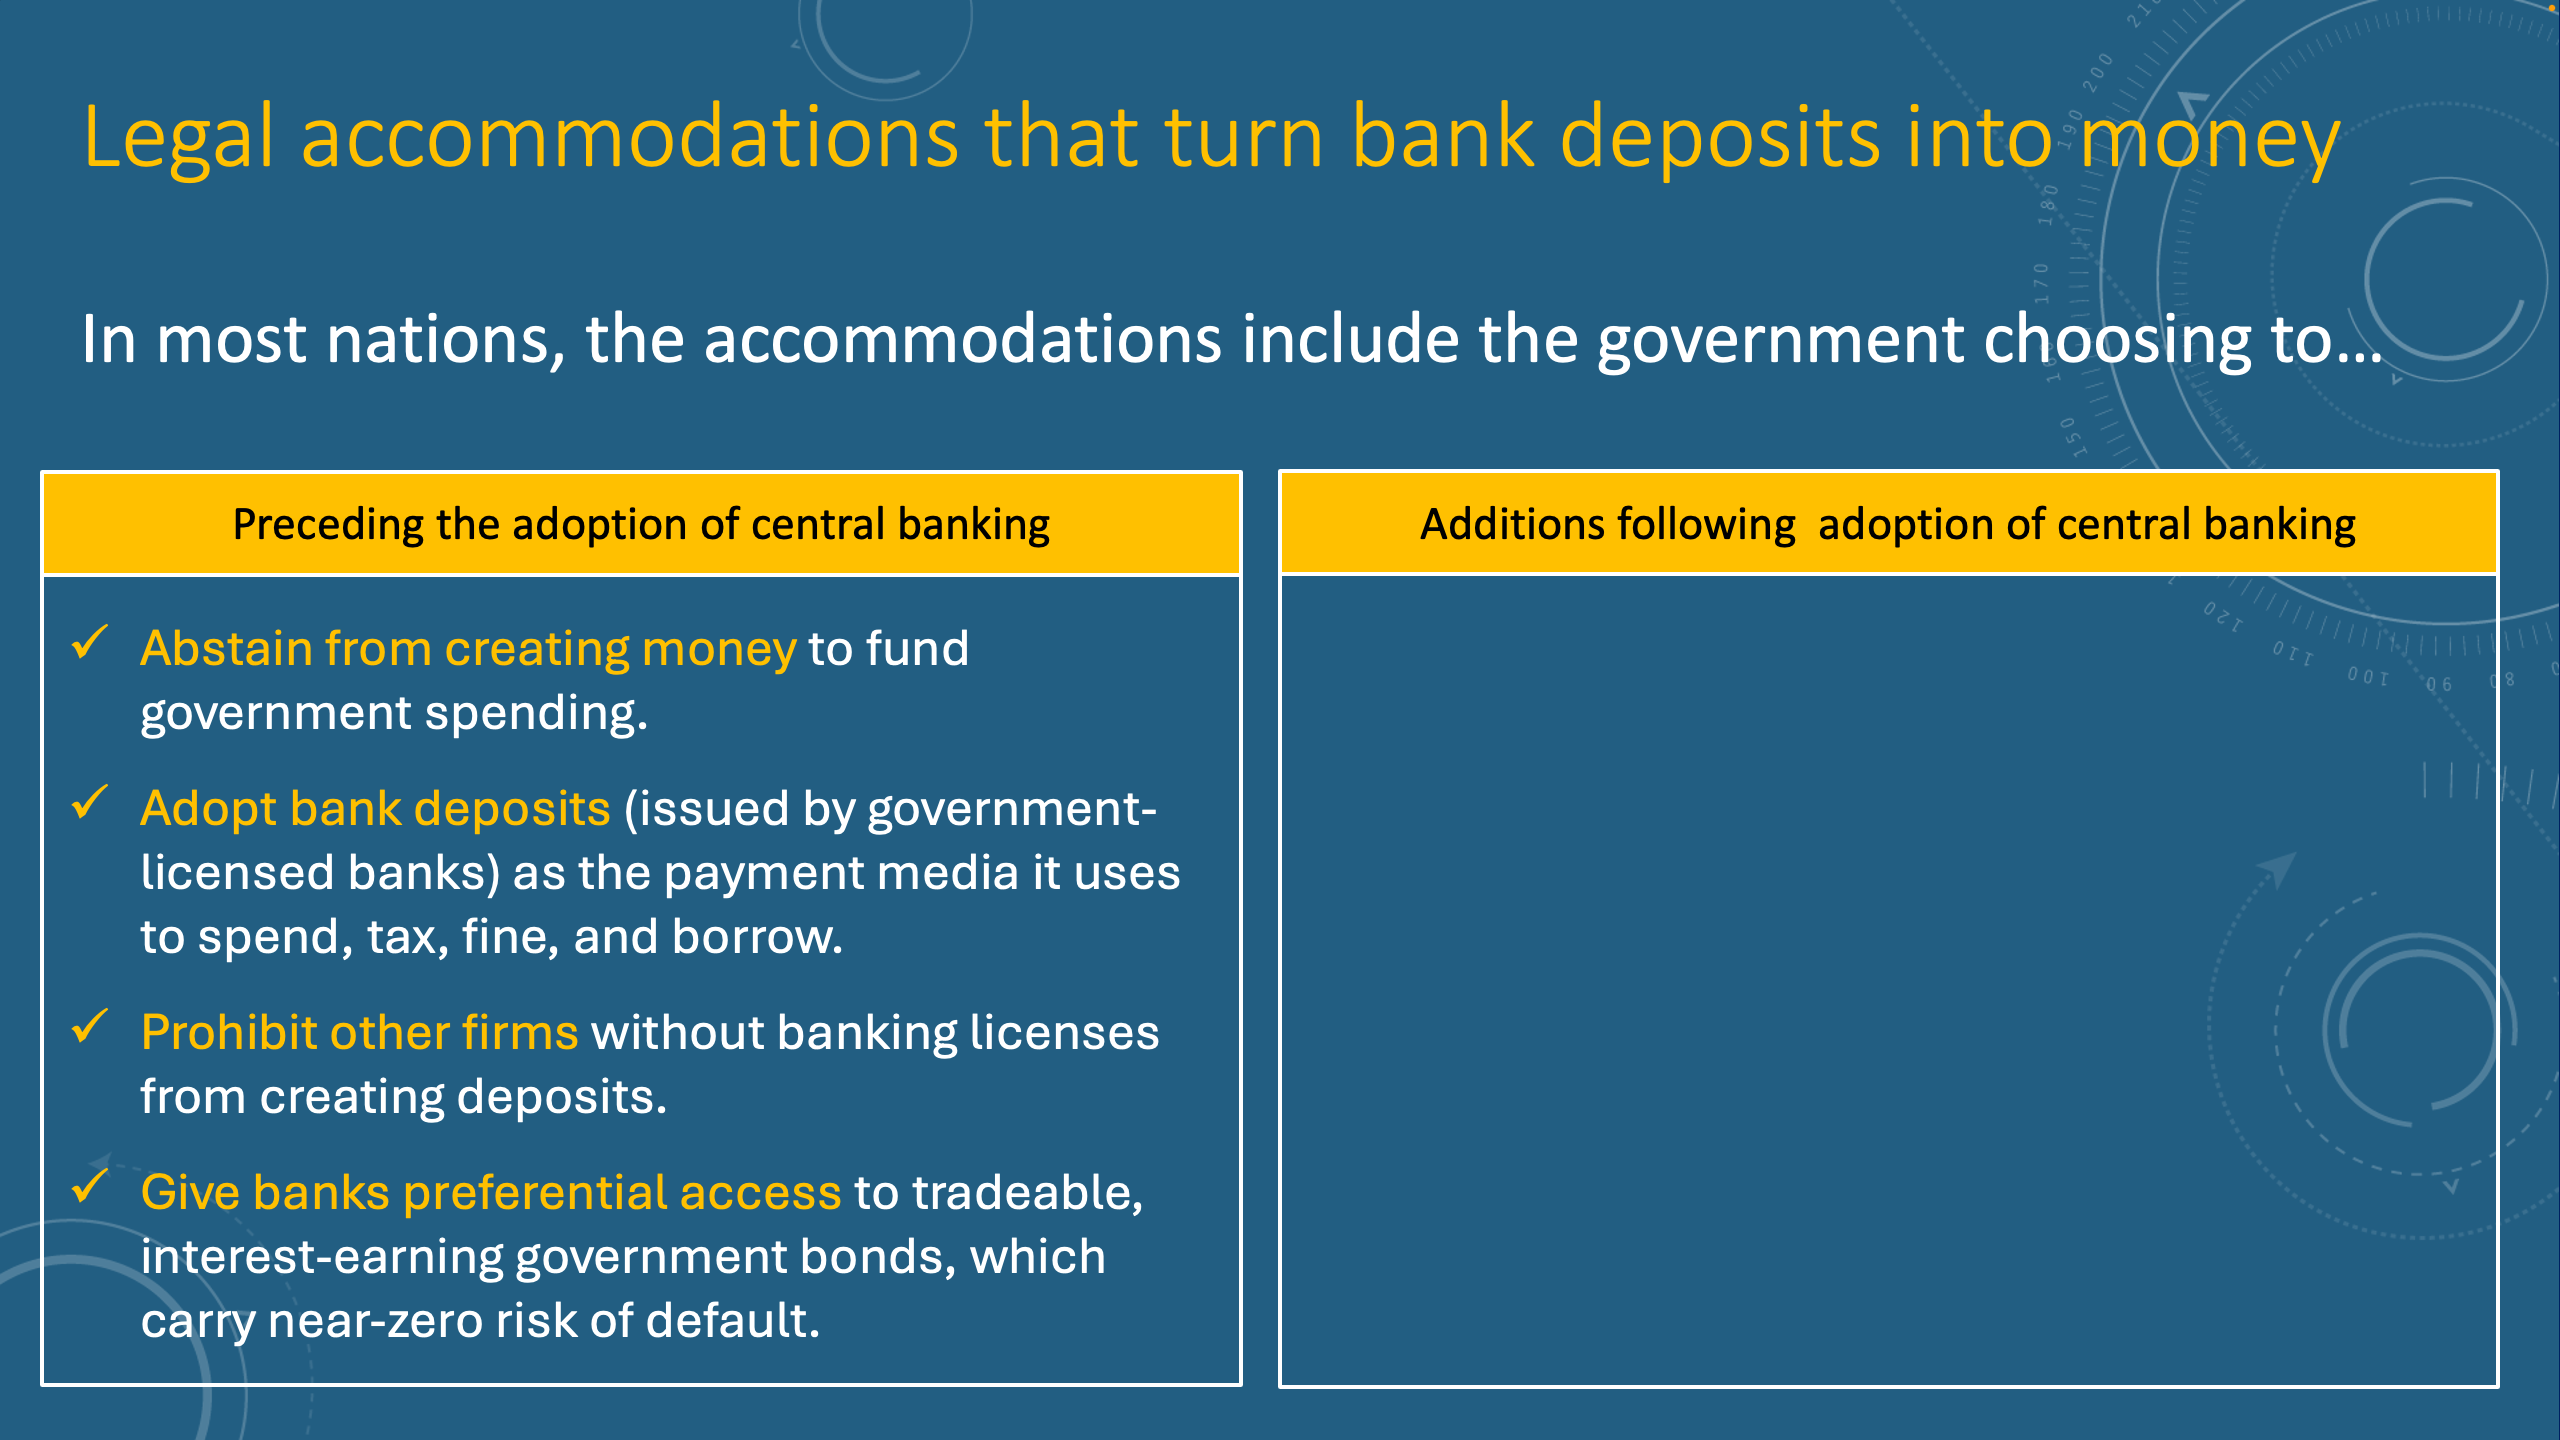
And last here, before the era of central banking, is that the governments give banks preferential access to tradable interest earning government bonds, which carry near zero risk of default. [The government gives banks these bonds as a form of borrowing from the banks. Upon receipt of the bonds, the banks newly create the deposits they give the government to spend, just as they newly create all the money they lend, as shown in the previous presentation about bank accounting.] So the reason why everybody trusts that bank deposits are going to have value is that banks have received commitments from the government that they will pay the banks interest, will pay the banks money in the future plus interest, and that presumably this money will make it possible for banks to always be good on their deposits. [This is what it means that the First and Second Banks of the United States were “banking on the full faith and credit” of the US government.]
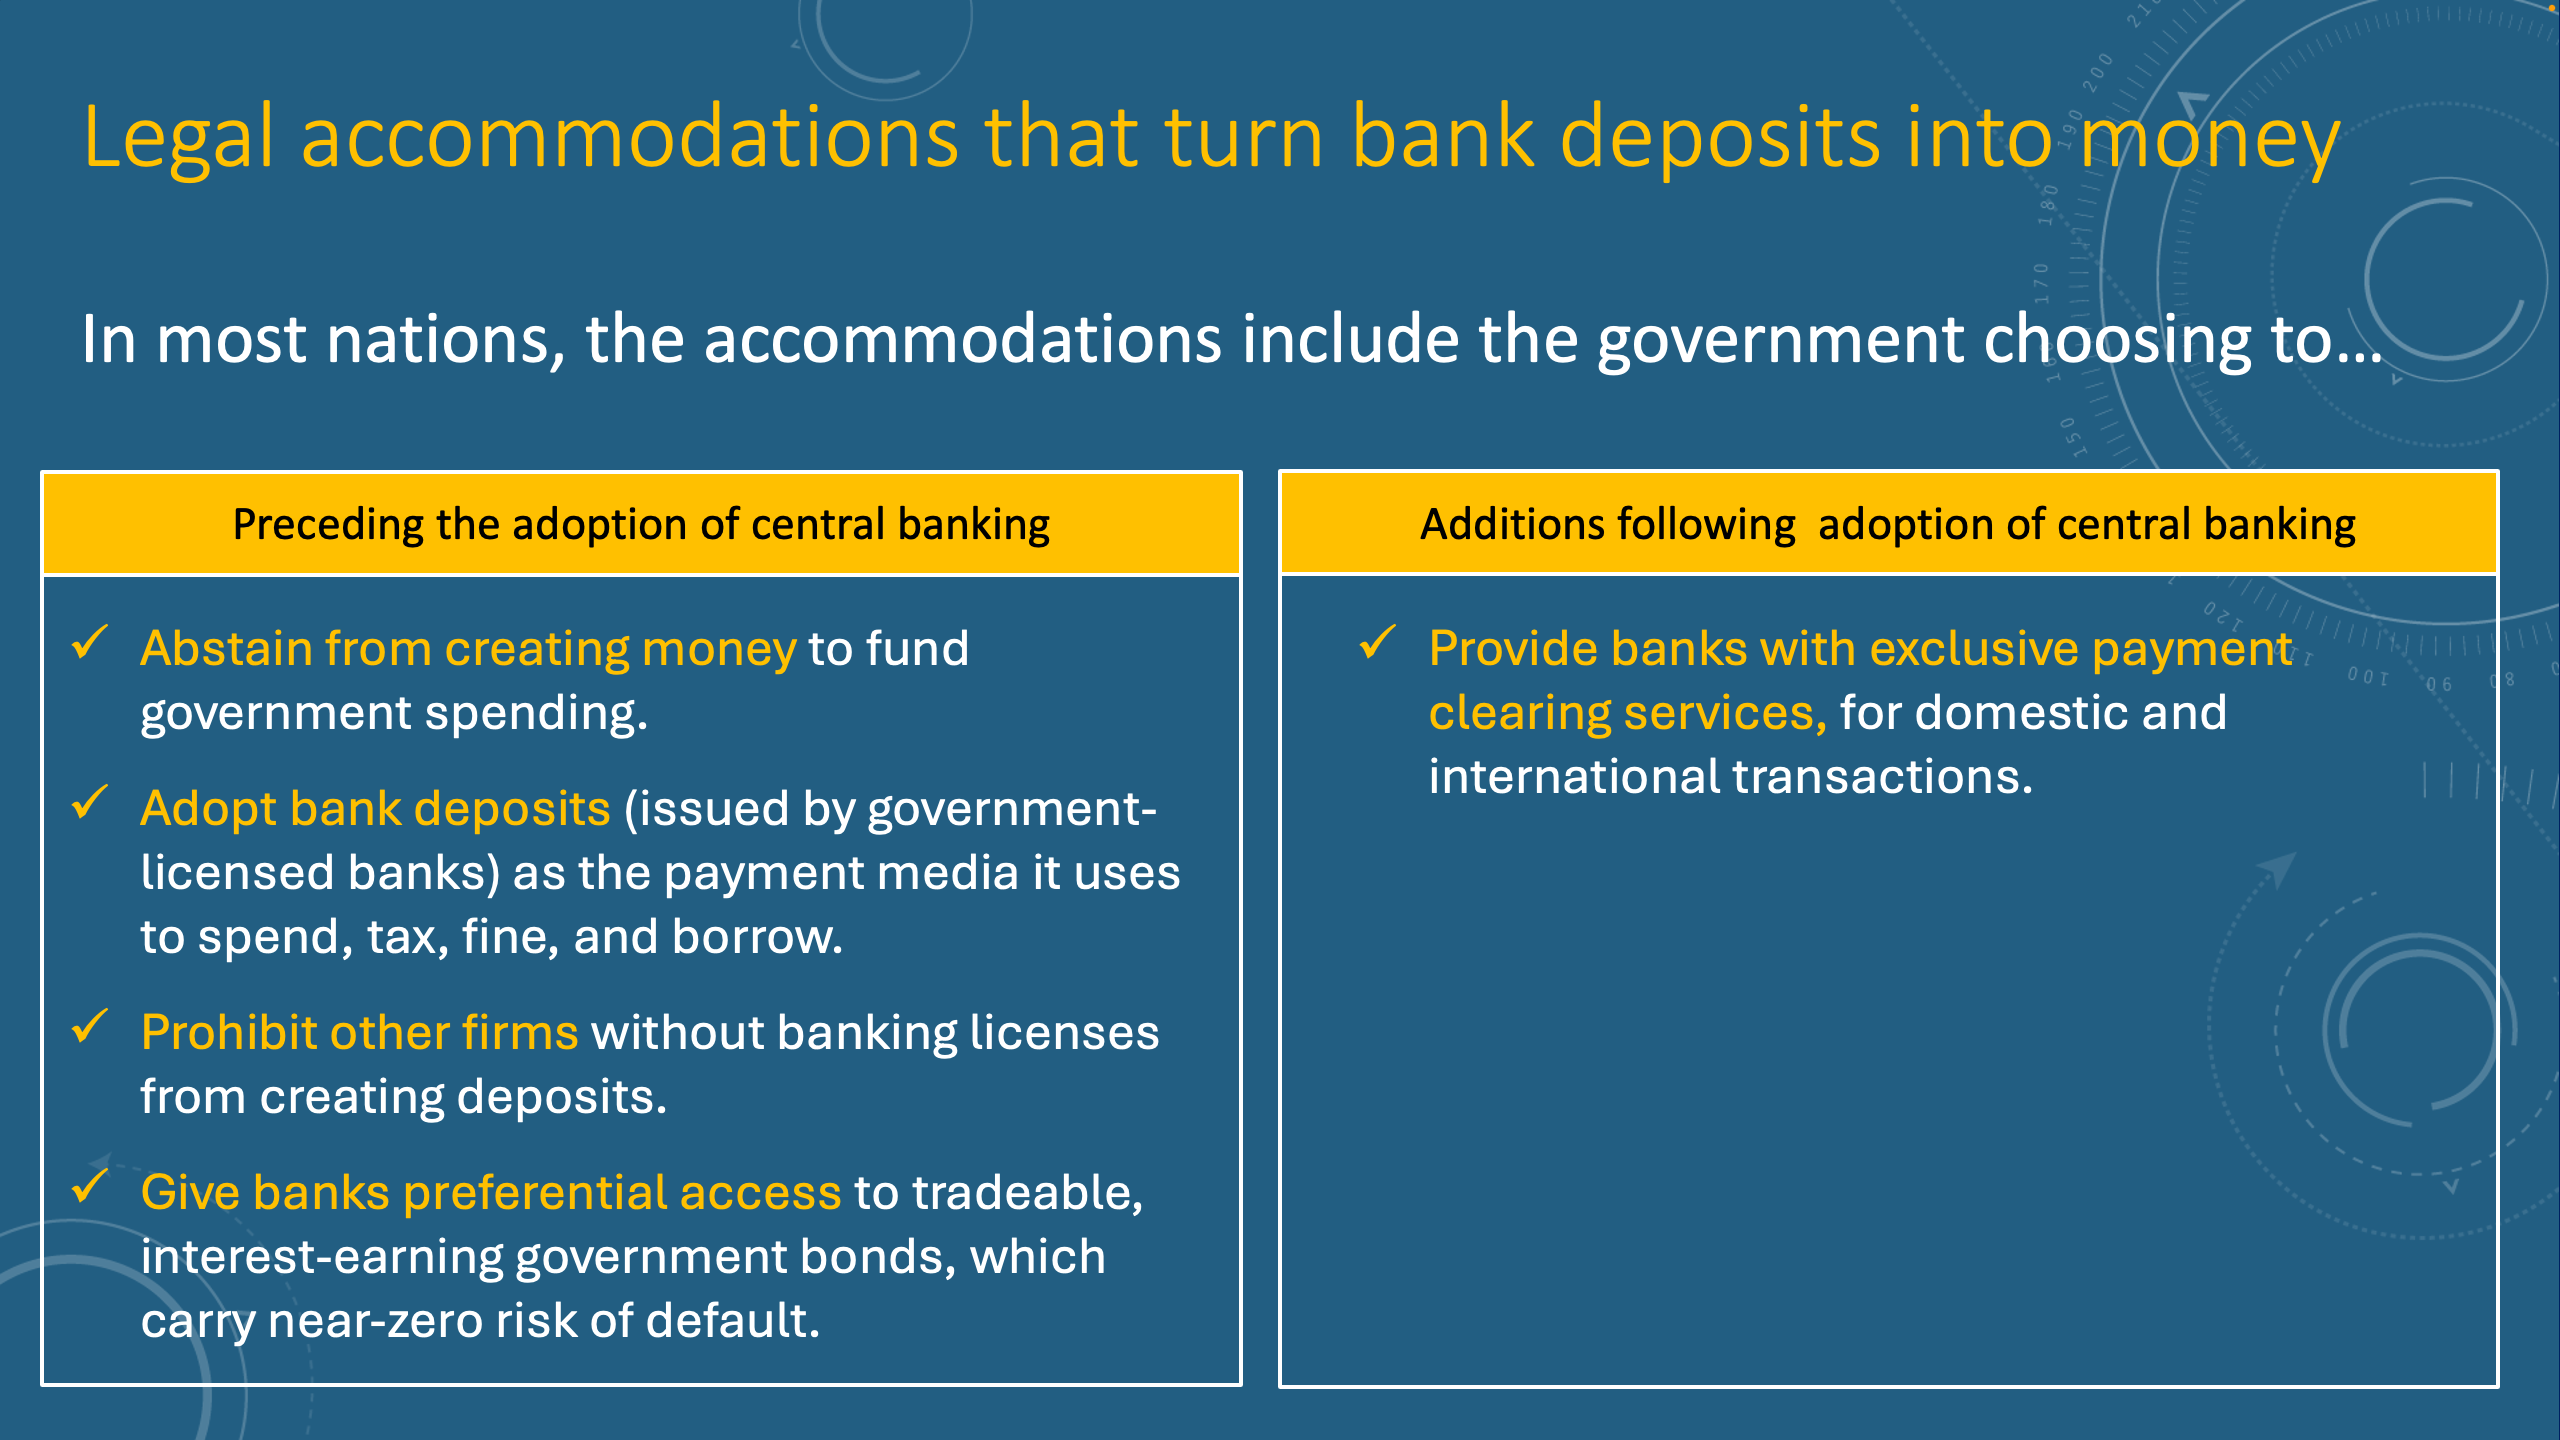
Moving now to accommodations that came in after central banking. Governments provide to the banking sector exclusive payment clearing services for domestic and international transactions. These include physical media for making payments like coins and bills, as I mentioned already, but also things like check clearing services and international transactions across borders, and many other services.
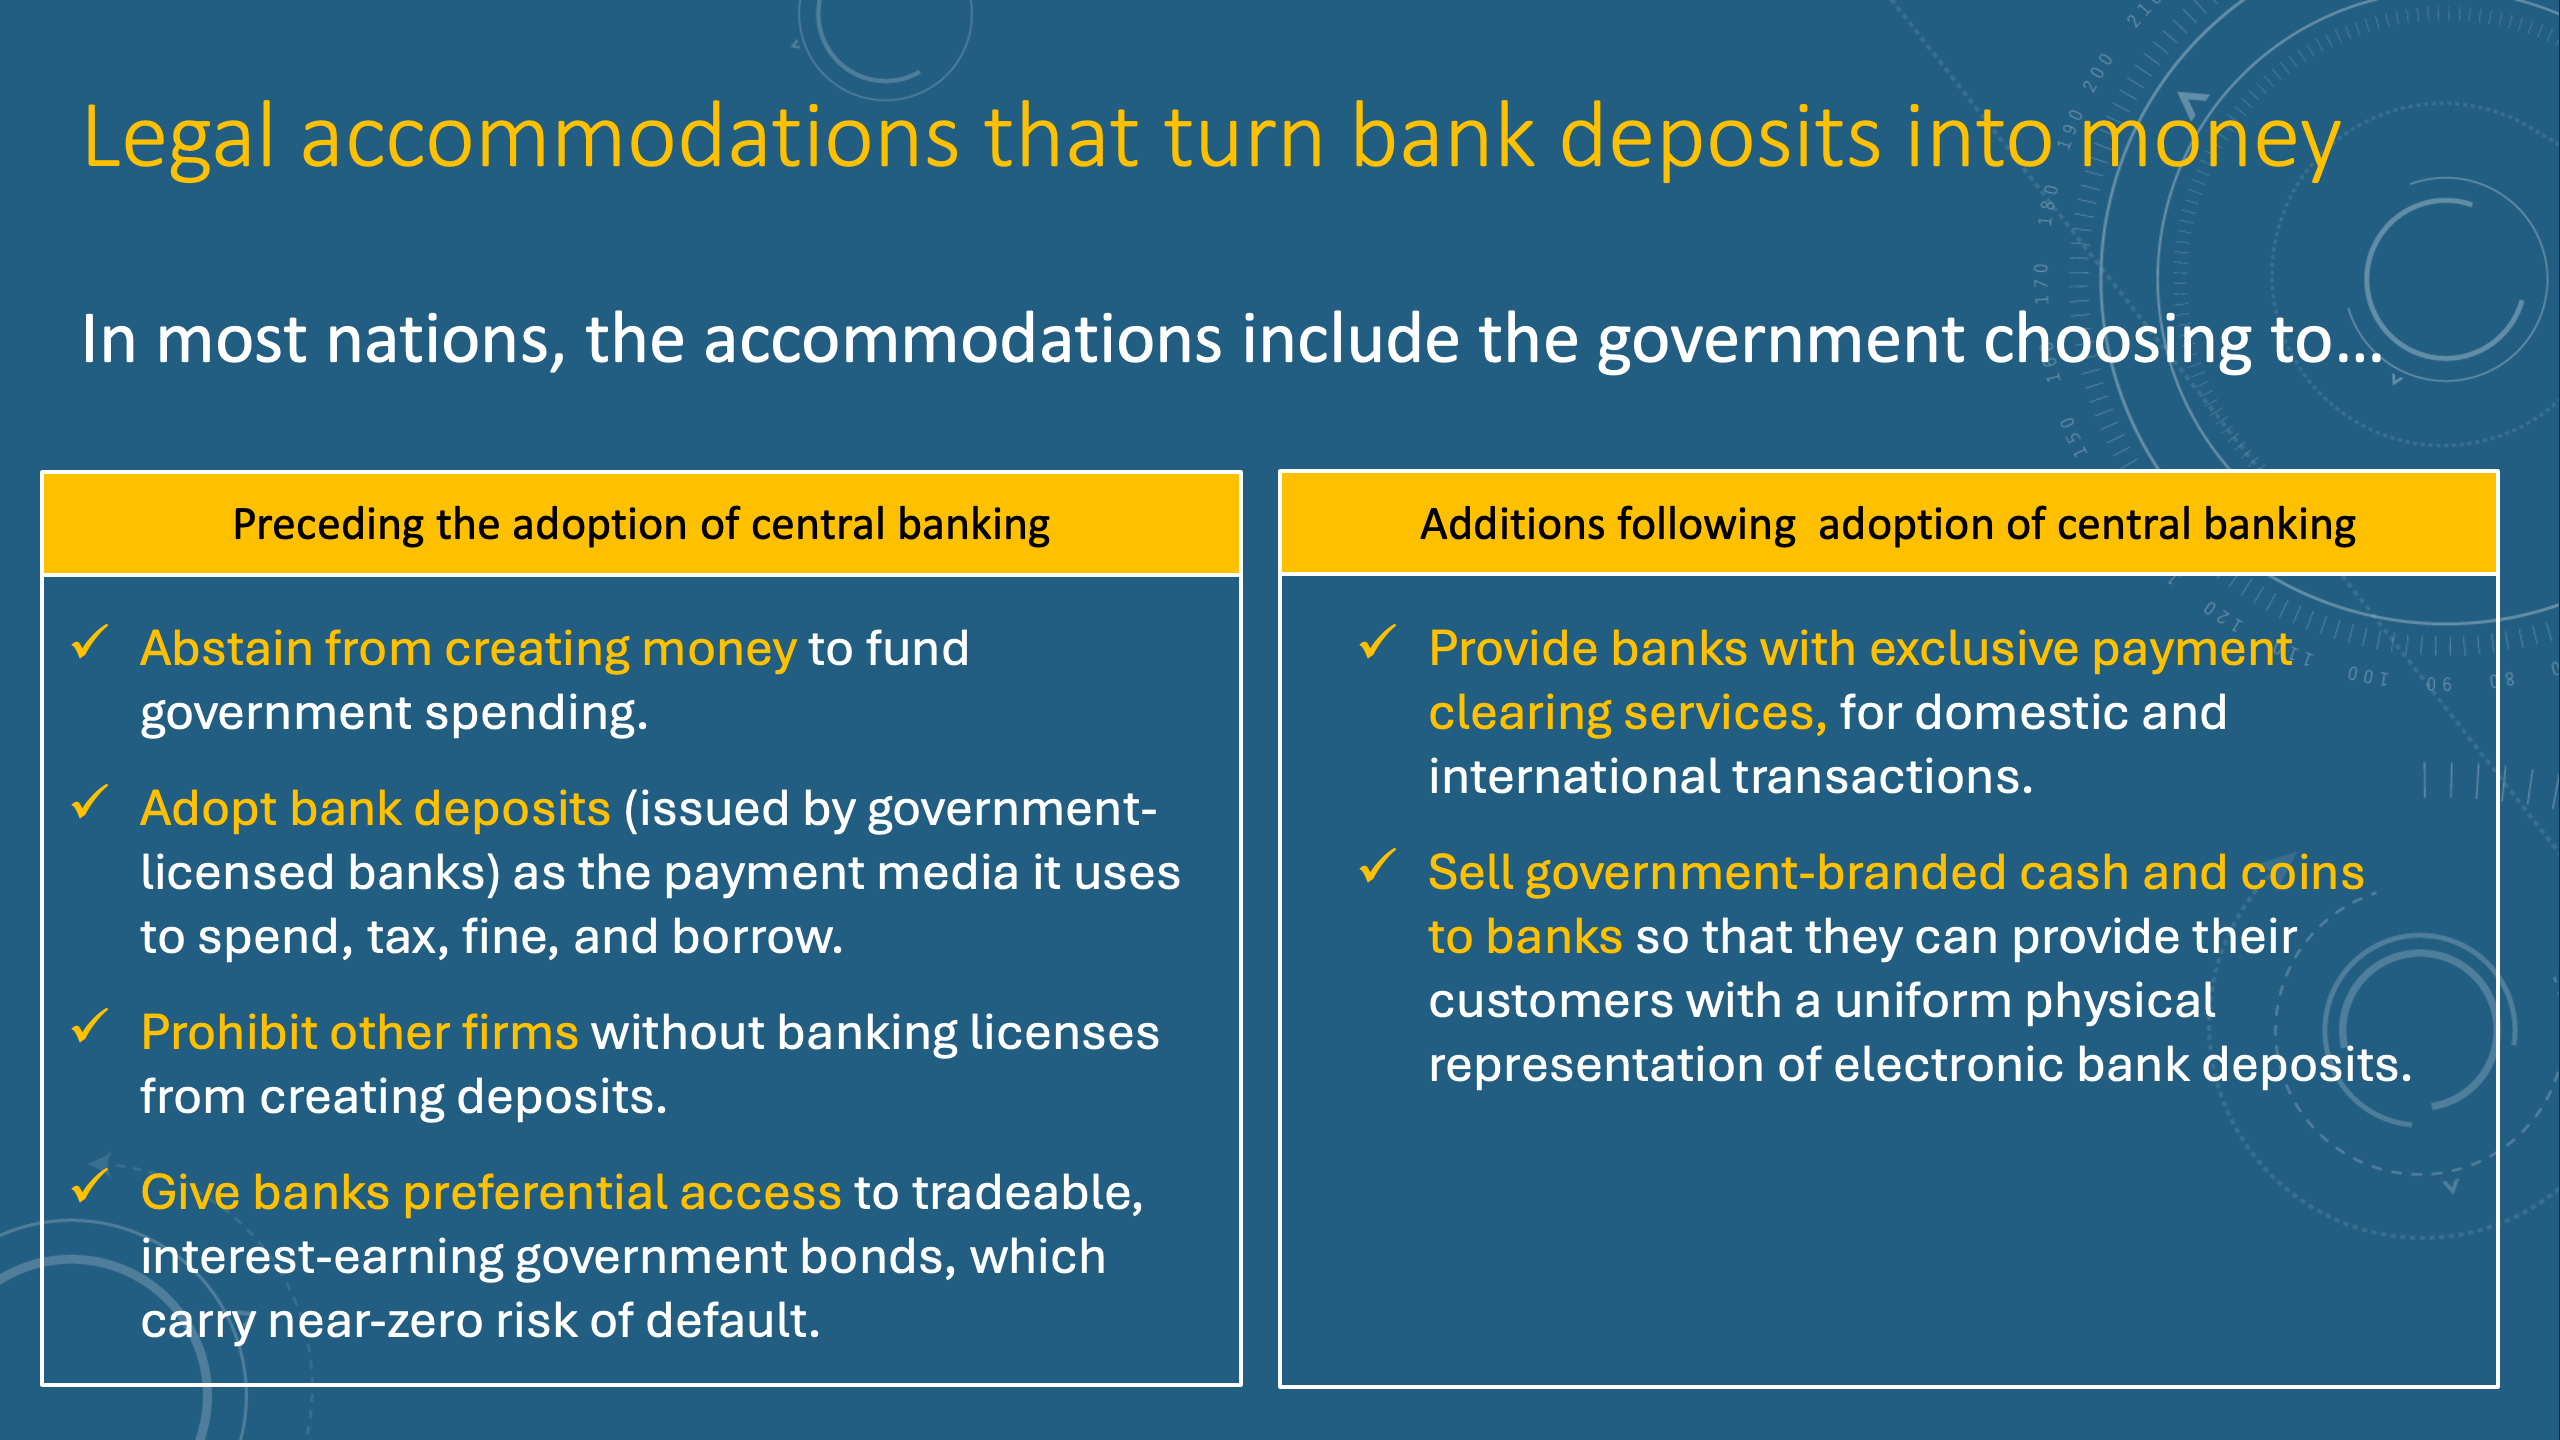
The government also sells government branded cash and coins to banks, as I just mentioned, so that they can provide their customers with a uniform physical representation of electronic bank deposits.
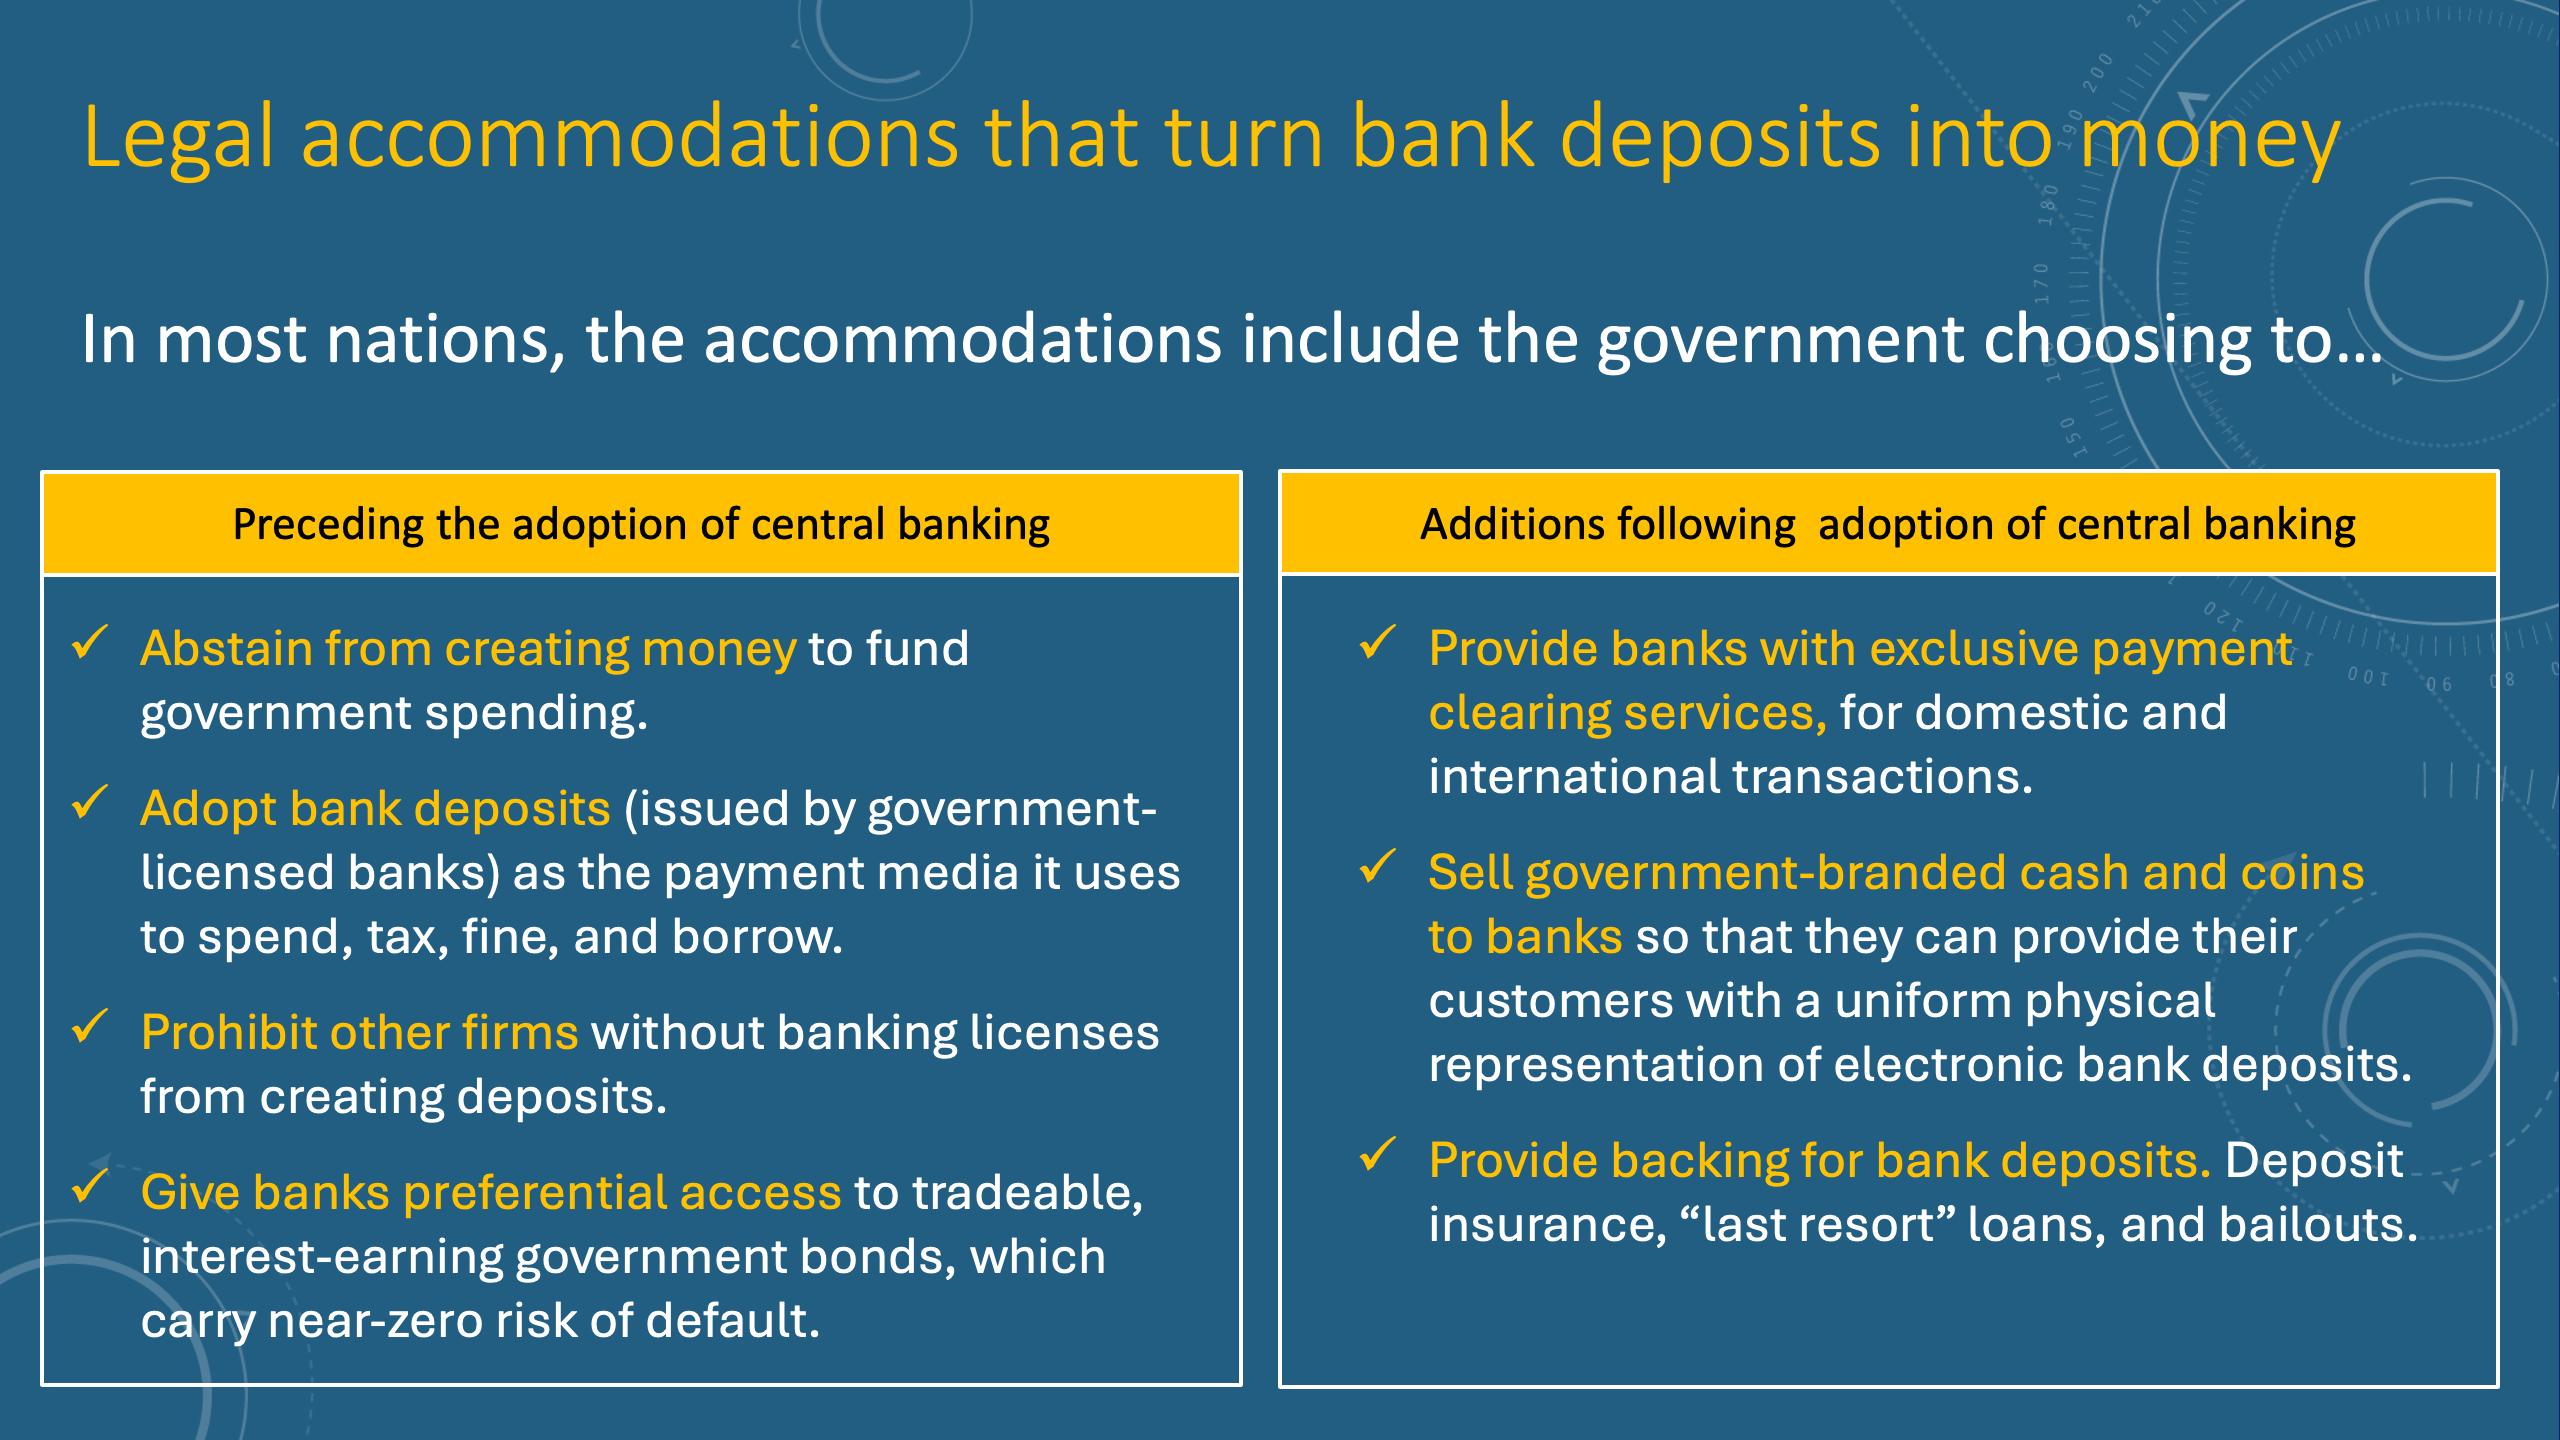
And then finally, governments provide banks with deposit insurance and last resort loans, and ultimately, in many cases, bailouts that ensure that bank deposits continue to function as money and to be considered a reliable supply of money for the country.
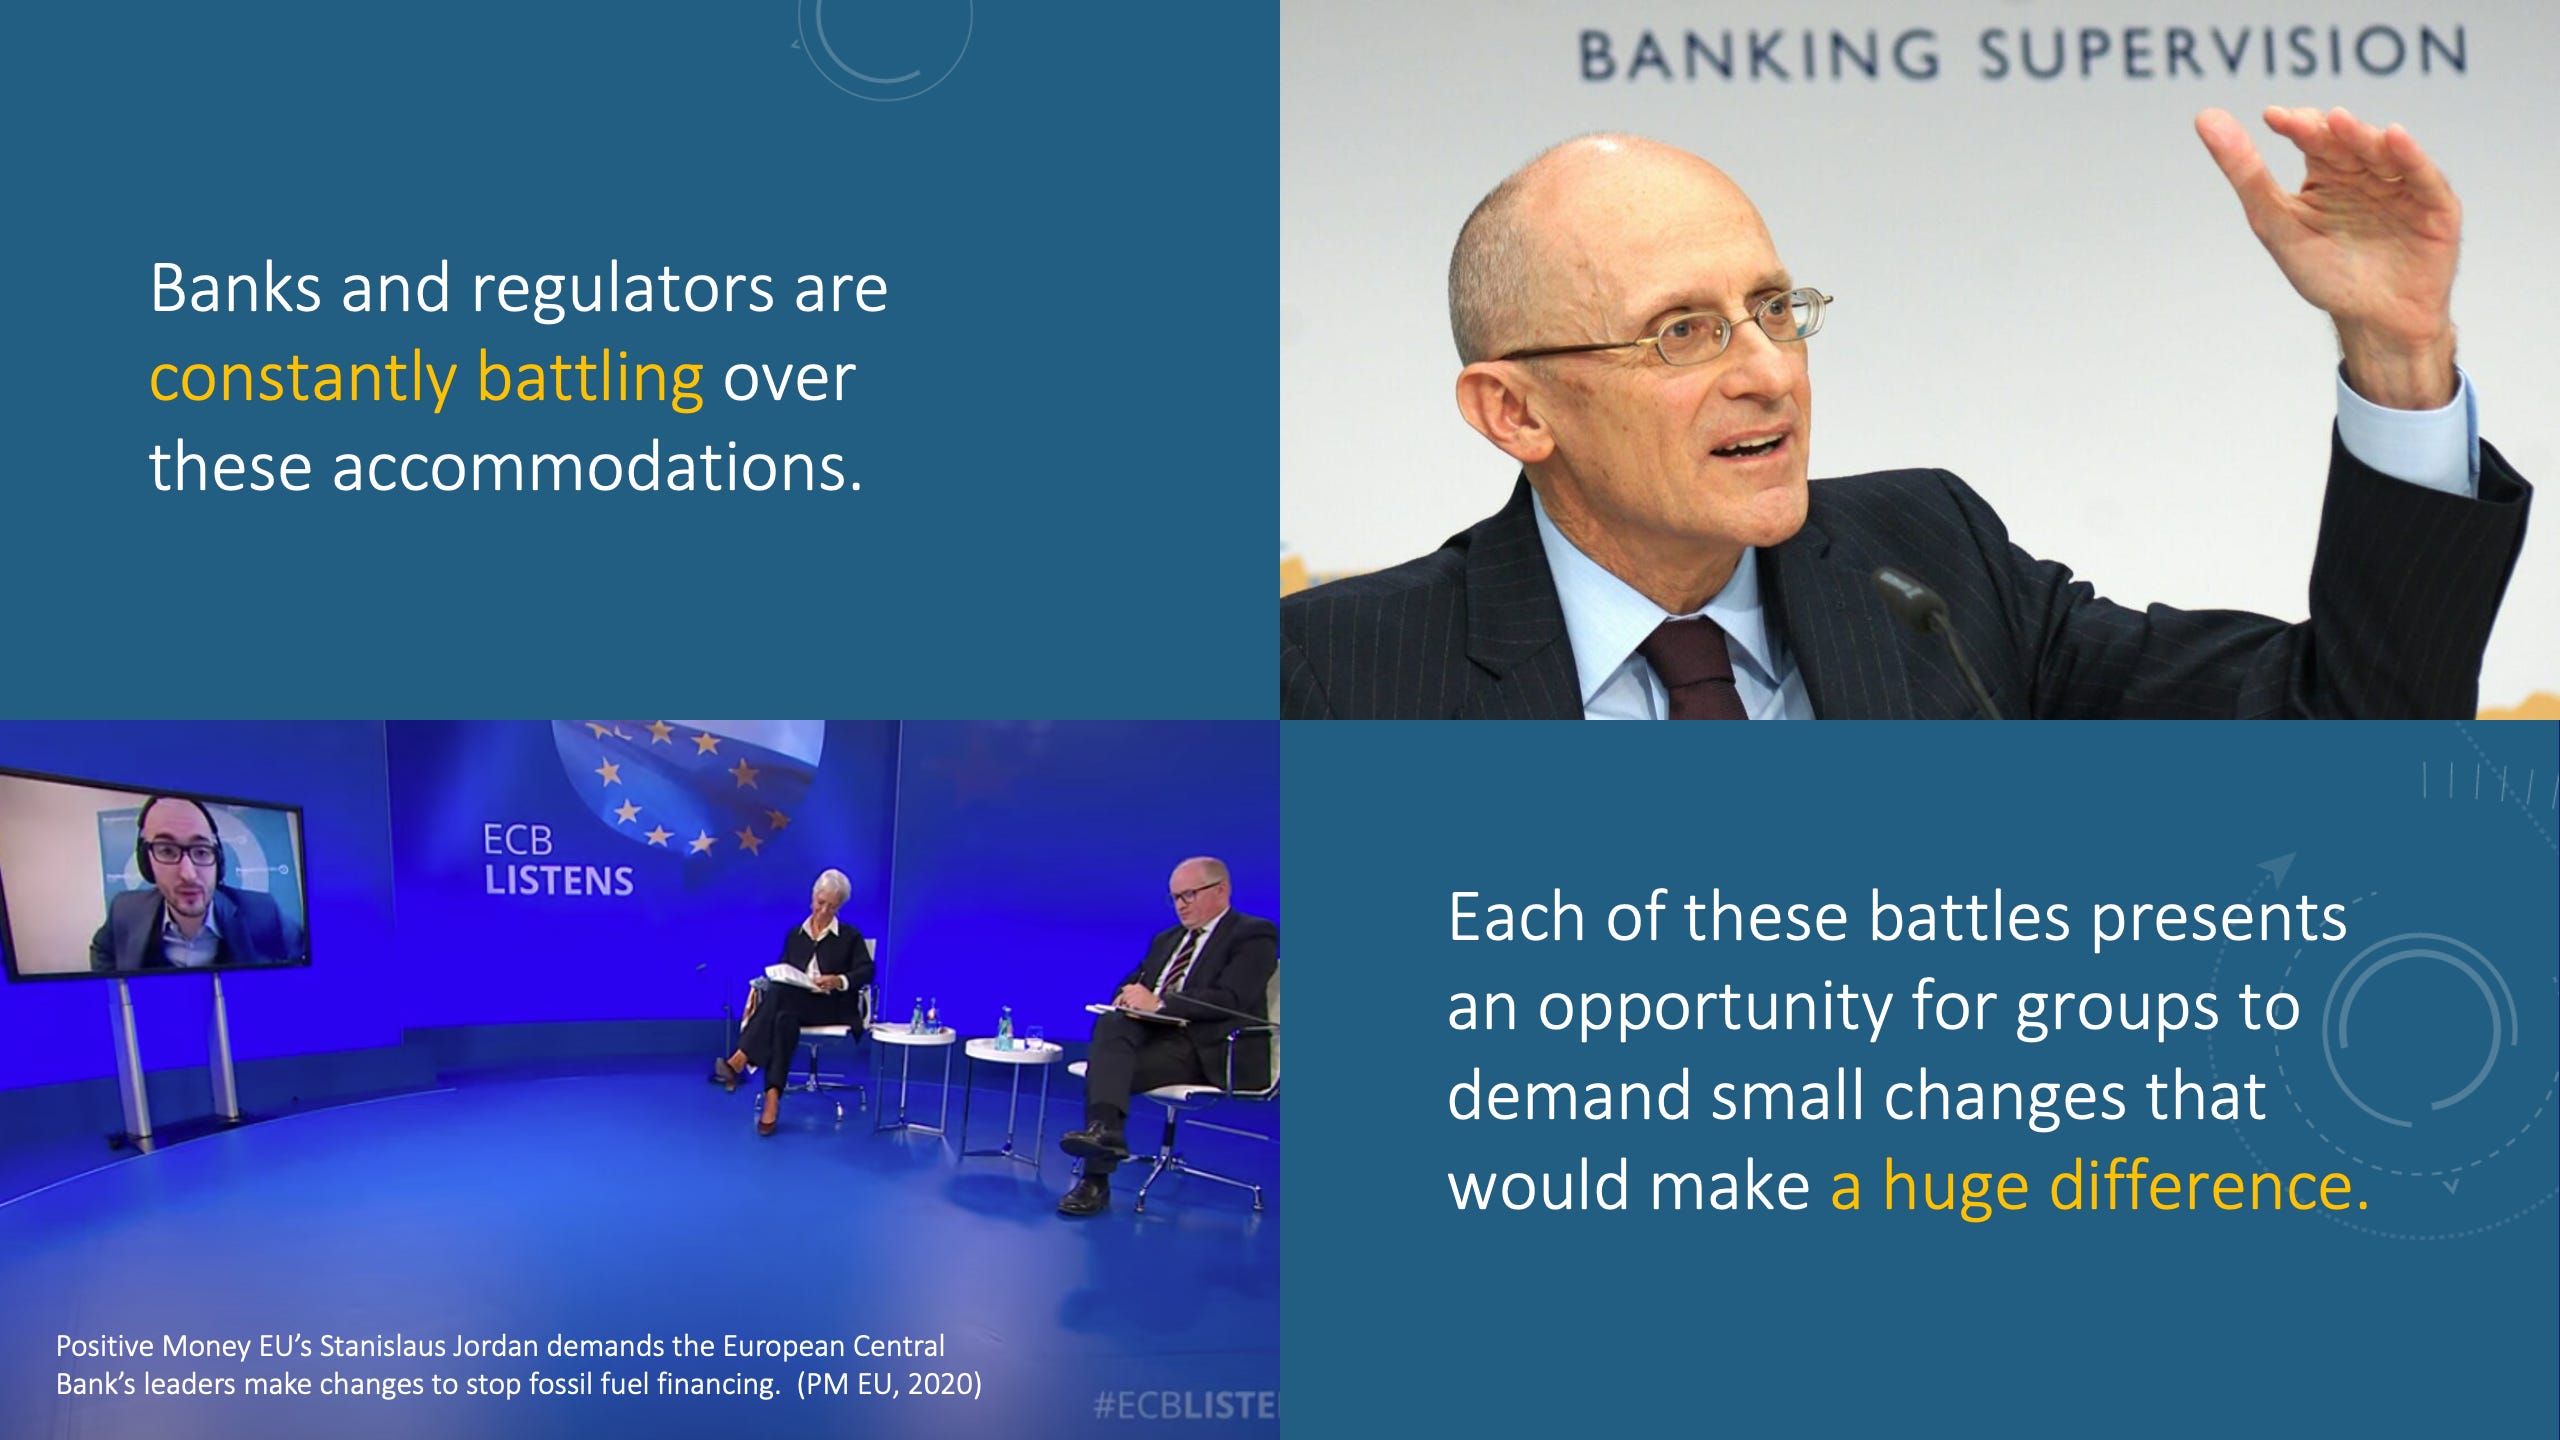
What’s important about understanding that bank’s ability to create money is formed out of these numerous legal accommodations and public services is to be able to see and understand that actually these accommodations are being constantly contested. Banks and regulators are battling over these accommodations in hearings and public filings and in the court of public opinion and so on. But we often don’t recognize it because the battles are about technocratic minutia like capital adequacy regulations or risk buffers or collateral frameworks or financial technologies or stable coins, that may be one that you’ve heard about recently in the news. In each of these cases, what the battle is really about is whether or not banks’ exclusive privileges will be sustained, expanded, contracted, or otherwise modified, which affects how much money banks can create and how much they can profit. And in the case of stable coins, what’s happening there is that – I read the trade press and the newsletters from the banking lobby in the United States and in Europe – and you know what they are concerned about with stable coins is that stable coins might allow financial technology companies to offer a competitor to their deposit creation, and thus they would lose some of their exclusive privilege to be the ones creating the money supply of the country. So what’s valuable about understanding that each of these contests ultimately are about how much money banks can create, who they can create it for, who else is allowed to create money, and how much they can profit also from that is that you can understand that each of these battles presents an opportunity for groups to demand changes, big changes but also just small changes to the system that would make a huge difference.
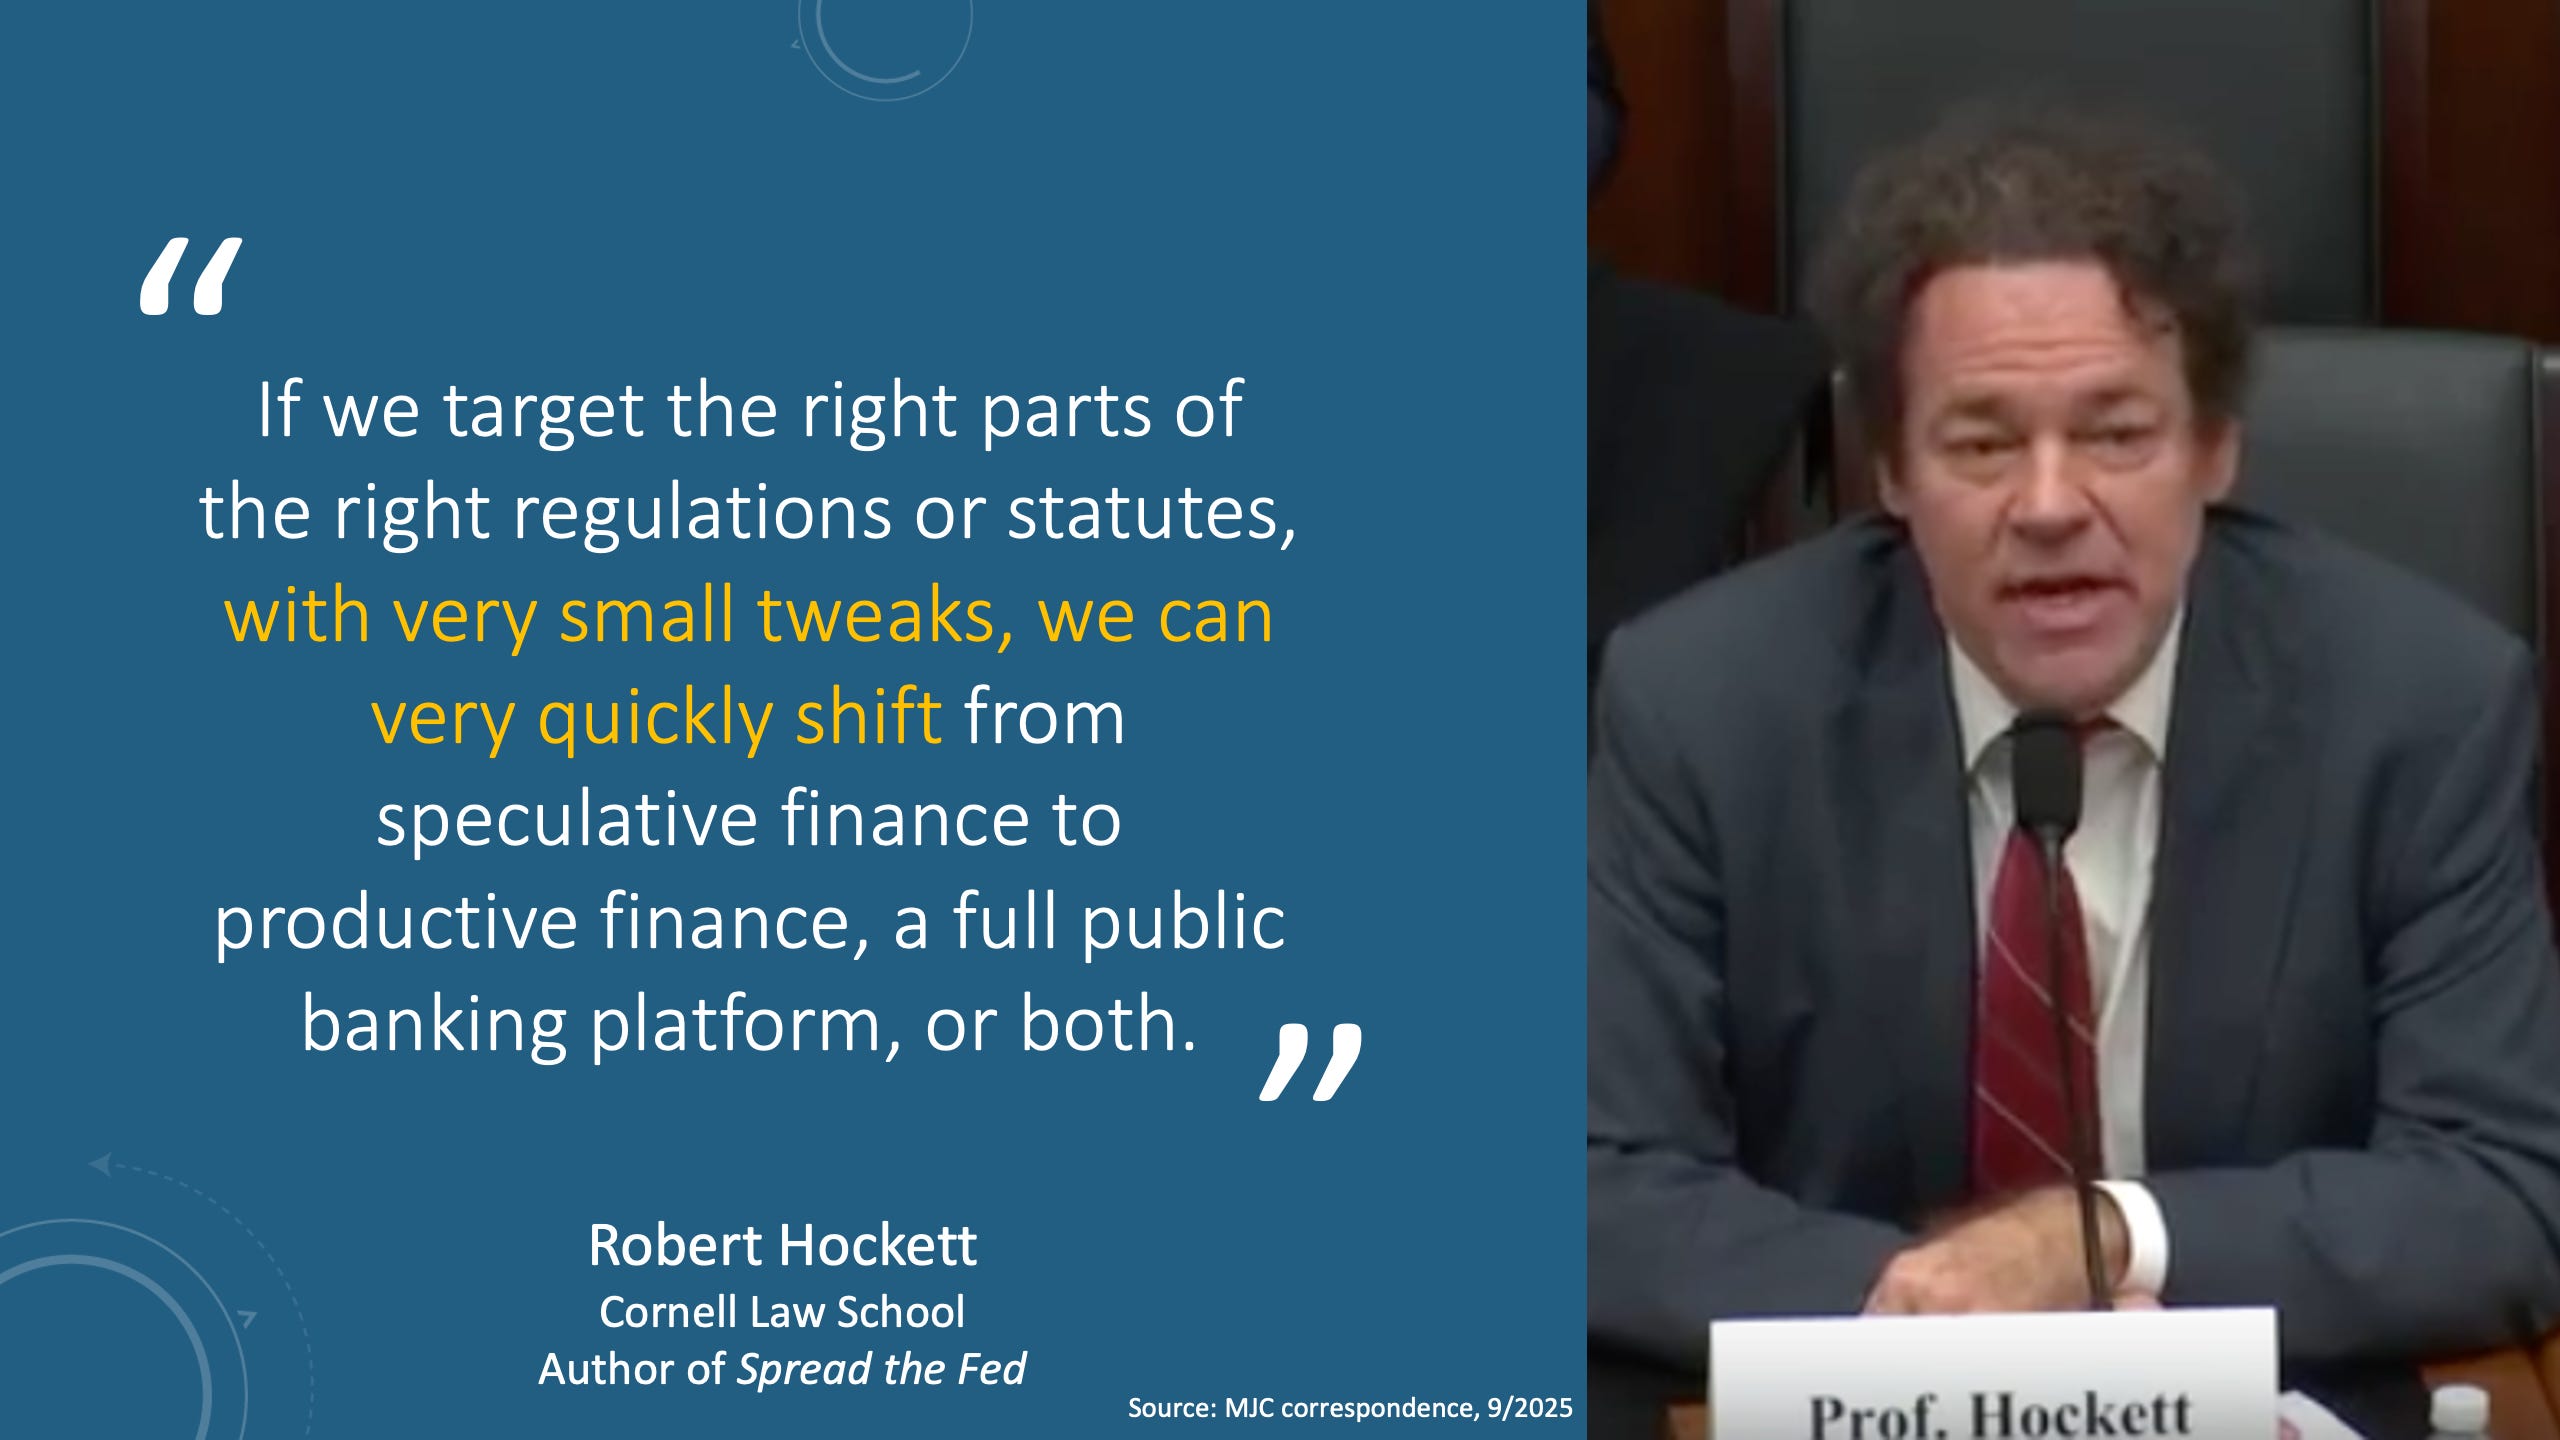
And that’s not just theoretical. You can actually see this in the way that the banking industry engages in these battles, they don’t typically ask for big, wholesale changes to the system. Rather, they target one little rule, one little law, statute at a time, and in that way, slowly change the entire system, typically to their advantage. Now the banking professor at Cornell Law School, Bob Hockett is a well renowned expert on the banking system and has submitted multiple draft policies to Congress that have been entered in Congress with bipartisan support that would change the way bank money creation works today. He validates this idea. He says, “If we target the right parts of the right regulations or statues statutes with very small tweaks, we can very quickly shift from speculative finance to productive finance a full public banking platform, or both.” And what he’s saying in there is that, if we would prefer that bank money creation be flowing into farms and factories and the and stabilizing the economy, rather than into speculation on Wall Street and real estate and so on, just a few small changes to the laws would make that possible.
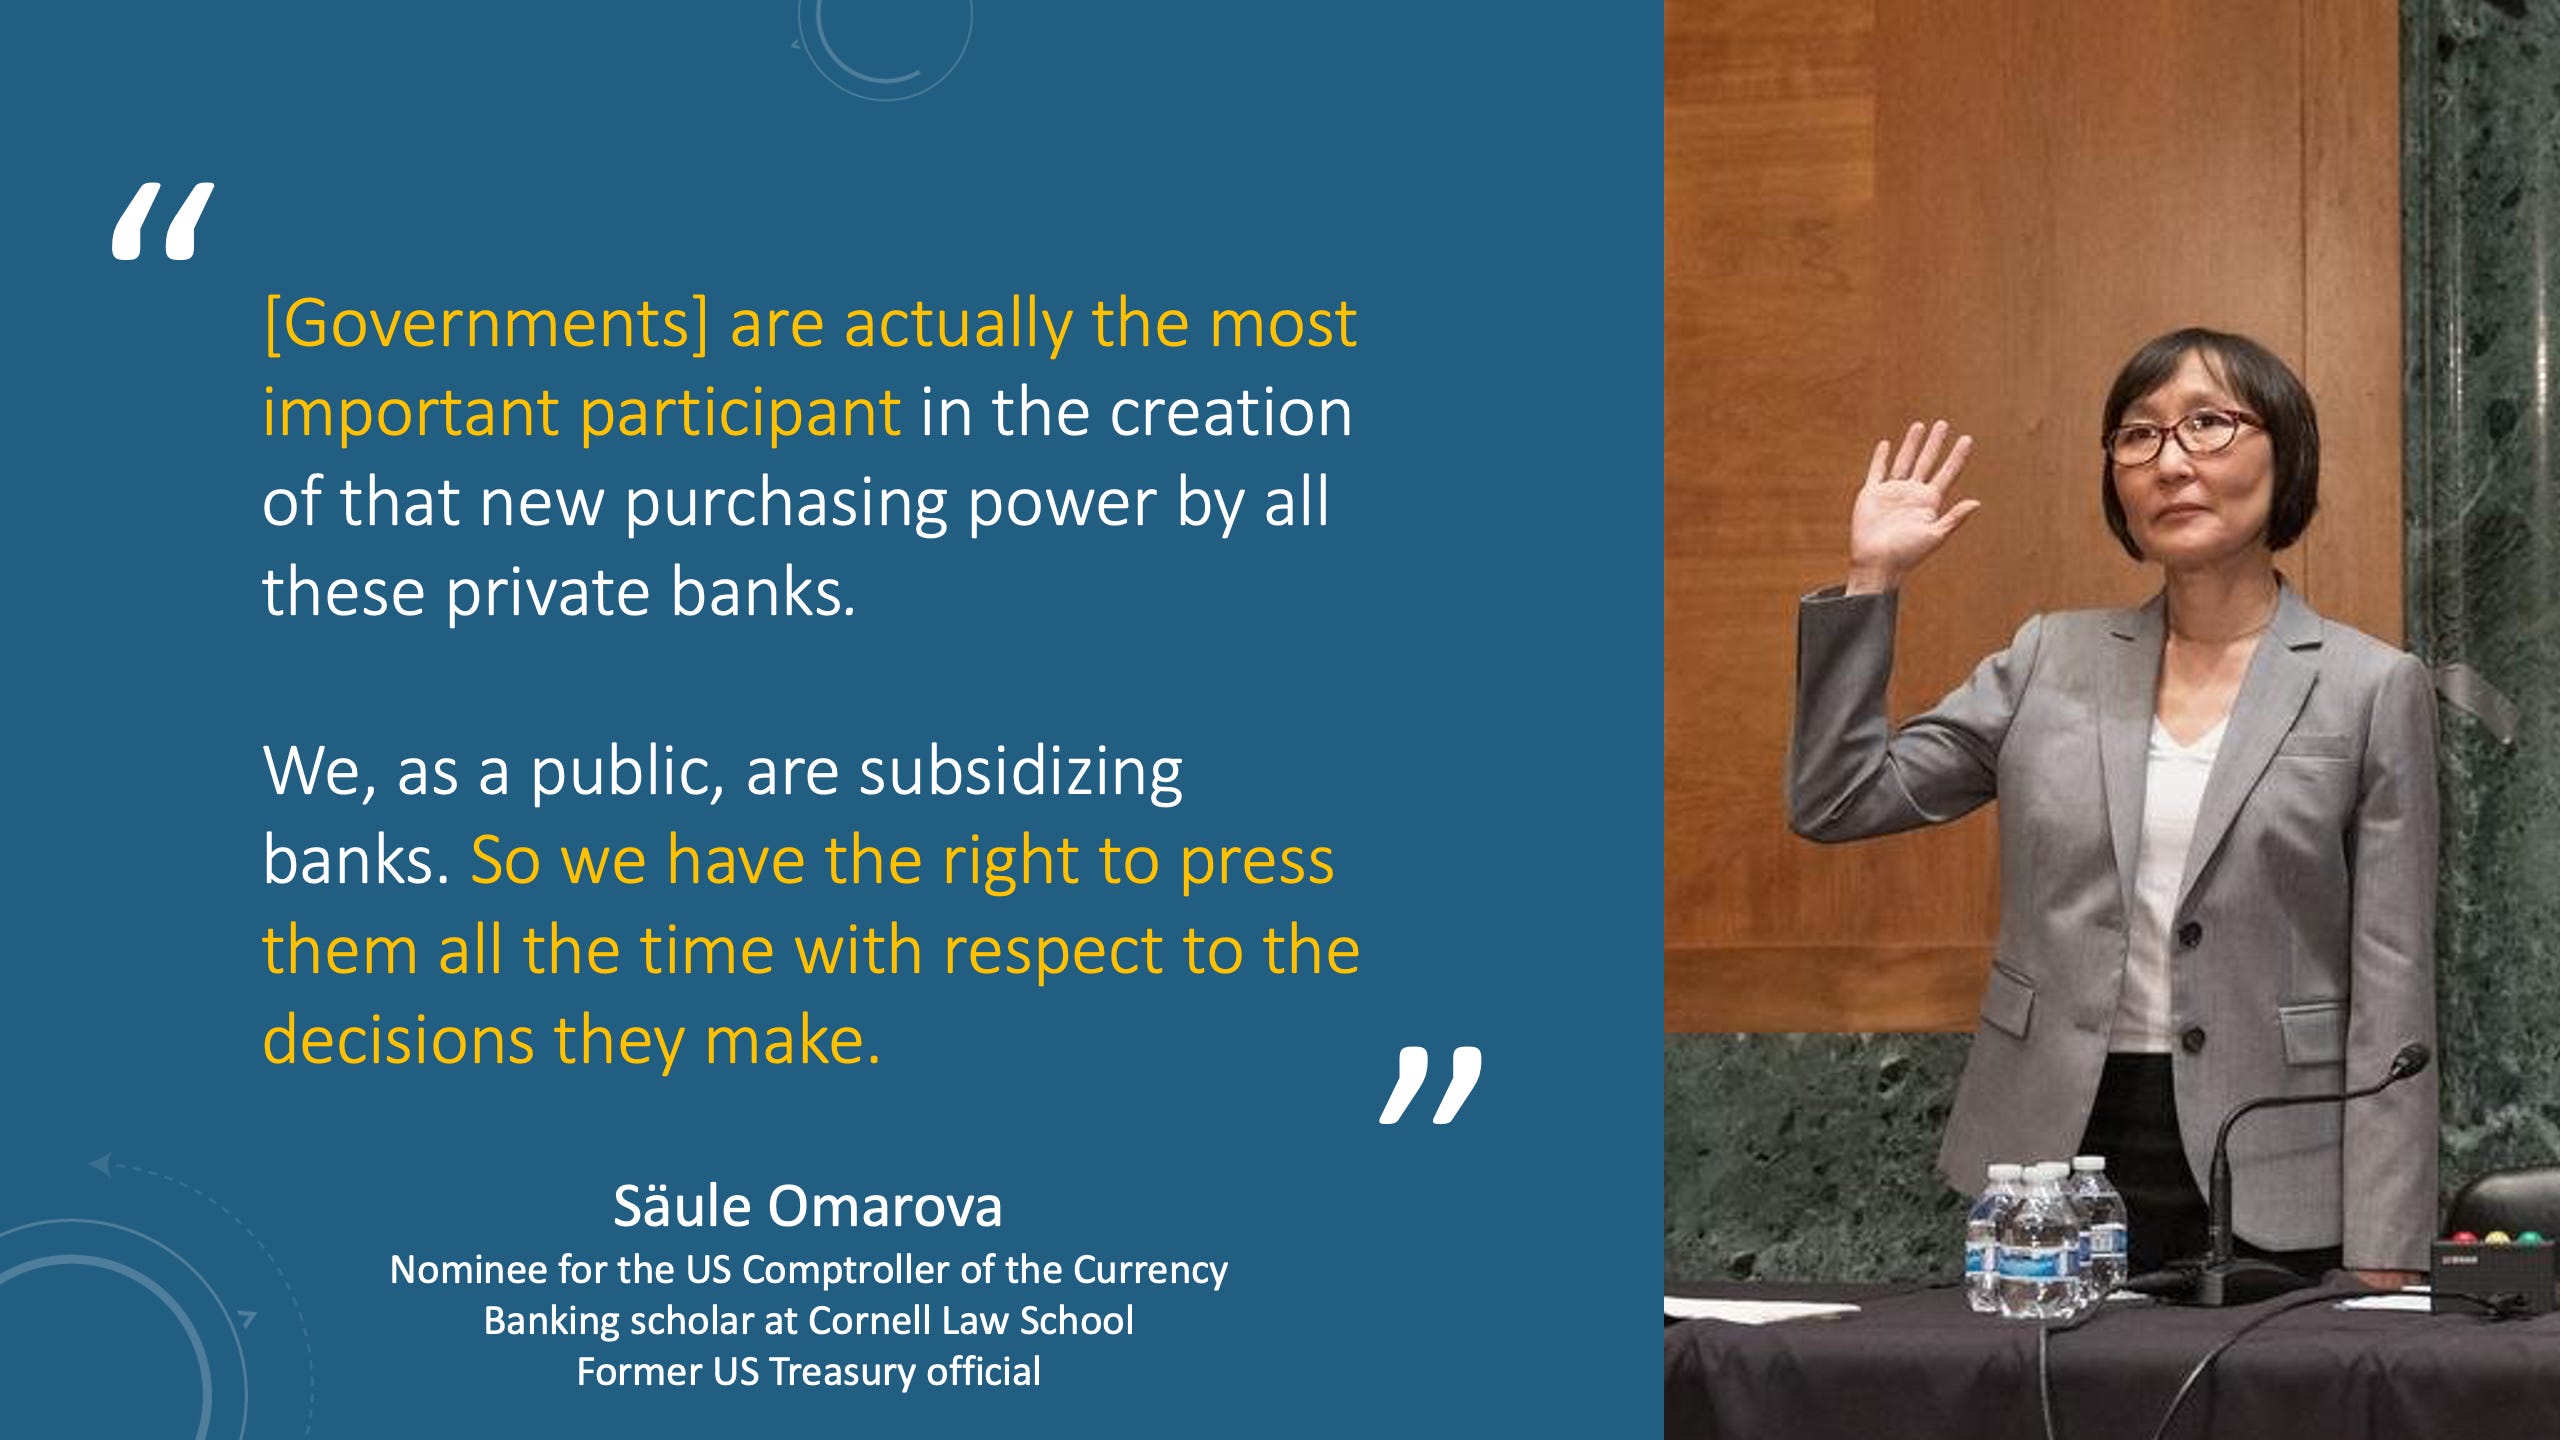
Saule Omarova is another banking legal scholar, also a former nominee for the US Comptroller of the Currency and a former US Treasury official. She says, “Governments are actually the most important participant in the creation of that new purchasing power by all these private banks. We as a public are subsidizing banks, so we have the right to press them all the time with respect to the decisions that they make.” So again, what’s valuable here about understanding the law and understanding that it’s constantly being contested, is that if we have concerns, and you get to decide for yourself, if you do have concerns about the current way the money system operates, that you have the right to demand that it be changed.
Okay, so that’s my segue into the politics aspect of our talk today, because there’s the law of what the law says and the institutions that it creates, and what’s happening as a result of that, and then there’s the process of how we got to this law and what’s keeping it in place.
Annotated Bibliography
These are organized approximately in the order of their approachability and the sequence of information in the video’s narrative.
Hockett, Robert C., and Saule T. Omarova. 2017. “The Finance Franchise.” Cornell Law Review 102 (5): 1143–1218. https://dx.doi.org/10.2139/ssrn.2820176
This paper illuminates bank money creation through the lens of law, arguing that governments have outsourced the creation of their money supplies to banks. They compare the government to franchisor (the creator of the legal money creation power) that has outsourced the money creation power to banks by giving them franchise rights to exercise the money creation power.
Ricks, Morgan. 2016. The Money Problem: Rethinking Financial Regulation. Chicago: University of Chicago Press. https://press.uchicago.edu/ucp/books/book/chicago/M/bo22438821.html.
This book illuminates bank money creation through the lens of law.
Ricks, Morgan. 2023. “Banks as Public Utilities.” Money as a Democratic Medium 2.0 Conference: Boston, Massachusetts.
This is one of several talks in which I’ve seen Morgan Ricks walk the audience through United States Code 12 U.S.C. § 378(a)(2) as a way of demonstrating the difficulty of identifying the legal accommodations that enable banks to serve as the creators of a nation’s money supply.
Tankus, Nathan. 2020. “Why Are Banks Special? Monetary Policy 101.” Notes on the Crises. May 25, 2020. https://nathantankus.substack.com/p/why-are-banks-special-monetary-policy
This article by the director of the Modern Money Network provides a concise overview of bank licensing and the accommodation of governments in accepting bank notes (and deposits) as payment for taxes.
Desan, Christine. 2014. Making Money: Coin, Currency, and the Coming of Capitalism. Oxford: Oxford University Press.
A scholar at Harvard Law School, Christine Desan provides a majestrial account of the formation of the Bank of England as the first commercial bank to receive the basic set of legal accommodations that turn bank deposits and bank notes into a nation’s money supply.
Zarlenga, Stephen A. 2002. The Lost Science of Money: The Mythology of Money, the Story of Power. Valatie, NY: American Monetary Institute.
Zarlenga recounts the colonial American and United States history of money creation, including the creation of debt-free money by states, the prohibition of state money creation by the US Constitution, the federal governments’ abdication from creating money to fund spending, and its adoption of commercial bank deposits and bills as the payment media it would use for government business, and the issuance of Greenbacks to fund spending during the Civil War.
Peer, Nadav Orian. “Money Creation and Bank Clearing.” Fordham J. Corp. & Fin. L. 28 (2023): 35.
This article by University of Colorado Law School professor, Nadav Orian Peer, recounts the legal history of interbank payment settlement in the United States and the government accommodations and payment services provided to banks.
Menand, Lev. “Why Supervise Banks? The Foundations of the American Monetary Settlement.” Vand. L. Rev. 74 (2021): 951.
This article by Columbia Law School scholar, Lev Menand, recounts pivotal regulatory battles over the legal accommodations surrounding bank money creation in the US since the 1950s.
Menand, Lev, and Morgan Ricks. “Rebuilding Banking Law: Banks as Public Utilities.” Yale J. on Reg. 41 (2024): 591.
This article by legal scholars Menand and Ricks provides another account of the last 100 years of government accommodation of the bank money creation privileges. This piece brings the story up to the present, arguing that banks should be re-regulated as public utilities. The piece reflects ongoing fight over the government accommodations that enable banks to create a nation’s money supply.
BRIEF OF THIRTY-THREE BANKING LAW SCHOLARS AS AMICI CURIAE IN SUPPORT OF APPELLEE - Case 19-4271, Document 50, 07/29/2020, 2895689
This brief was submitted as part of a US federal court case involving the regulation of financial technology services. In it, the legal scholars point out that what makes banks special among all other financial institutions is that they are legally privileged to create money. This case represents just one contemporary instance in which banks’ legal money creation privileges are being contested.
Bank Policy Institute. 2025. “Blog.” Bank Policy Institute. Accessed October 13, 2025. https://bpi.com/blog/
For a catalog of contemporary fights over the legal accommodations that enable bank money creation, see the blog and newsletters of the Bank Policy Institute, the industry lobby for the biggest US banks.
NPR. 2023. “How the Debt Ceiling Fight Could Affect the Economy.” Transcript, June 1, 2023. NPR. https://www.npr.org/transcripts/1063767973
This is the source for the Saule Omarova quote.
Hummel, Sam. 2024. “Who Owns and Controls Your Country’s Central Bank? It May Not Be Who You Think.” Sam Thinks Out Loud. November 23, 2024.

A few years ago, I compiled a dataset on the founding and ownership structures of the world’s central banks. I was inspired to create the dataset after reading a paper written by a former central banker in South Africa. He said that no such dataset existed and that the data gap was undermining a correct institutional/political understanding of the central banking sector. In the linked article, I shared the dataset and summarize some of my key take-aways.
United States Mint. 2024. “How Coins Are Made: Bringing Coins Into Circulation.” Inside the Mint. July 2, 2024. https://www.usmint.gov/news/inside-the-mint/how-coins-are-made-bringing-coins-into-circulation
This article on the website of the United States Mint explains that coins are minted by the Mint in response to orders for coins placed by depository institutions (banks). Coins do not enter circulation as spending by the government.
Federal Reserve Bank of San Francisco. 2025. “Infographic on the Cash Lifecycle.” Last modified 2025. https://www.frbsf.org/cash-lifecycle-infographic/
This article and infographic shows how coins from the Mint and bills from the US Bureau of Engraving and Printing are put into circulation by the Federal Reserve in response to orders from banks, not as spending by the government.
Perry Mehrling. 2020–. “Economics of Money and Banking (Mehrling) — Full Course.” Institute for New Economic Thinking. YouTube playlist. Accessed October 2025. https://www.youtube.com/playlist?list=PLbjqQEPFY1J8ShzMPiaULMDCIuFmaBs0Y.
This course taught through Columbia University by highly regarded banking historian and economist Perry Mehrling, provides instruction on bank and central bank accounting, including how coins and bills enter circulation as physical substitutes for bank deposit accounting entries.
Lowenstein, Roger. America’s Bank: The Epic Struggle to Create the Federal Reserve. Penguin, 2016.
Lowenstein’s historical account of the Federal Reserve Act’s passage provides a number of insights into the influence of bankers in the crafting of the Act. Lowenstein does not see their influence as particularly problematic. In general, his account is biased, marginalizing and deriding nearly everyone offering a more democratic and publicly-owned alternative to the 12 private for-profit regional banks ultimately established by the Federal Reserve Act.