

Over the last few years, I’ve been producing Money as a Force for Good workshops (online and offline) with the Money Justice Collaborative. We are a nonprofit project that teaches social movement activists how national currencies can be transformed into a powerful force for addressing many of the crises our societies face today. Our workshops are designed so that anyone can understand the issue without needing prior expertise in economics or finance. In this post, I’ll share how we do that. We’ve learned a lot about how to avoid a few of the biggest barriers that block people and organizations from joining together to advocate for national currencies that support economic, social, and ecological sustainability.
If you want to experience some of the Money as a Force for Good workshop yourself, here is a recording of the opening exercise that is discussed in this post. The recording is edited so that anyone can use it to facilitate a workshop of their own. Just pause the video when the question prompts come up.
We first let people discover experientially that they do understand money creation and that they do have preferences about how it works. They don’t have to rely on “experts.”
One thing we’ve learned in developing the Money as a Force for Good workshop is that its important to help people reorient their understanding of where money comes from, using their own experience as a guide. That’s important because what most people believe about where money comes from differs dramatically from the truth that governments create less than 5% of the money their country’s use and that banks create the rest when making loans. To make this reorientation an empowering experience, we first guide workshop participants through a fun experience in which they discover that they do understand money creation and that they do have valid preferences about how it works.
We do this by playing a game that we like to call, “You be the judge!” In the game, we ask workshop participants to imagine that one night all the money in their entire country vanishes. They must now decide how they will create new money to replace what vanished. We give them five options for creating all new money for their nation. The five options represent some of the ways of creating money that human societies have developed over thousands of years:
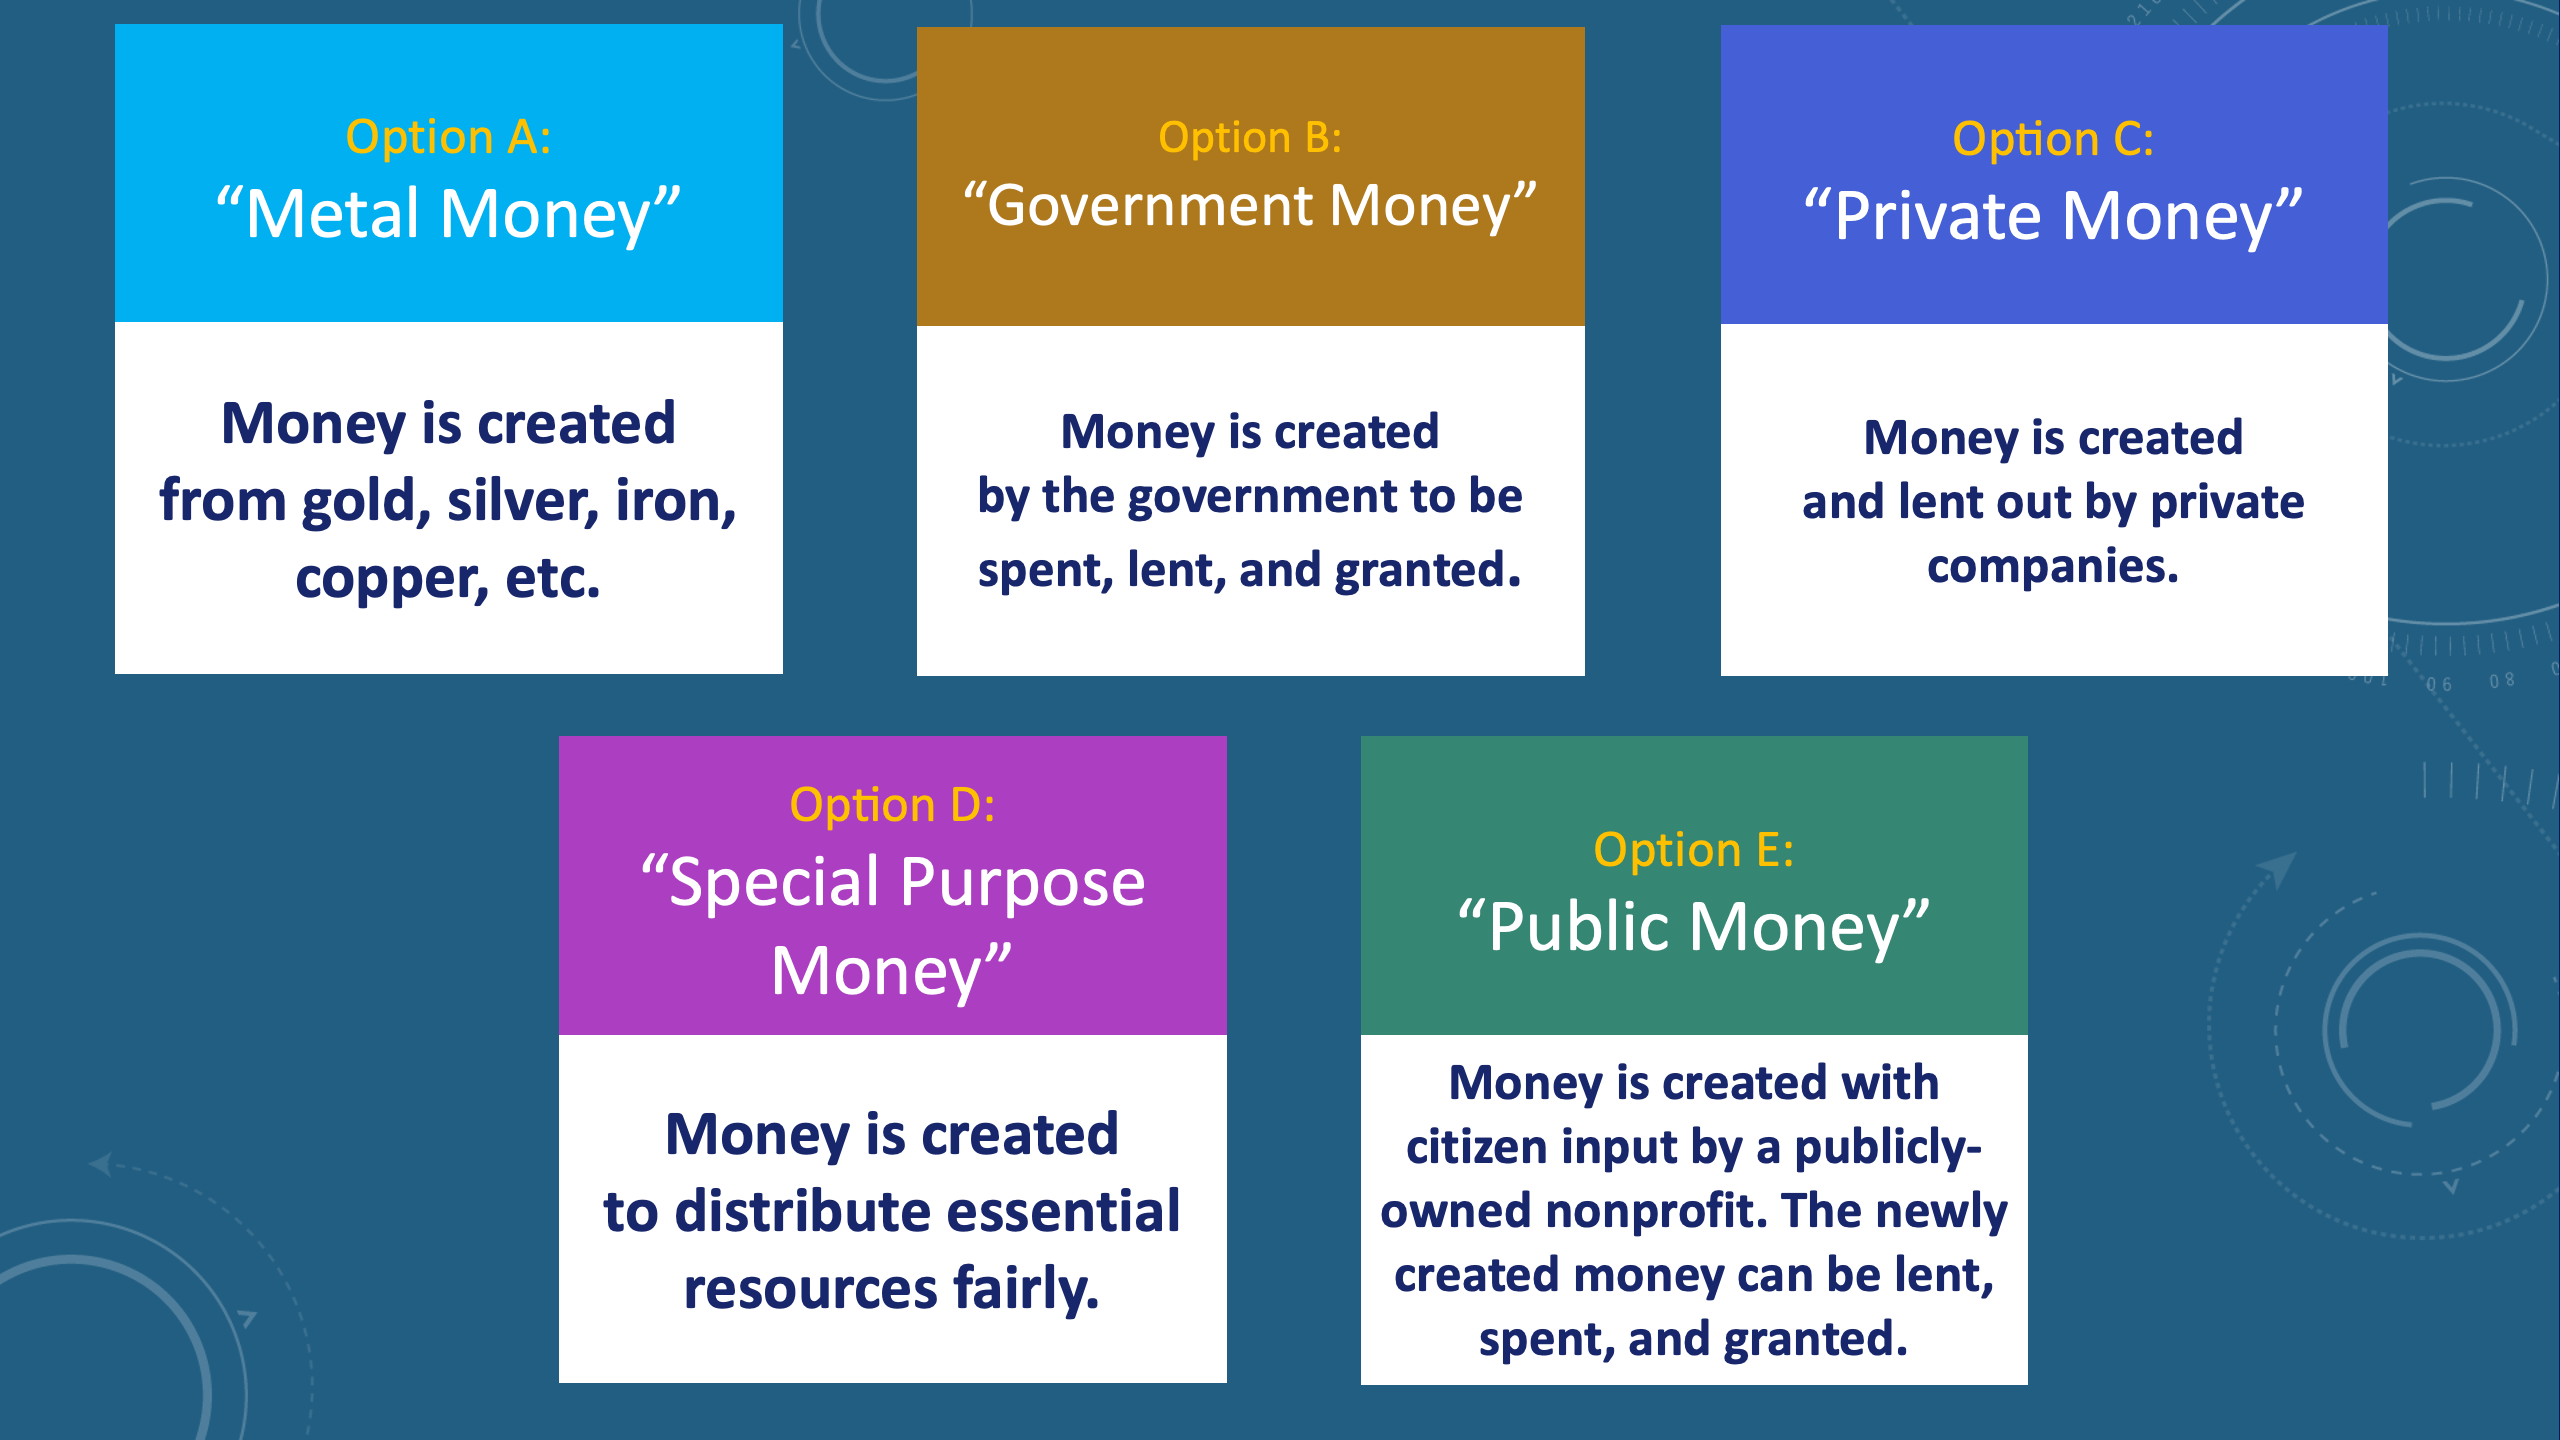
For each option, we tell them a story about how things would typically unfold if they chose that option. After each story, they get to judge how much they like that option, on a scale from 1 to 10, with 10 being “Awesome”. At the end, everyone in the group shows their scores to the whole group so they can see how each other graded the options. We invite the participants to share the questions and concerns that came up for them as they imagined each of the stories. With nothing more than this little exercise, participants begin asking insightful questions, raising real concerns, and showing open-minded curiosity.
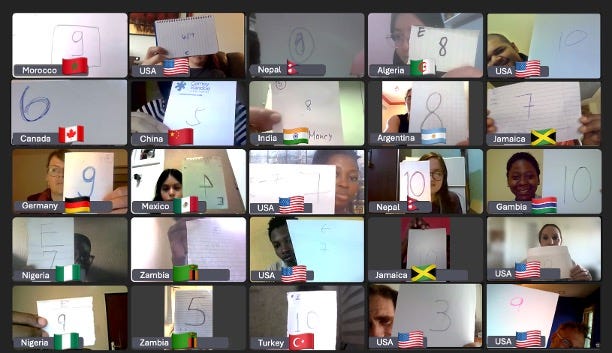
While they talk, we tabulate their scores for each option (high, low, average, and median). When we share their scores back with them, we point out that there isn’t universal agreement about which option would be the best. In fact, the highest and lowest score for each option is typically spread apart by 7 or 8 points.
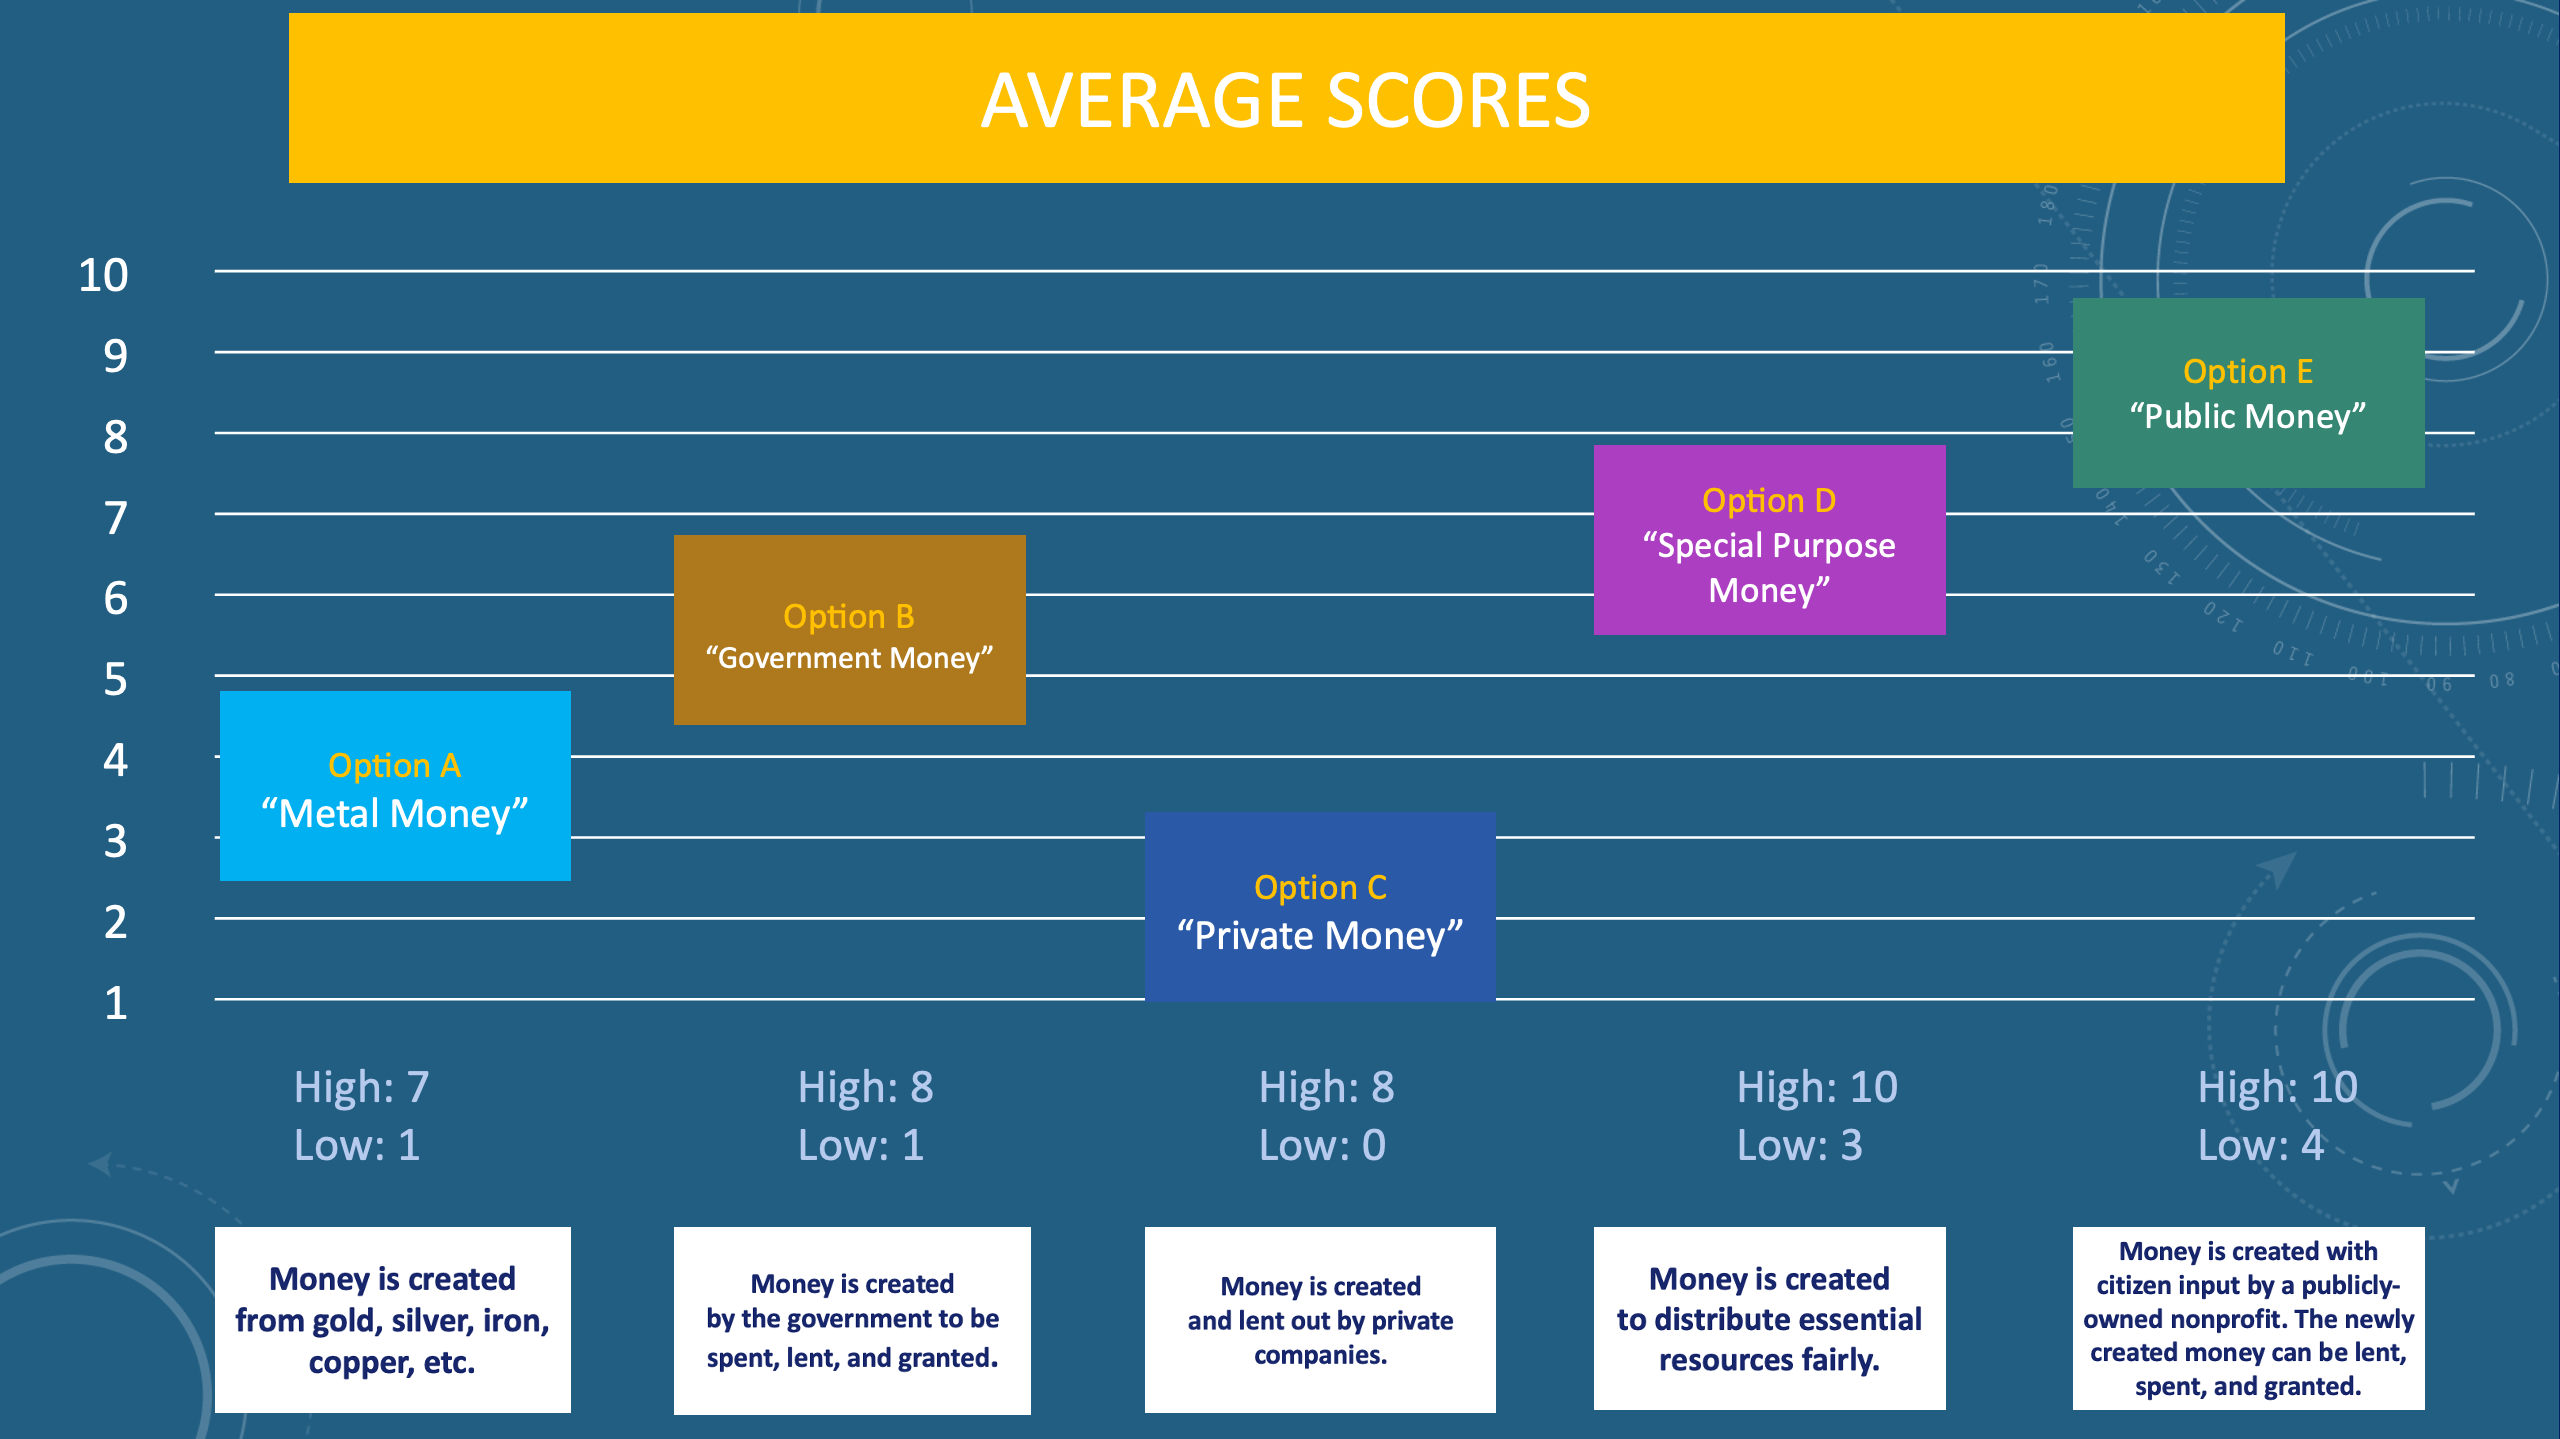
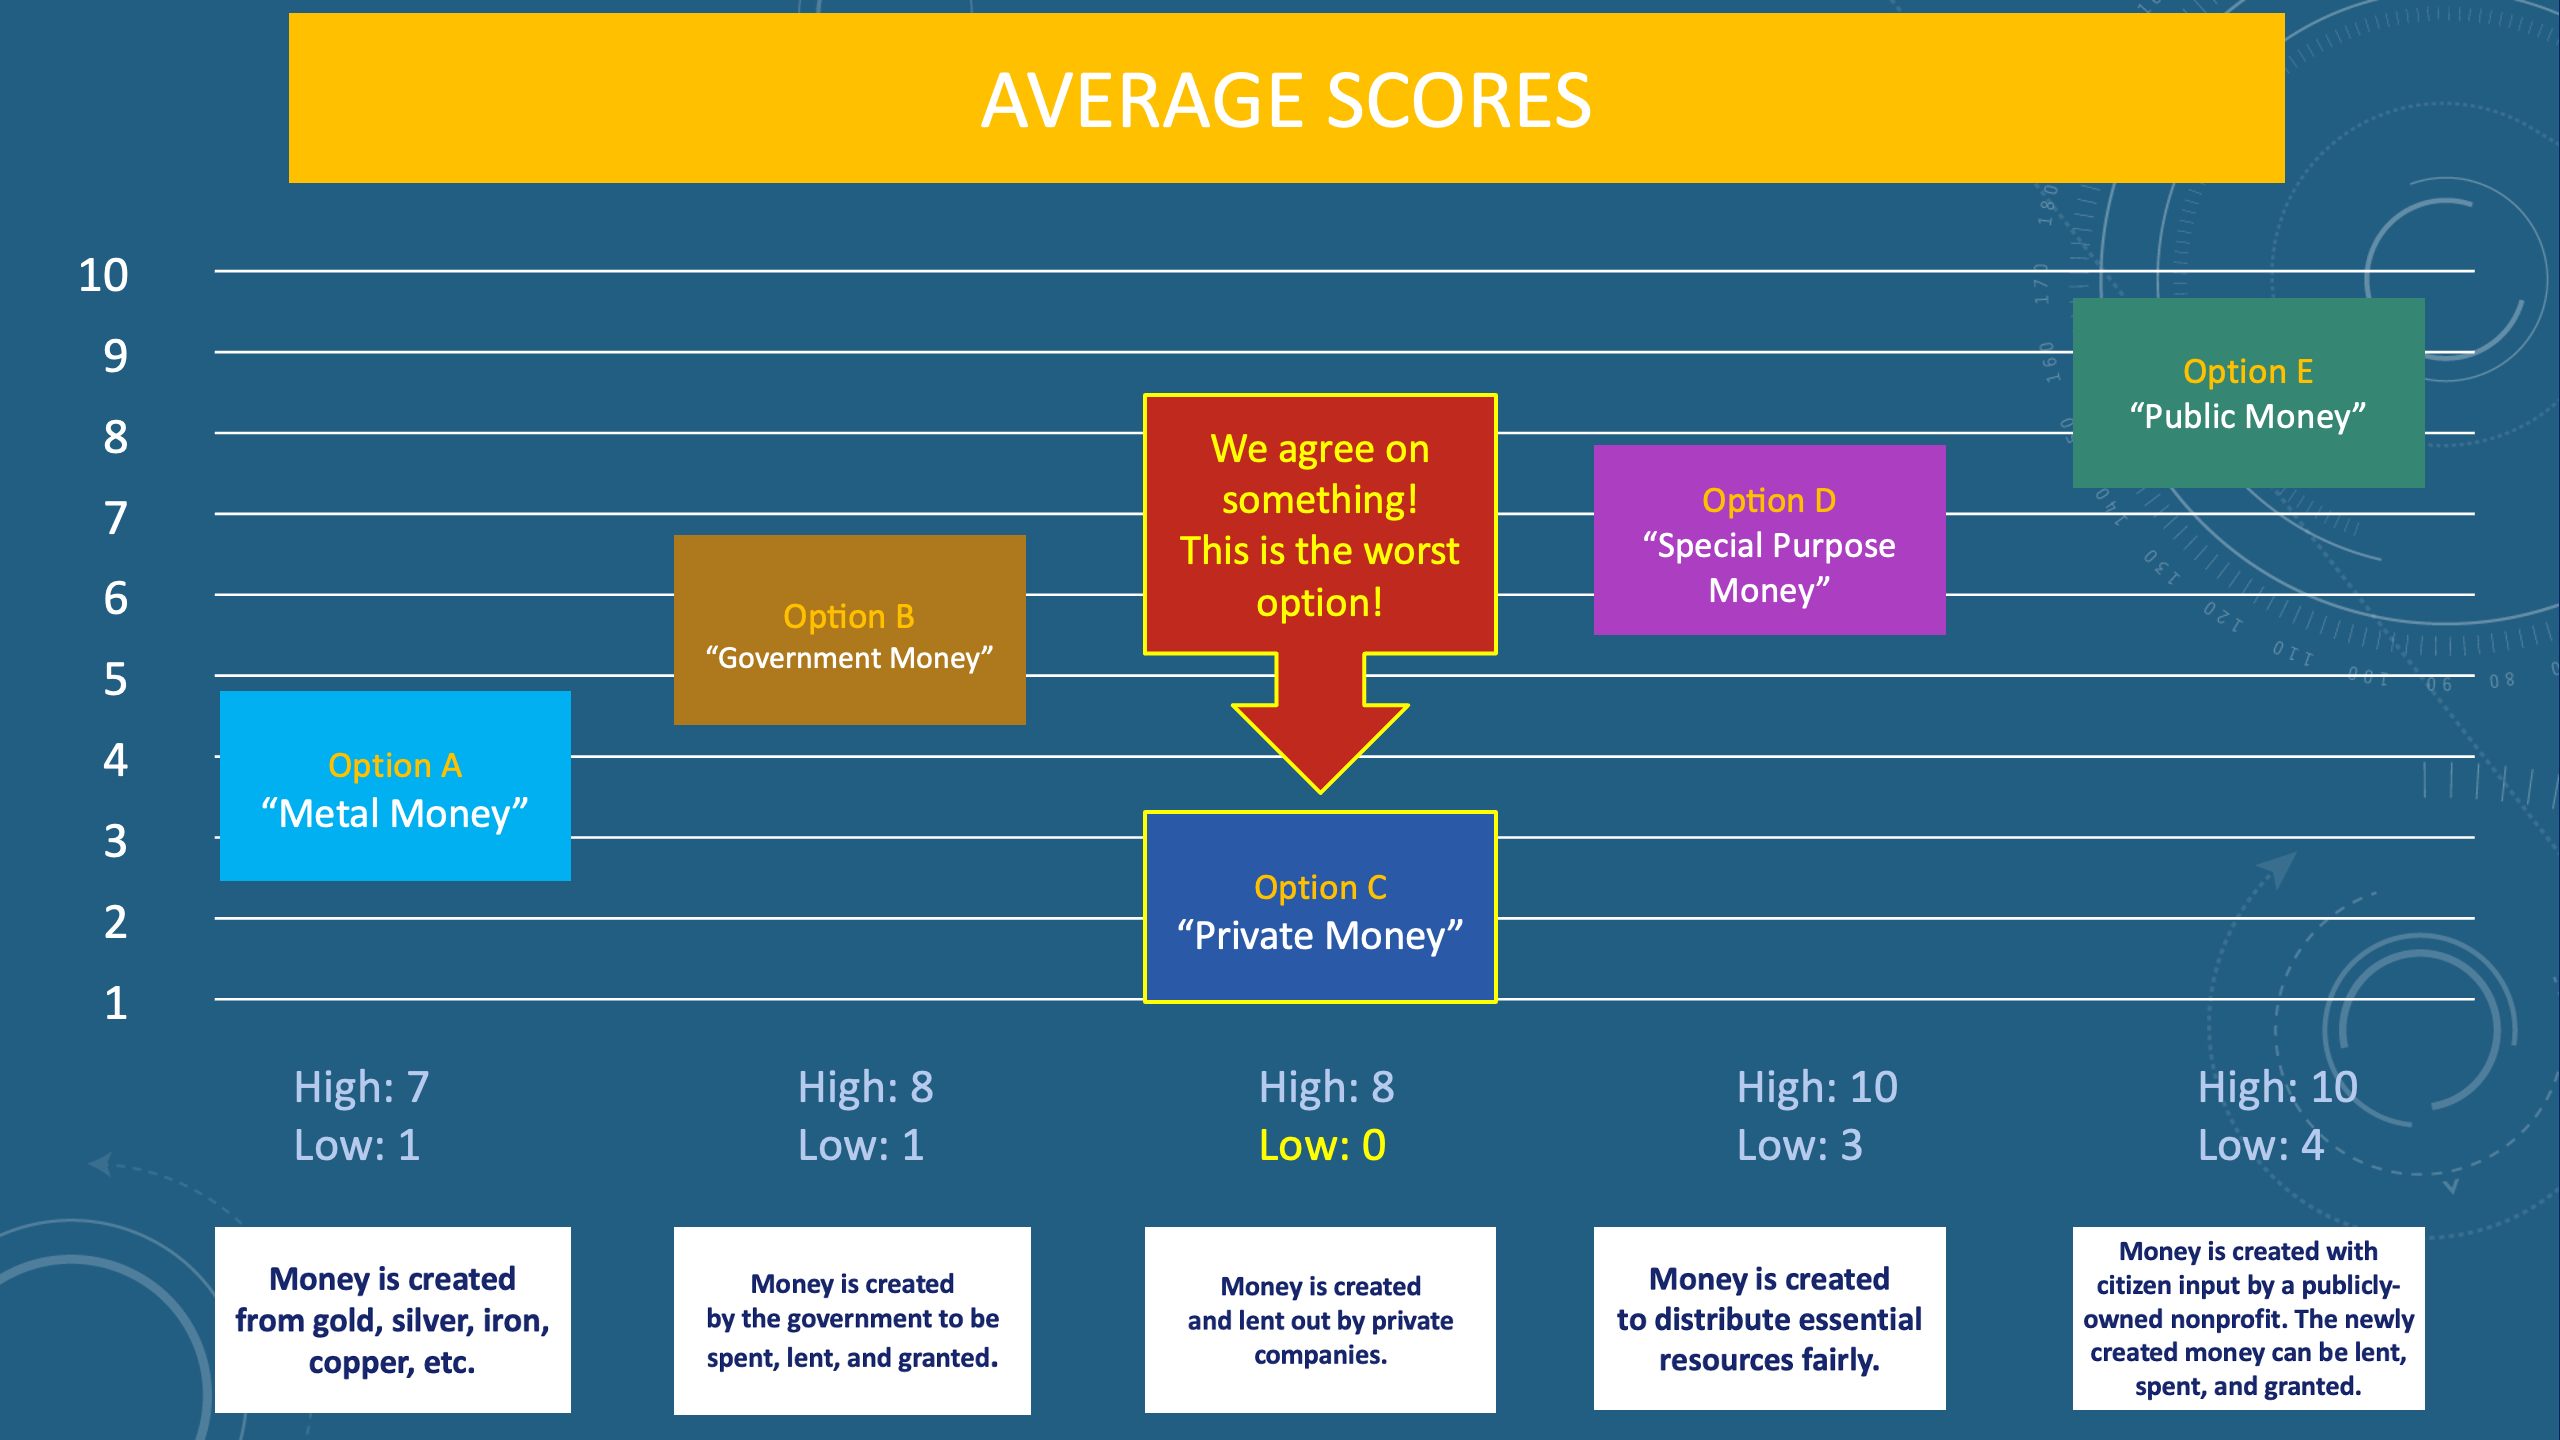
Then we bring their attention to a consistent outcome across all our workshops. There is near universal agreement on which option is the worst: Option C. In fact, in every workshop Option C breaks the grading scale because one or more people score it a zero instead of sticking to our grading scale of 1 to 10.
In option C, the national government delegates the power to create the nation’s money supply to privately-owned for-profit corporations. These corporations, better known as commercial banks (not central banks), use this government-granted power to create 100% of the money they lend. Option C describes how most nations create their money supplies, today. This surprises many participants and generates significant curiosity about how it works today, how we got here, and how the other options would work, by comparison.
The conversation inevitably reveals an important insight: all ways of creating money can be good or bad, better or worse, depending on how they are implemented. One way might be good when living in a democracy while it may be bad when living in an authoritarian state, for example. No one system is the best in all contexts. And the details of how any system is implemented matter.
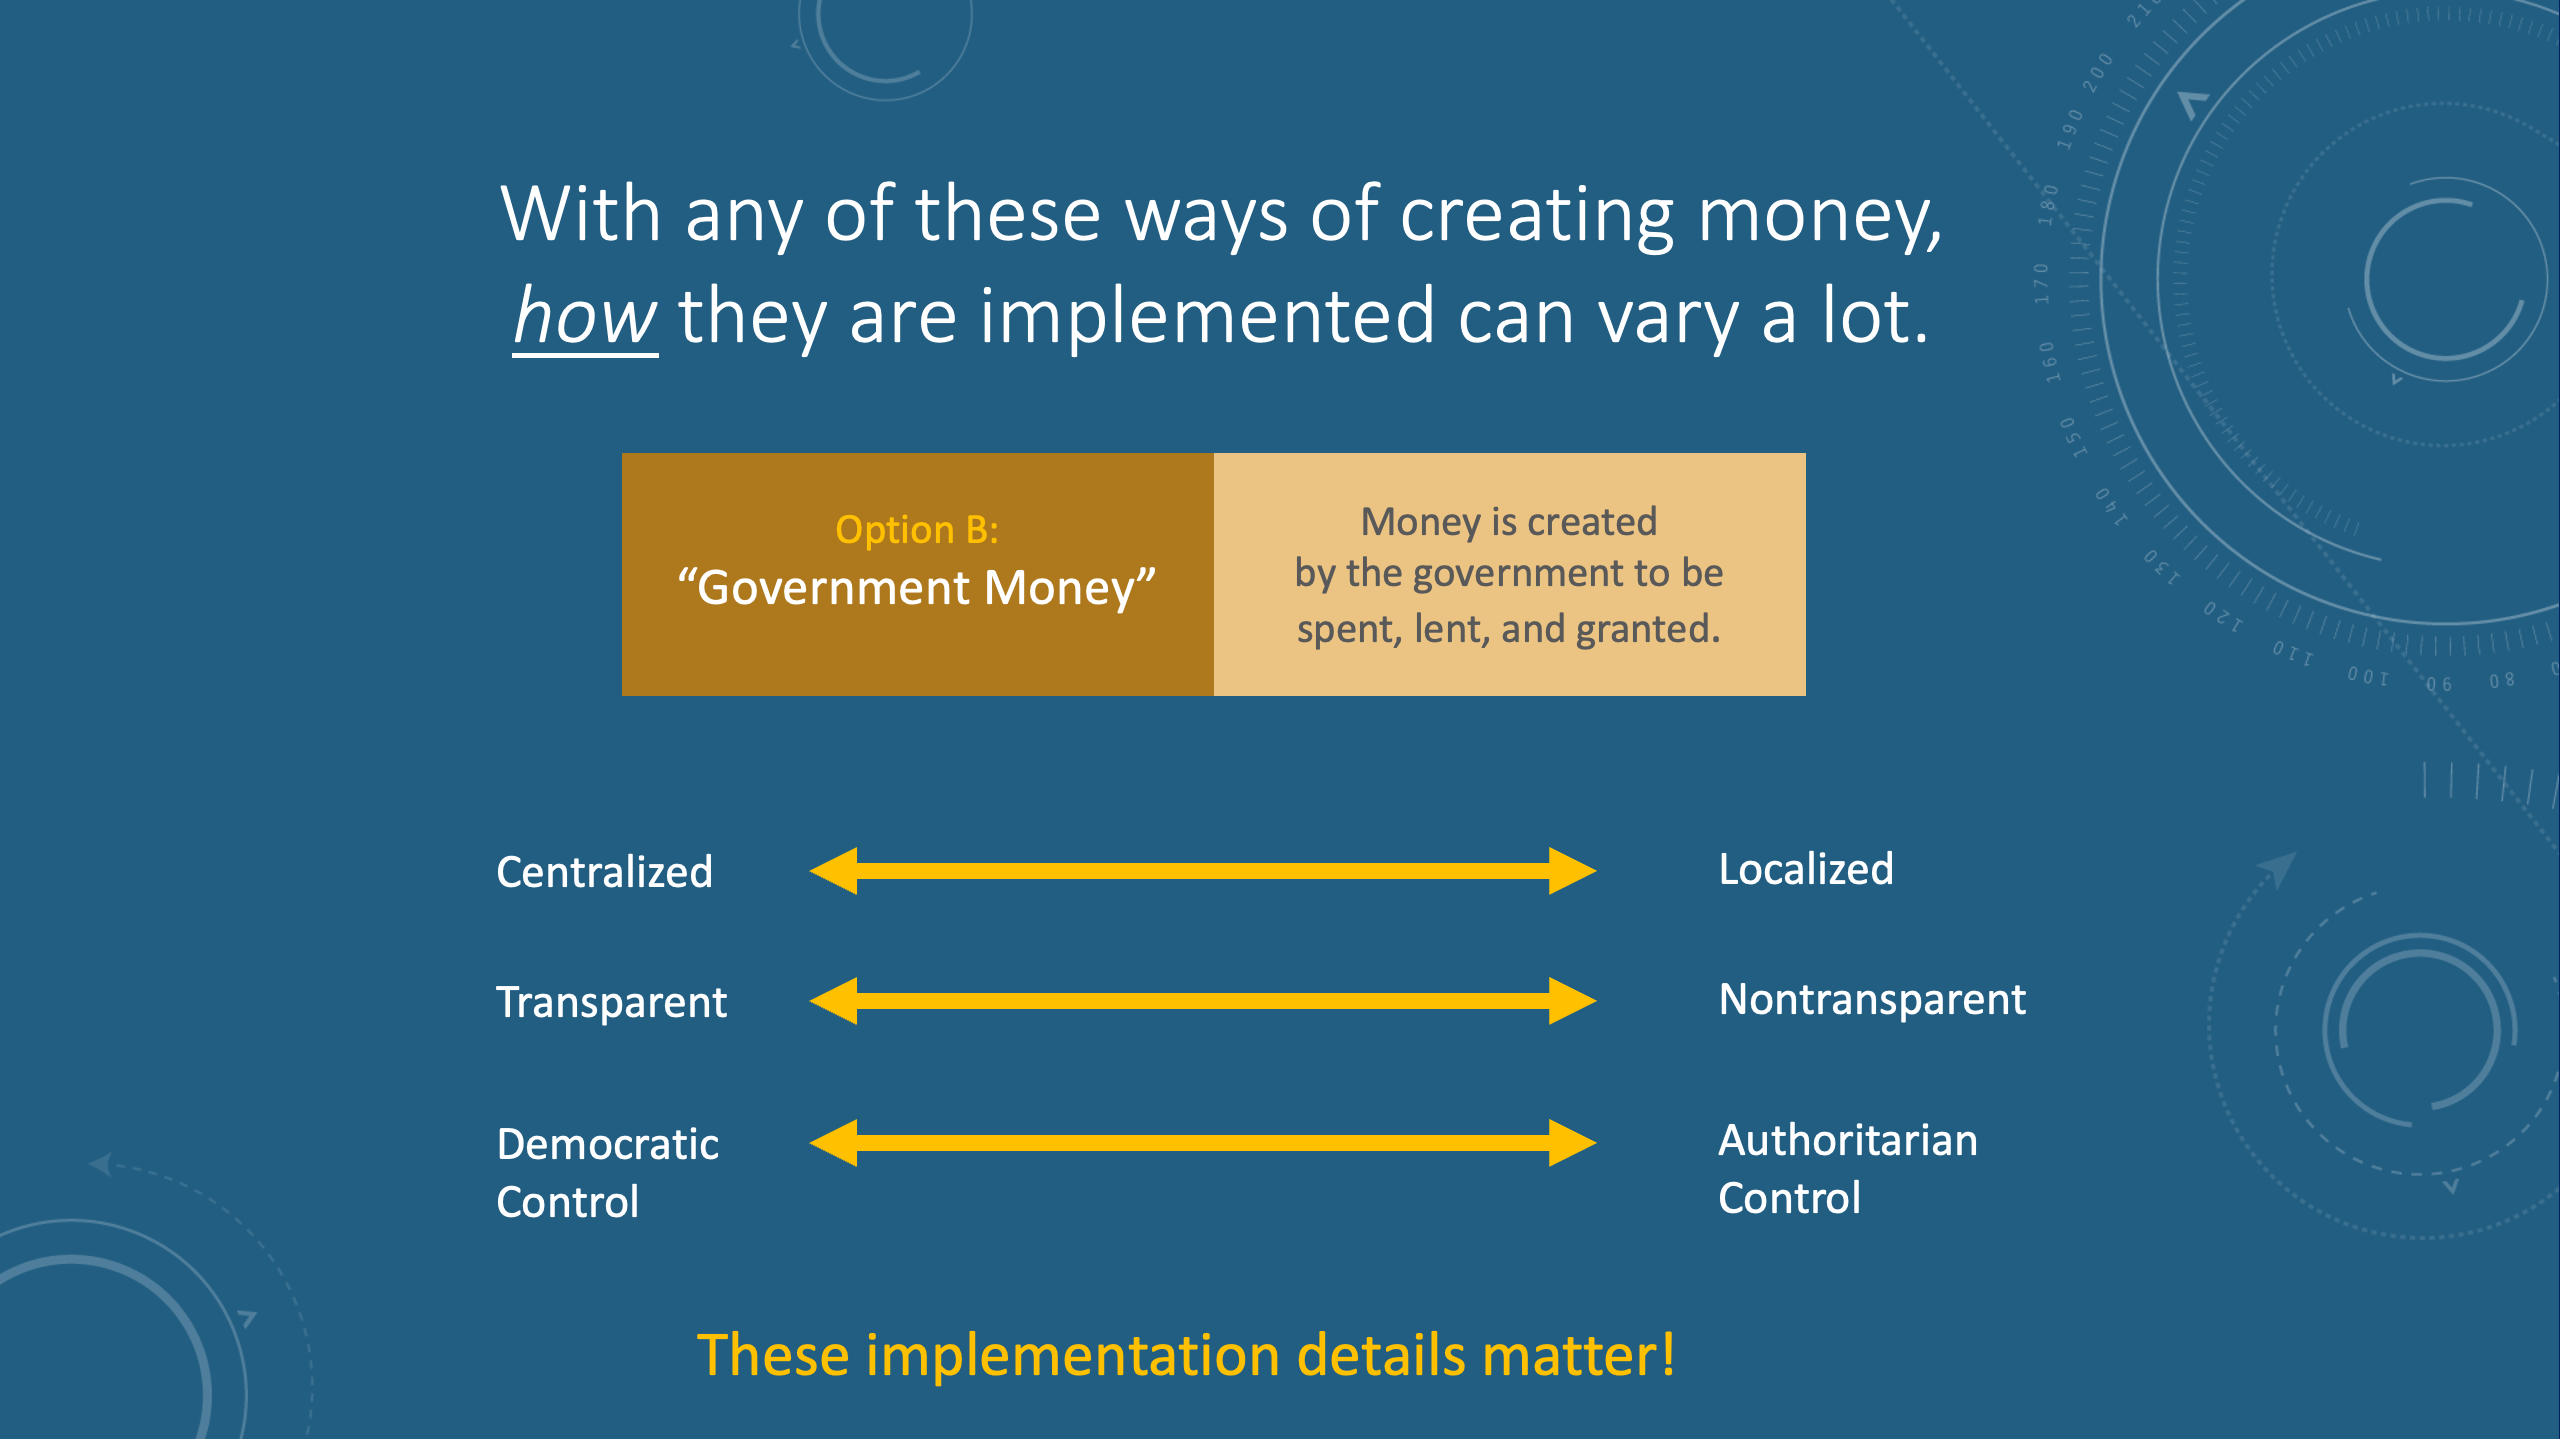
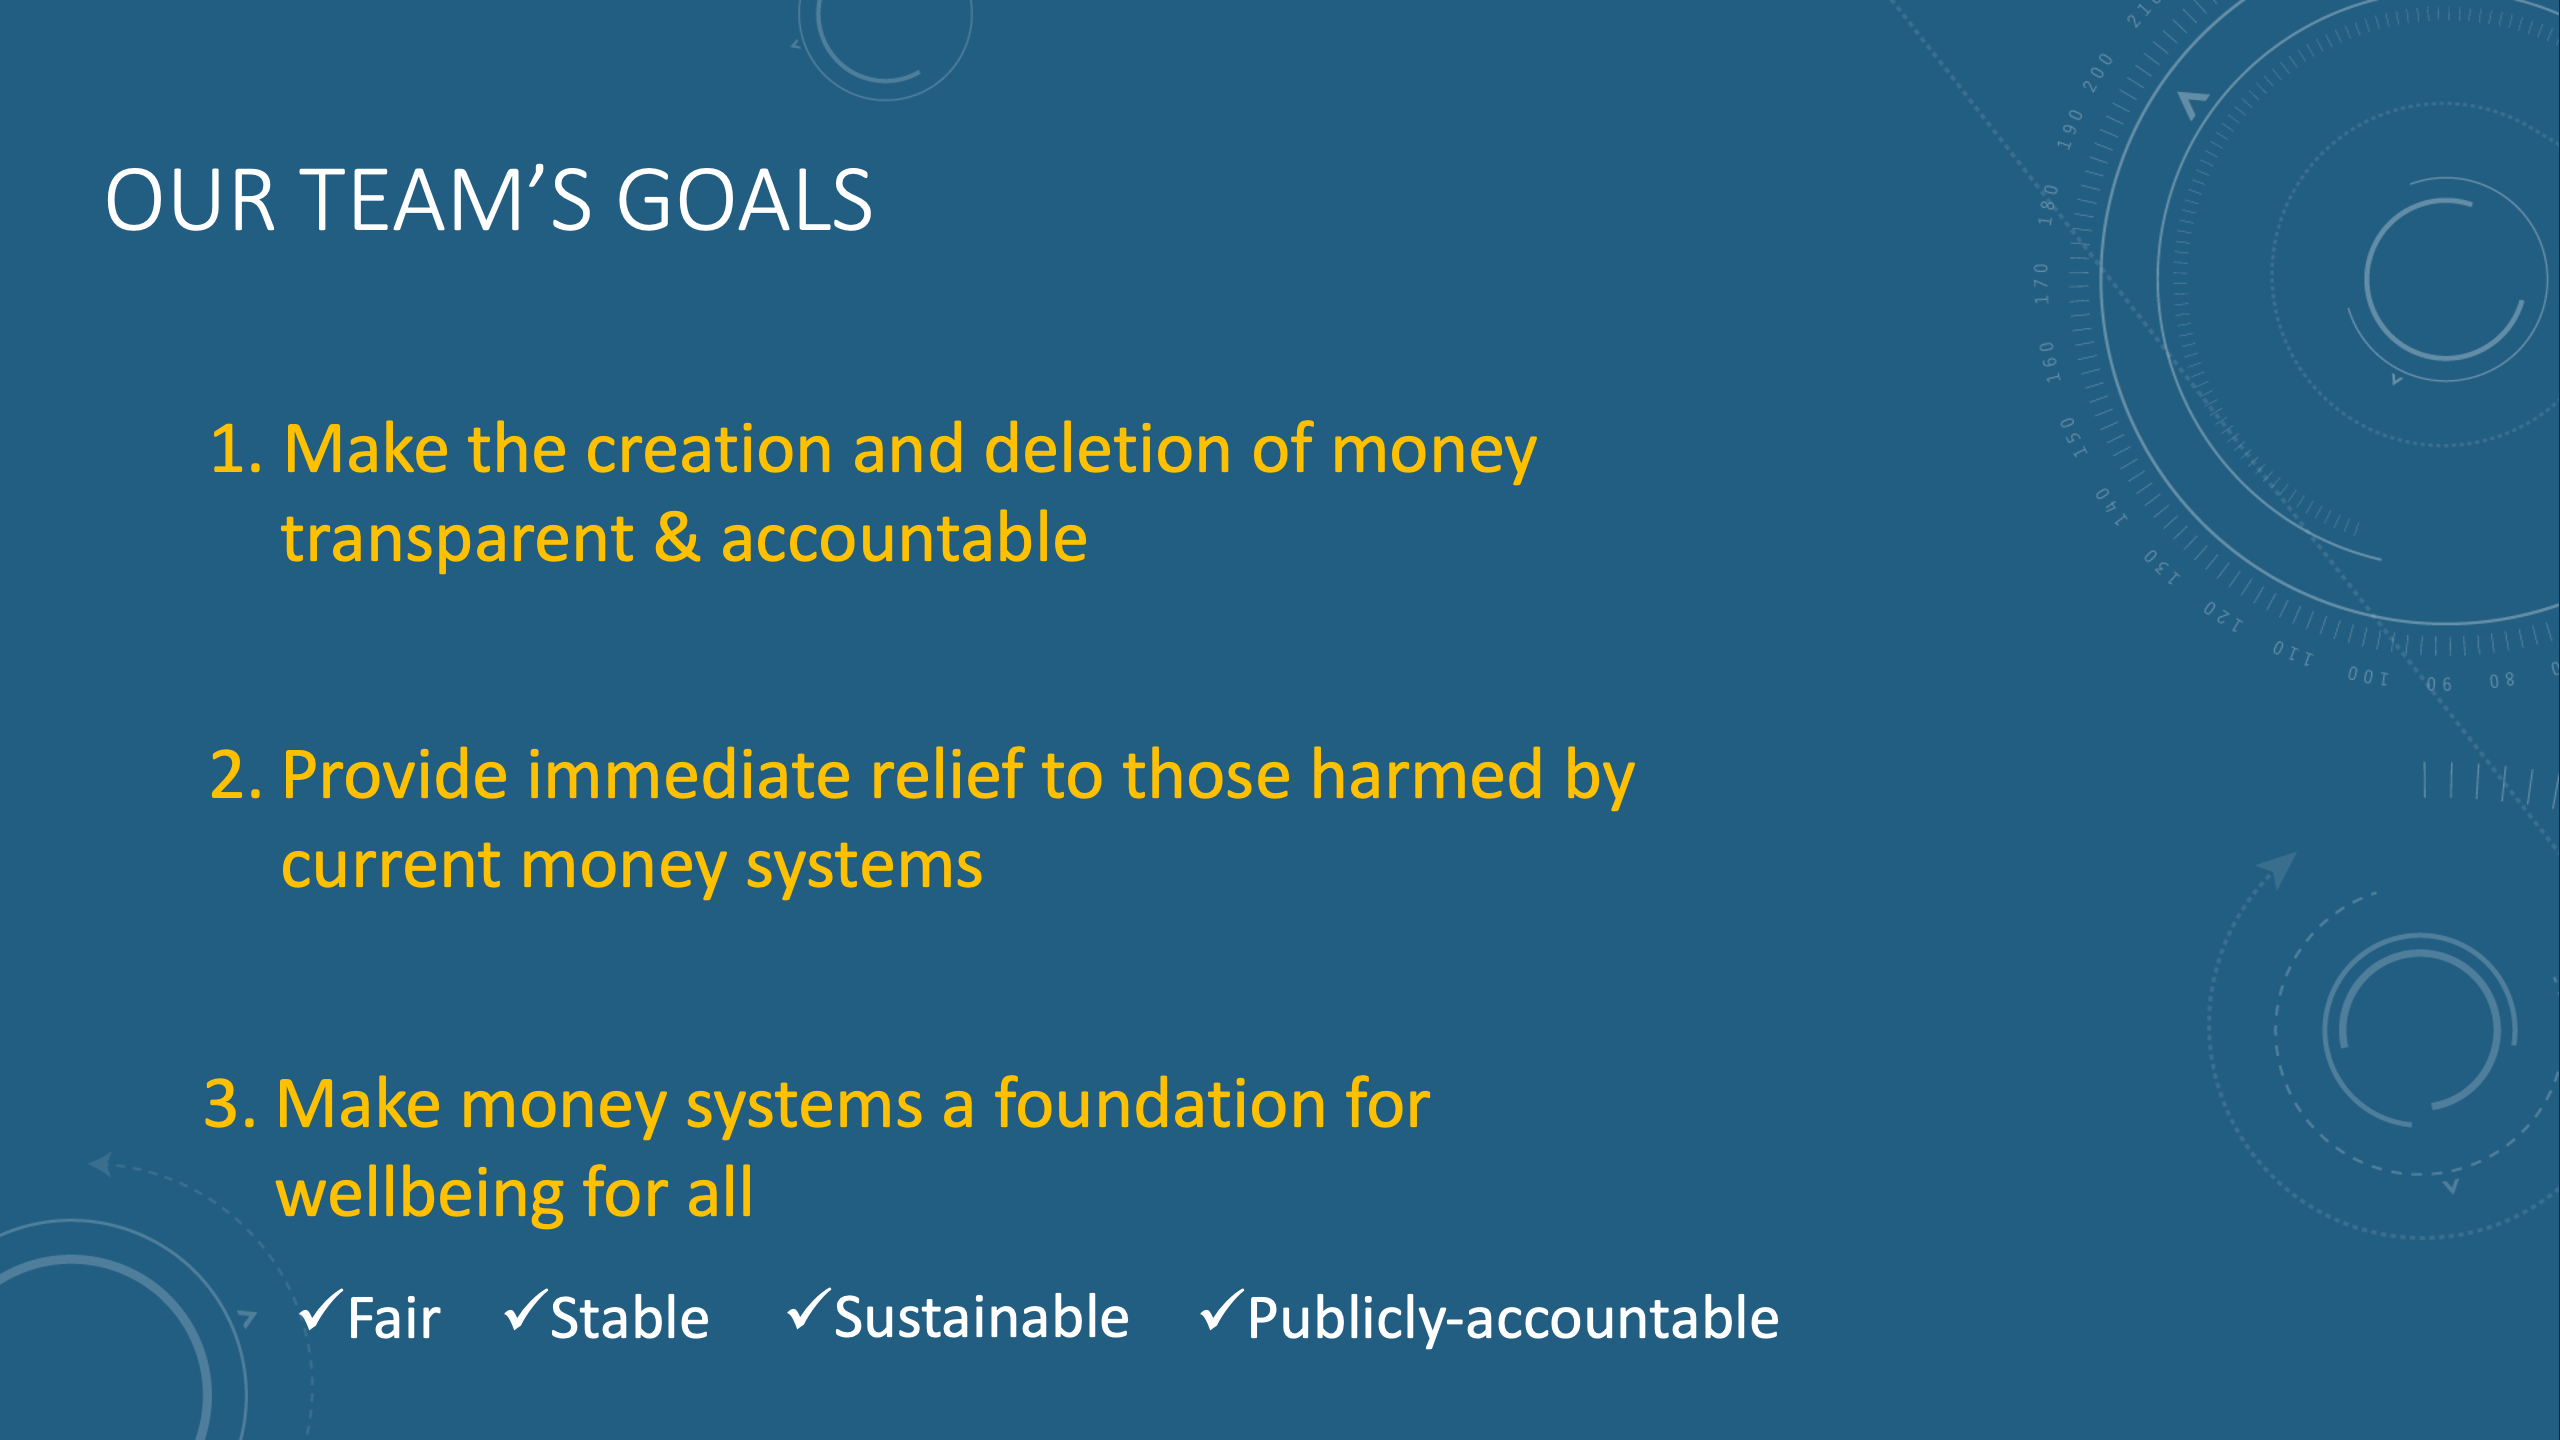
The recognition that the details of how money is created matters a lot highlights the need for transparency and public accountability in any money creation system. At this point, workshop participants are typically bought in on the first of the Money Justice Collaborative’s goals in advocating for the transformation of national money systems.
Make the creation and deletion of money transparent and accountable
Provide immediate relief for those harmed by current money systems (for example, debt relief)
Make money systems a foundation for wellbeing for all. Fair. Stable. Sustainable. Publicly-accountable.
But most importantly, by this point in the workshop participants have answers to many of the thoughts that were initially so disorienting, without us or anyone telling them what to think:
Throughout the exercise we emphasize that all opinions about how money creation works are valid and that even the members of our Money Justice Collaborative have different opinions about what would be best. This creates the psychological and social space for the participants to work out what they believe themselves and in dialogue with their peers.
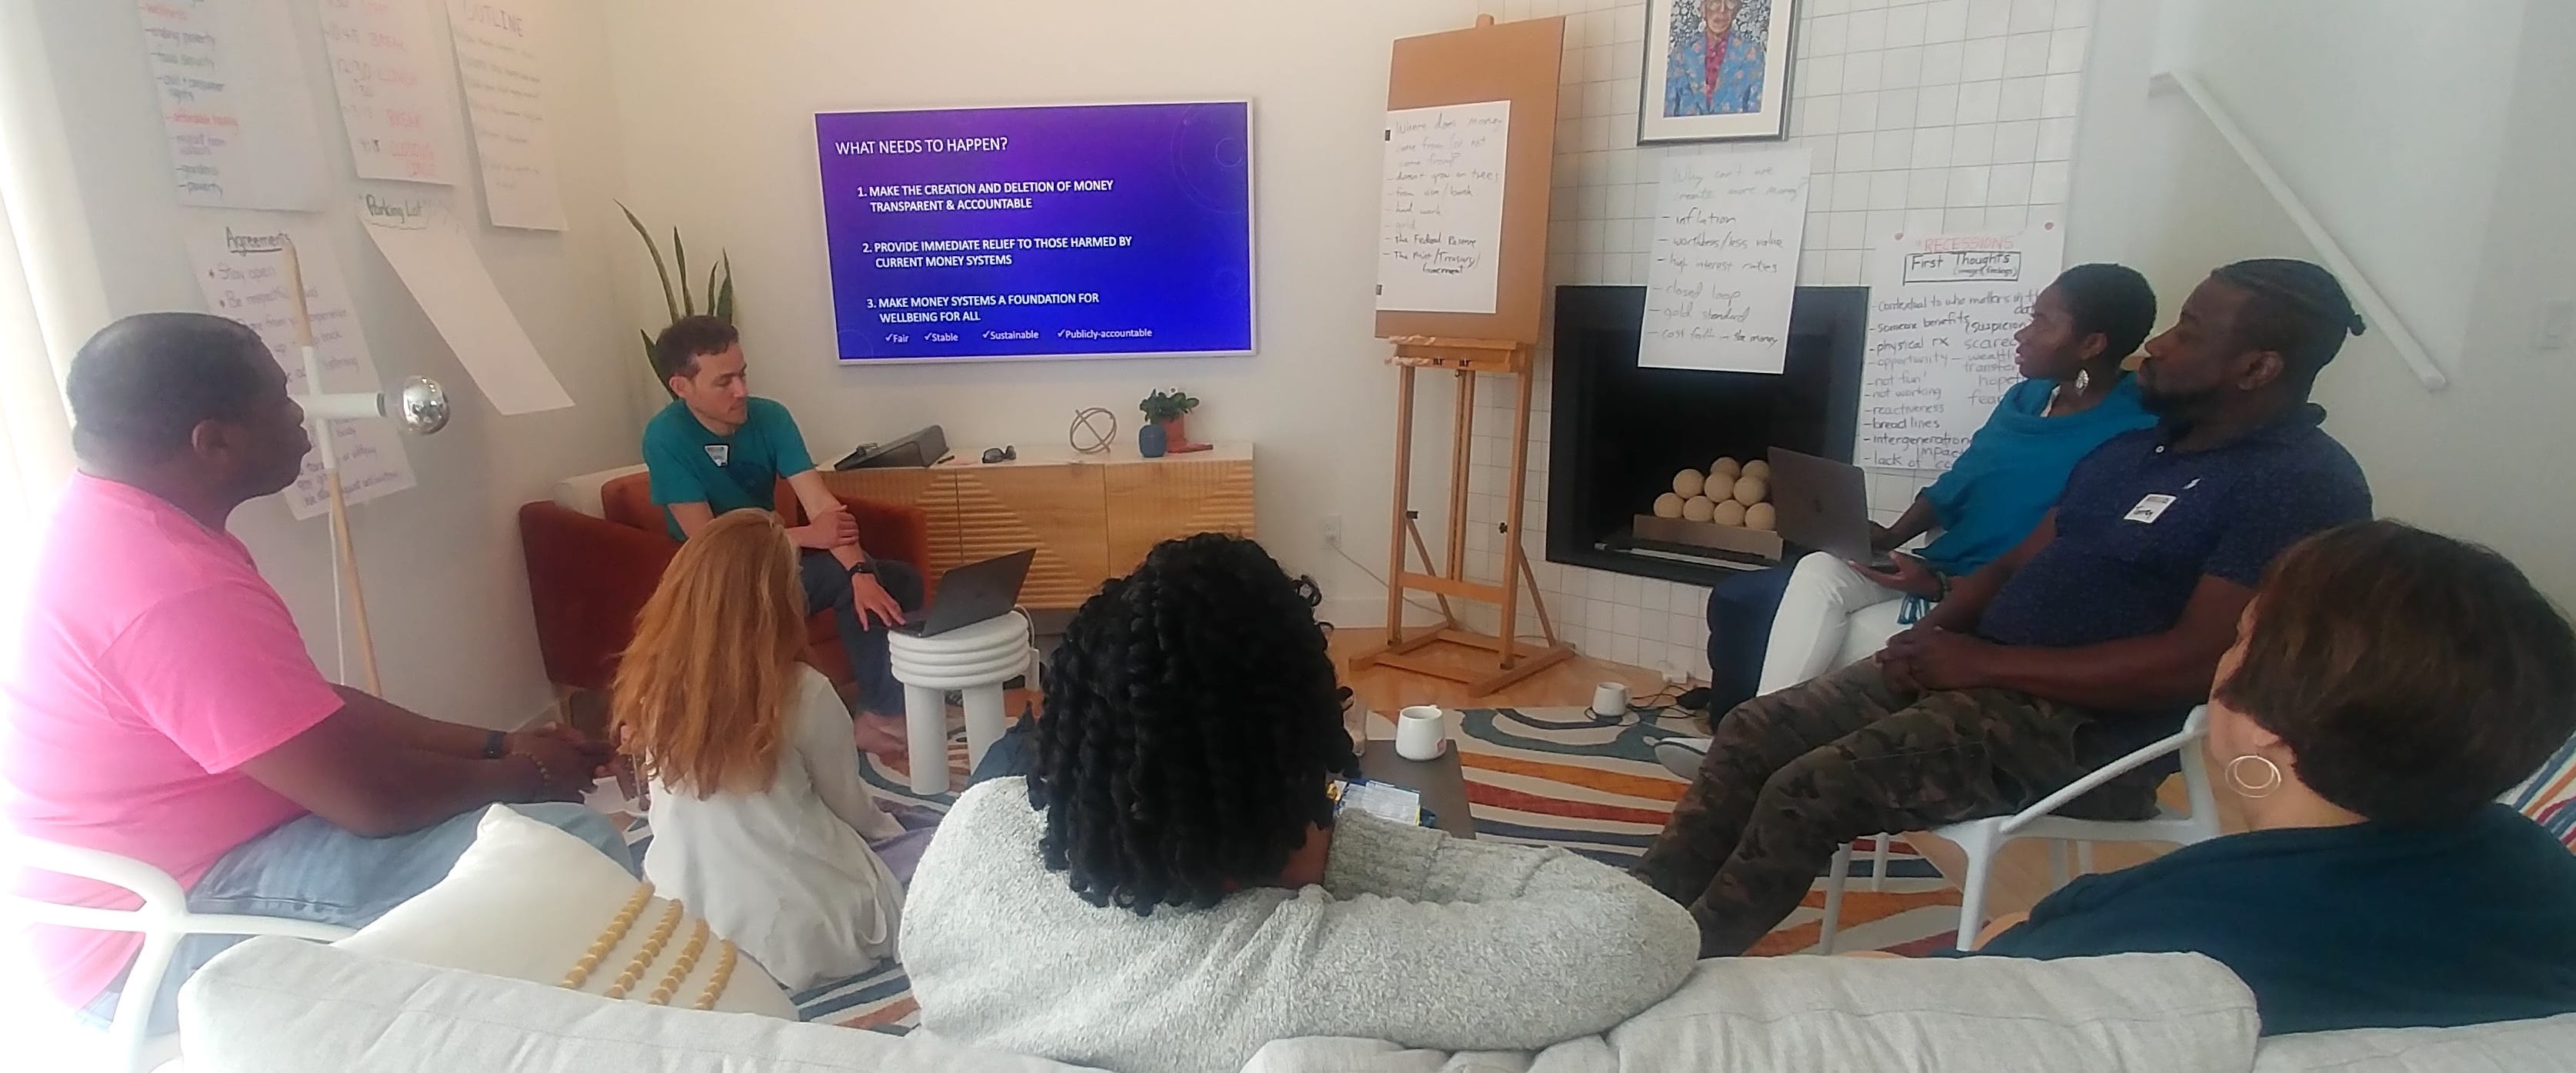
It’s always exciting to see how, during the workshop, participants develop a sense of conviction and empowerment. That is most visible in the incisive questions they ask and the genuine interest they express in knowing more about how things can change and how they can play a part. It’s also evident in the way they name the harms of the current system for themselves. The depth of engagement can also be seen in the range of emotions expressed, such as excitement, relief (from shame and guilt), concern, anger, curiosity, and hope. Sharing these with each other can be therapeutic as well as motivating for staying engaged with each other as the workshop journey continues.
As mentioned earlier, you are welcome to use the recording of this exercise in workshops of your own. If you would like to have the Money Justice Collaborative lead a workshop for your team, you can email us at info@moneyjusticecollaborative.org.
Why this approach sidesteps a few major difficulties
I’m going to share now some of the nitty-gritty of why we think our exercise works so well. I hope these insights will be useful to others teaching about money creation and monetary reform, but I also just think they are fascinating looks into human psychology.
After our “You be the judge!” exercise, it is rare for participants to assert defenses of how money is created today, whereas that is a common response to presentations that start out by teaching how it works today. The psychological discomfort that people feel when simply being confronted with the reality that money creation doesn’t work the way they thought leads many to focus on resolving that discomfort, rather than seeking a solution to any problem “out in the world.” This is a common phenomena dubbed “cognitive dissonance” by psychologists.
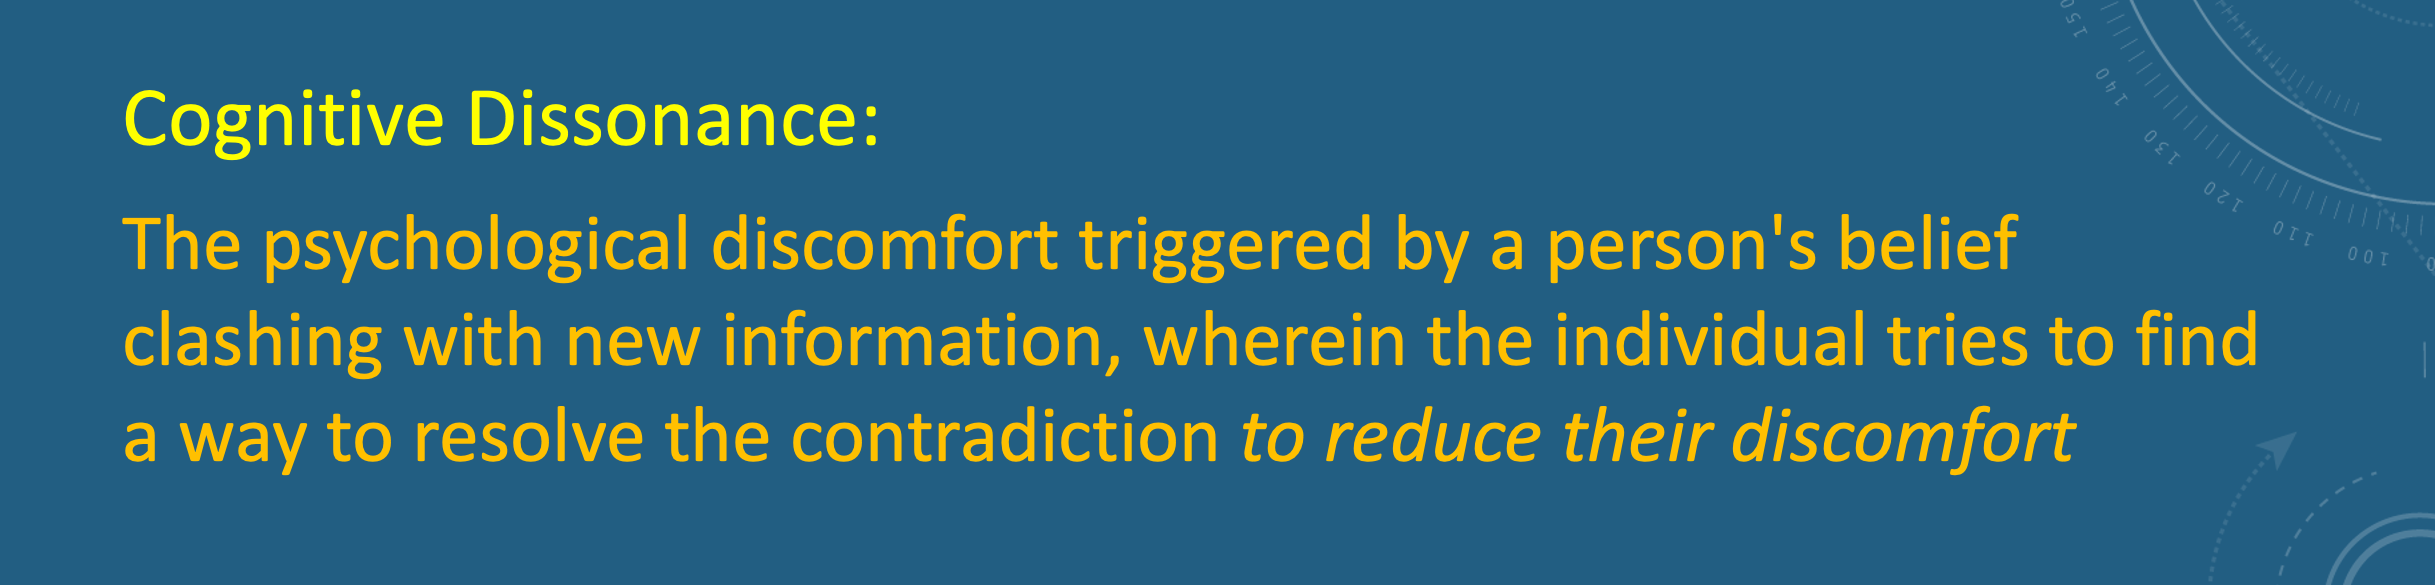
There are two main ways people try to quickly resolve their psychological discomfort. First, by deciding that the way it works today is good, and therefore there is nothing to worry about. Second, by deciding that alternatives are worse, and therefore there is nothing to worry about or change.
These approaches to resolving psychological discomfort show up in common objections, such as these:
“Yes, but bank lending is good because without it nobody could buy a home or get investment for a business.”
“Yeah, but what are the alternatives?”
Starting by showing people alternatives sidesteps a problem that many of us who advocate for changing the way nations create money have discovered: there is often no satisfactory way of answering these questions when they come immediately after describing how money creation works today.
If you answer the first objection by saying there is nothing good about the current solution, you reinforce the person’s belief that you are hiding something, so they cease trusting you as a messenger. Alternatively, you can tell them a few of the genuine reasons why legislators convince themselves to adopt this way of creating money, such as “Governments choose it because they think businessmen will know where to put money into the economy better than the government” or “Governments choose it because they don’t trust themselves to create money.” The problem with these responses is that these arguments sound as reasonable to average people as they do to the policymakers that pass legislation based on them. In the absence of knowing that they prefer alternative solutions, people are often satisfied with these explanations and cease being interested in the problem.
If you answer the second objection by describing one or more alternative ways of creating money, people immediately begin pointing out potential pitfalls in each of those alternatives. The potential pitfalls are real concerns, which you have to acknowledge. But when you do, the person often tunes out, satisfied that there is nothing that needs to be changed about the current system because the alternatives would be problematic too. It doesn’t matter that you can explain to them that the pitfalls they foresee apply equally to the current system, or that there are solutions to those pitfalls, or that the alternatives are better when given a full comparison. Their dismissive response reflects a subconscious tactic known as solution aversion, a psychological phenomena in which people are able to deny a problem if they dislike the solutions to it.
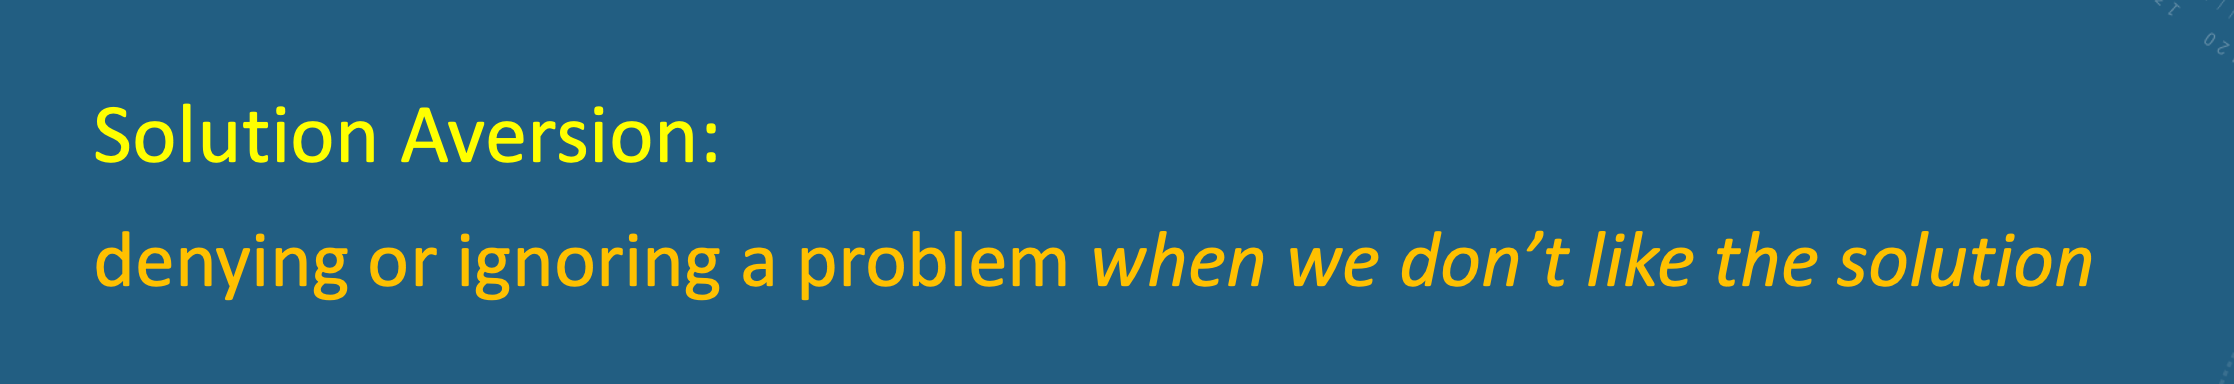
Each of these objections ultimately give the person the ability to settle comfortably into a belief similar to this: “See. The way it works today is actually good, or is better than the alternatives, so I don’t need to be concerned about the fact that I and 85% of people are misinformed about how money is created. It doesn’t matter because there is nothing that needs to be changed.”
This is a psychologically more comfortable belief than the one that we want them to reach, which is more along the lines of, “Wow. The way money is created today is bad and needs to be changed. The fact that people don’t know how it works today is also bad and needs to be changed. I or someone needs to tell people and advocate for change.”
This sequence puts workshop participants in an open mindset, builds self-confidence, empowers with new information, creates social safety, and establishes dissatisfaction with the current way of creating money.
In the case of our workshop, participants don’t encounter the reality that their conception of how money is created is incorrect until several psychologically and socially important things have happened first:
They’ve had their minds opened to the fact that there are many ways money can be created and that they are already aware of several of those ways.
That they can understand different ways of creating money and the advantages and disadvantages of them.
That they have opinions about the different ways money can be created. They prefer some ways over others.
That others have similar opinions to them. They are not alone.
That they and others almost universally dislike the idea that corporations can create money for the purpose of enriching private shareholders.
This sequence puts workshop participants in an open mindset, builds self-confidence, empowers with new information, creates social safety, and establishes dissatisfaction with the current way of creating money. Thus, when participants are confronted with the reality that bank lending creates the money we use today, they already know they dislike it, that other ways of creating money exist, that they prefer some of those other ways, that they are not alone in having those preferences, and that there is general support for changing how it works today. As a result, they don’t feel as much cognitive dissonance and solution aversion has been cleared away by the knowledge of solutions they like.
Groups of people will choose the status quo solution over almost any other solution, no matter how great its benefits, unless they have first become convinced that staying with the current solution is untenable.
Importantly, this approach also does one more psychological and sociological thing: It begins to build a collective conviction among the group that staying with the status quo is unacceptable. Fascinating research conducted on people selling goods and services to corporations found that groups of people (such as committees that decide whether to make big purchases) will choose the status quo solution over almost any other solution, no matter how great its benefits, unless they have first become convinced that staying with the current solution is untenable. For example, they must collectively conclude that the current solution is so harmful, risky, dangerous, costly, ineffective, embarrassing, or obsolete that their only choice is to transition to another solution.
Those advocating for changing how nations create their money often try to achieve consensus that our current system must change by presenting many critiques of the current system. That can work. However, some people are more open to intellectual critiques than others. That is why it can be beneficial to have groups experientially discover the problems with our current money creation system and make the critiques, themselves.
For privacy reasons, we cut out the audience discussions from the recording of the opening of our Money as a Force for Good workshop. Unfortunately, that means you’ll just have to take our word for it that participants do the work of building this consensus by making the critiques themselves. If you’d like to experience it for yourself, try running the workshop yourself or invite the Money Justice Collaborative to run it for your organization or network.
Detailed stories are necessary for people to move beyond knee-jerk reactions.
Some people find it irritating that as we go through the options we don’t give historic or current examples of each of the options being practices in the real world. We do that for another psychological phenomena: guilt by association. Just as there is no perfect way of creating money, there has never been a perfect society. Thus, it is impossible to simply name-drop any historical or current example of a society using a particular way of creating money without inviting critiques associated with that society, more generally. “Oh, the Germans use that system? Well that would never work here because they are socialist.” “Oh, the American Colonies used that system? Well that’s a red flag because they owned slaves and were conducting a genocide of indigenous peoples.”
Later in the workshop, we give detailed stories about several of the alternative ways of creating money. Detailed stories are necessary for people to move beyond knee-jerk reactions. You can always feel the knee-jerk reaction of the audience when you begin telling the detailed story. It comes at the very moment you name the time and place of the story. But as the story unfolds, you can feel people relax and often become excited. Remember that lesson from the “You be the judge!” game: the details matter!
What to do when talking to someone outside of a workshop context?
Of course, if reforming our national currencies required dragging everyone into a workshop, it could never happen. So, how do you get people to have a similar experience, quickly? Here’s what I say to people when they ask me what I do.
My Elevator Pitch for Monetary Reform
“I study how nations create their currencies. Not just physical cash, but also the money that only exists as numbers in bank accounts. Like, how does each additional unit of Dollar or Euro or Yen come into existence, exactly? [I often pause here for a beat because some people want to venture a guess.] It turns out that humans have developed many ways of creating the money they use, and some are much better than others. Since 2008 a wave of research has revealed that our current system is intensifying many of the crises we are facing, like inequality and climate change. It also shows that much better ways of creating money exist. That’s why myself and policy people at Harvard Law School and Cornell Law School, and think tanks and advocacy organizations are all pushing to change how it works today.”